



India’s consumption story is changing shape. The next leg of growth may not come from millions of new consumers entering the market, but from affluent consumers spending significantly more on what they already buy.
Knight Frank estimates that India had 19,877 ultra-high-net-worth individuals (UHNIs) with net worths above $30 million (~₹285 crore) in 2026. That is 63% higher than five years ago. The number is expected to cross 25,000 by 2031.
The high-net-worth population is also increasing. As per the Capgemini World Wealth Report 2026, wealth concentration among the rich in India increased by 4.6% to $1.64 trillion (around ₹156 lakh crore) in 2025.
The growth in India’s affluent population is creating a larger pool of consumers capable of spending disproportionately on high-ticket goods and services. For investors, this creates an interesting opportunity. While many large companies are increasing their exposure to premium products to capture this shift, a few smaller listed companies are much more directly exposed to this theme.
Join now
Two Small-Cap Stocks Riding the Same Premiumisation Trend
At first glance, Ethos and Raymond Realty have little in common. One sells luxury watches; the other develops premium and luxury homes. But both are benefiting from the same shift: affluent Indians are increasingly willing to spend more on high-value purchases.
Ethos Limited: Selling More Expensive Watches
Ethos is an authorised retailer of many luxury watches, including Rolex, Omega, IWC Schaffhausen, Jaeger-LeCoultre, Panerai and other Swiss majors. The company has spent the last few years deliberately tilting its mix toward the top end of that portfolio.
It operates 100 watch boutique stores across 34 cities, and retails 85 watch brands, of which it has exclusive selling rights for 64 brands in India. The financial performance also indicates strong growth.
Premiumisation Is Showing Up in the Numbers
The latest numbers show that the premium end of the market continues to grow. In FY26, Ethos’ consolidated revenue rose 28.8% YoY to ₹1,612 crore. However, profitability moderated as forex fluctuations, along with higher employee and rental costs from new store additions, weighed on margins and earnings.
Ethos Financials: Top-Line Surges
| Metrics | FY25 | FY26 | Change |
| Revenue from Operations(₹ crore) | 1,251.6 | 1,612.2 | 28.8% |
| EBITDA Margins (%) | 16.8% | 15.3% | -150 bps |
| Net Profit (₹ crore) | 96.3 | 96.2 | -0.1% |
Ethos Ltd.: Quarterly Financial Performance
| Metrics | Q1FY26 | Q1FY27 | YoY Growth |
| Revenue from Operations(₹ crore) | 346.3 | 461.7 | 33.3% |
| EBITDA Margins (%) | 14.8 | 15.7 | 90 bps |
| Net Profit (₹ crore) | 19.1 | 28.7 | 50.3% |
The momentum picked up in Q1FY27. Consolidated revenue grew 33.3% YoY to ₹461.7 crore, while EBITDA increased 44.1% to ₹74.8 crore. As a result, EBITDA (Earnings Before Interest, Tax, Depreciation, Amortisation) margin expanded by 90 basis points to 15.7%.
More importantly, the underlying metrics point to continued premiumisation. Luxury and high-luxury watches accounted for 71% of Ethos’ watch sales in Q1FY27, unchanged from FY26 but significantly higher than 65% in FY22. At the same time, the average selling price of watches has increased from ₹1.49 lakh in FY22 to ₹2.26 lakh in Q1FY27, roughly a 52% increase over the period.
The growth in average selling price of watches is supported by aggressive expansion in store count. It has increased from 94 boutiques across 30 cities at the end of FY26 to 103 boutiques across 34 cities by the end of Q1FY27, including entries into tier-2 markets such as Agra, Amritsar and Visakhapatnam.
There is another leg to Ethos’ luxury strategy: the pre-owned market. Its Certified Pre-Owned (CPO) business grew 22.9% YoY in FY26. The company also opened a dedicated CPO boutique during the period.
Ethos can grow revenue through a combination of higher transaction values, premium mix and store expansion, rather than relying solely on a sharp increase in customer volumes.
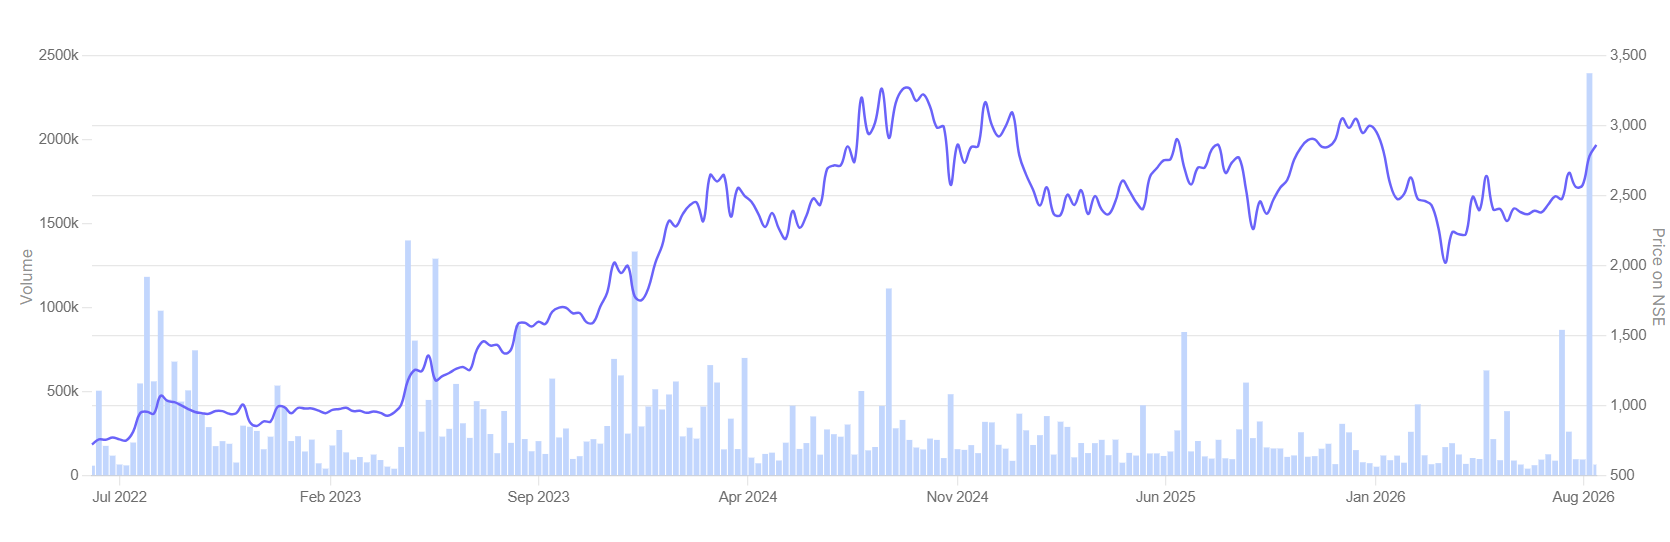
The operating improvement has also translated into a significant rerating of the stock. Since its listing in March 2022, Ethos stock price jumped nearly four times, from around ₹721 to a record high of ₹3,259. As of August 10, 2026, it is trading at around ₹2,870.
Ethos Ltd.: 5yr Stock Price Chart
Raymond Realty: Premiumisation With a Bigger Ticket
Raymond Realty is riding the same premiumisation trend as Ethos, but with a much bigger ticket size. The company has steadily moved up the residential market, from its first project in Thane to premium developments under its ‘The Address by GS’ brand and, more recently, luxury projects across Mumbai.
The premiumisation is visible not just in Raymond Realty’s project names, but also in the ticket size of the homes it is selling. As per the company presentation, The Address by GS has an average ticket size of around ₹3.2 crore. At the luxury end, Invictus by GS in BKC has an average booking value of roughly ₹7.6 crore, while Invictus by GS Tower A and Tower B are at around ₹5.4 crore and ₹5.9 crore, respectively.
Raymond Realty currently has a ₹52,000 crore Gross Development Value (GDV) portfolio, giving significant revenue visibility. It is also pursuing joint development agreements (JDAs) across the Mumbai Metropolitan Region (MMR).
The joint development agreement model is becoming increasingly important. Instead of tying up large amounts of capital in land acquisition, Raymond Realty partners with landowners and develops projects through these agreements.
Financials: Growth Is Accelerating
The numbers show how quickly the business is scaling. In FY26, consolidated revenue from operations rose nearly 29% to ₹2,991 crore. EBITDA margin declined during the period by 230 bps to 16.3%. Management attributed the margin decline largely to project mix, with newer projects typically carrying lower margins in the early stages.
Raymond Realty: Financial Performance
| Metrics | FY25 | FY26 | Change |
| Revenue from Operations(₹ crores) | 2,320.0 | 2,991.0 | 28.9% |
| EBITDA Margins (%) | 18.6% | 16.3% | -230 bps |
| Net Profit (₹ crores) | 274.0 | 305.0 | 11.3% |
Raymond Realty: Quarterly Financial Snapshot
| Metrics | Q1FY26 | Q1FY27 | YoY Growth |
| Revenue from Operations(₹ crores) | 381.0 | 527.0 | 38.3% |
| EBITDA Margins (%) | 11.0 | 13.0 | 200 bps |
| Net Profit (₹ crores) | 16.0 | 13.0 | -18.8% |
The momentum has carried forward into FY27. Q1FY27 revenues from operations grew 38.3% YoY to ₹527 crore. EBITDA margin grew 200 bps to 13%. During the period, pre-sales were up 129% YoY to ₹700 crore while customer collections were up 47% to ₹550 crore. Pre-sales represent the value of homes booked during the period, while collections represent the cash received from customers. Revenue is recognised as projects progress and meet the accounting criteria for revenue recognition.
In the case of Raymond Realty, the surge in pre-sales points to strength in demand and creates visibility of future revenues, while collections provide evidence of cash conversion. The revenue and profit reported will be as projects advance and revenue is recognized.
Management Outlook
Management is targeting around 20% annual growth in pre-sales and revenue, along with around 20% return on capital employed. It is also targeting an EBITDA margin of 17-19% in FY27, suggesting that the current margin expansion still has room to continue.
That combination of premium housing, a large visible pipeline, an asset-light expansion model and relatively disciplined leverage makes Raymond Realty an interesting way to play India’s premiumisation trend through real estate. The key question remains whether the company’s large GDV pipeline can be converted into bookings and collections at the pace management expects.
Why the Stock Hasn’t Kept Pace With the Numbers
Despite strong operating numbers, Raymond Realty’s stock has lagged. Post demerger from Raymond in July 2025, the stock fell from ₹969 to make a low of ₹349 in March 2026. The stock has rebounded since and is now trading at ₹632 as of August 10, 2026.
Raymond Realty: Stock Price Chart
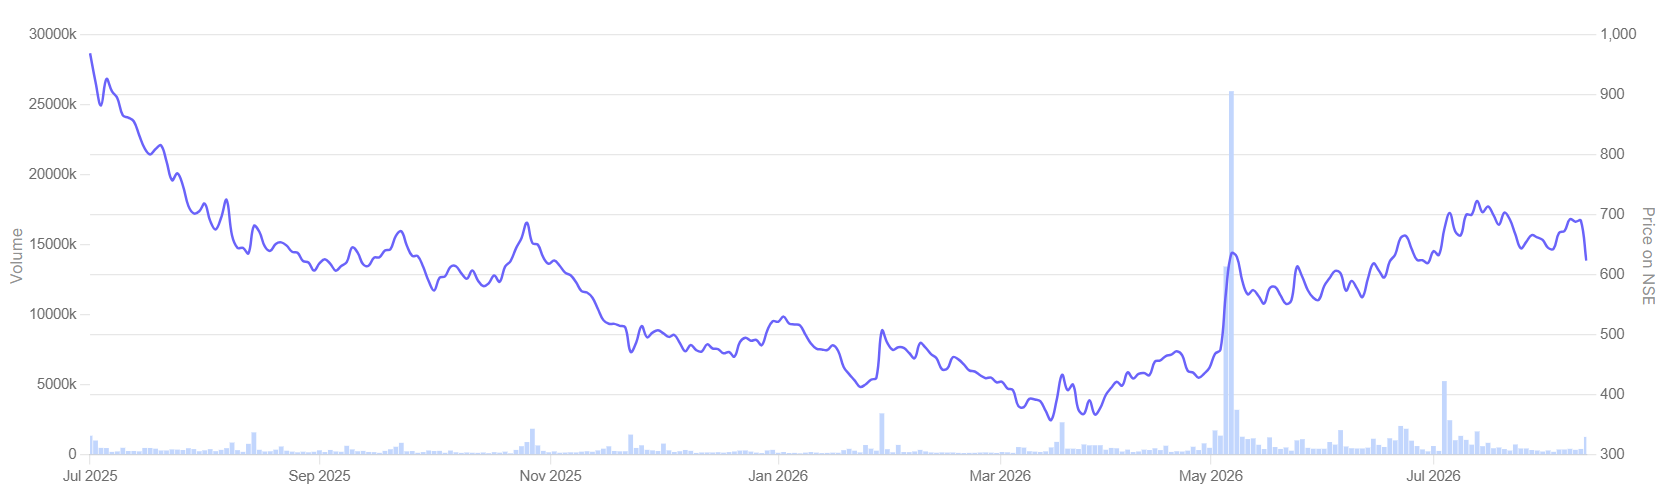
Three factors explain the gap: a weak post-demerger start, a lag between strong bookings and reported profits, and broader weakness in real estate stocks. In Q1FY27, net profit fell 18.8% YoY, as higher construction and marketing costs weighed on earnings. At the same time, the Nifty Realty index has also remained under pressure.
Two Premiumisation Plays, Two Very Different Valuations
It is no more a secret that many listed companies are betting on premiumisation for earnings recovery and growth. As incomes rise and the number of affluent consumers expands, spending is likely to shift further towards luxury watches, premium homes and other high-value products.
Ethos and Raymond Realty offer two very different ways to play this trend. But they have very little in common. One sells luxury watches and the other luxury apartments.
Ethos is the purer premium-consumption play, with strong growth in luxury watches and rising spending per customer. It is trading at a price-to-earnings (PE) multiple of 72.6x, as of August 10, 2026, and the market has already priced in a lot of future growth. Any slowdown in growth can impact future stock returns.
The market’s growing confidence in the story is also visible in institutional ownership. Institutional investors held nearly 35% of Ethos at the end of June 2026, more than double the 16.3% stake held in September 2023.
Raymond Realty, on the other hand, trades at around 14x earnings. That is significantly lower than peers such as Lodha Developers, which trades at nearly 30x earnings. Not to forget, Raymond Realty has further room for margins to improve with a large premium housing pipeline.
How the Two Stocks Compare
| Ethos | Raymond Realty | |
| Theme | Luxury consumption | Premium housing |
| Revenue growth | 28.8% FY26 | 28.9% FY26 |
| Q1FY27 revenue growth | 33.30% | 38.30% |
| Q1FY27 profit growth | 50.3% | -19% |
| Key operating metric | ASP + premium mix | Pre-sales + collections |
| Valuation (Aug 10, 2026) | ~72.6x PE | ~14x PE |
| Key risk | Valuation/execution | Earnings conversion/execution |
Ethos offers the cleaner premium-consumption story, where investors are paying upfront for years of growth. Raymond Realty offers the opposite setup: a large premium housing pipeline, strong bookings and improving margins, but much of earnings growth depends on execution.
That makes the two stocks less of a direct comparison and more of a choice between two different kinds of premiumisation bets. Ethos is a bet on continued growth in affluent consumption. Raymond Realty is a bet that strong bookings and its large development pipeline will eventually translate into earnings and cash flows. Add these stocks to your watchlist and monitor how they execute their growth plans.
Disclaimer:
Note: We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Deepan Datta has spent over a decade studying stocks and mutual funds. His passion is to uncover interesting stories in the financial markets and share them through his writings with investors at large. He is focused on delivering clear, easy to understand and research-backed insights. Deepan began his career as a Research Associate at S&P Global, where he developed a strong foundation in financial research and data analysis.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, their employees (s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.