



India’s mobile phone manufacturing industry is entering a different phase. The country has already emerged as the world’s second-largest mobile phone manufacturer. Mobile phone production has risen 33x, from around ₹18,900 crore in FY15 to around ₹6.3 lakh crore in FY26. Mobile phone exports have also increased from ₹1,566 crore to ₹2.6 lakh crore during the same period.
Yet, the next leg of growth will depend not just on producing more phones, but on how much of the value chain India can capture. This is where the government’s new Mobile Phone Manufacturing Scheme, or PLI 2.0, comes in. With an outlay of ₹62,500 crore from FY27 to FY31, the scheme shifts the focus towards incremental sales, exports and higher domestic value addition.
The scheme has two target segments: TS1 (mobile phone manufacturing) and TS2 (Indian mobile phone brands). Under TS1, the Scheme provides a differentiated incentive ranging from 2.25% to 5%. TS2 (which may provide a 1-year gestation period), meanwhile, provides a 5% incentive to eligible Indian brands, along with an additional 3% incentive for Indian design and research and development.
The incentive does not stop at higher production. Both segments can receive an additional incentive of up to 1.5% for domestic sourcing of key components. This makes localization an important part of the scheme, alongside the push for higher production and exports. At the same time, the government has kept the scheme focused on companies with scale.
Join now
The FY26 Qualification Hurdle: How Scale Dictates PLI Success
Large manufacturers and EMS players need a minimum FY26 turnover of ₹10,000 crore to qualify under TS1. Existing brands must then achieve at least ₹5,000 crore of incremental sales every year over their FY26 sales base.
New brands, meanwhile, become eligible after reaching ₹10,000 crore in annual sales, following which they must meet the incremental sales targets. If the turnover is low, an electronics manufacturing company or a mobile phone manufacturer will be eligible for TS2 if it has a minimum turnover of ₹1,000 crore in FY26.
This is subject to the scheme’s conditions, including meeting all criteria for an Indian brand. This creates an opportunity for Indian companies still building mobile manufacturing capabilities to participate as the domestic electronics ecosystem expands.
Against this backdrop, we look at one major beneficiary of mobile manufacturing scale-up and another company that is building a new opportunity in the segment.
#1 Dixon Technologies
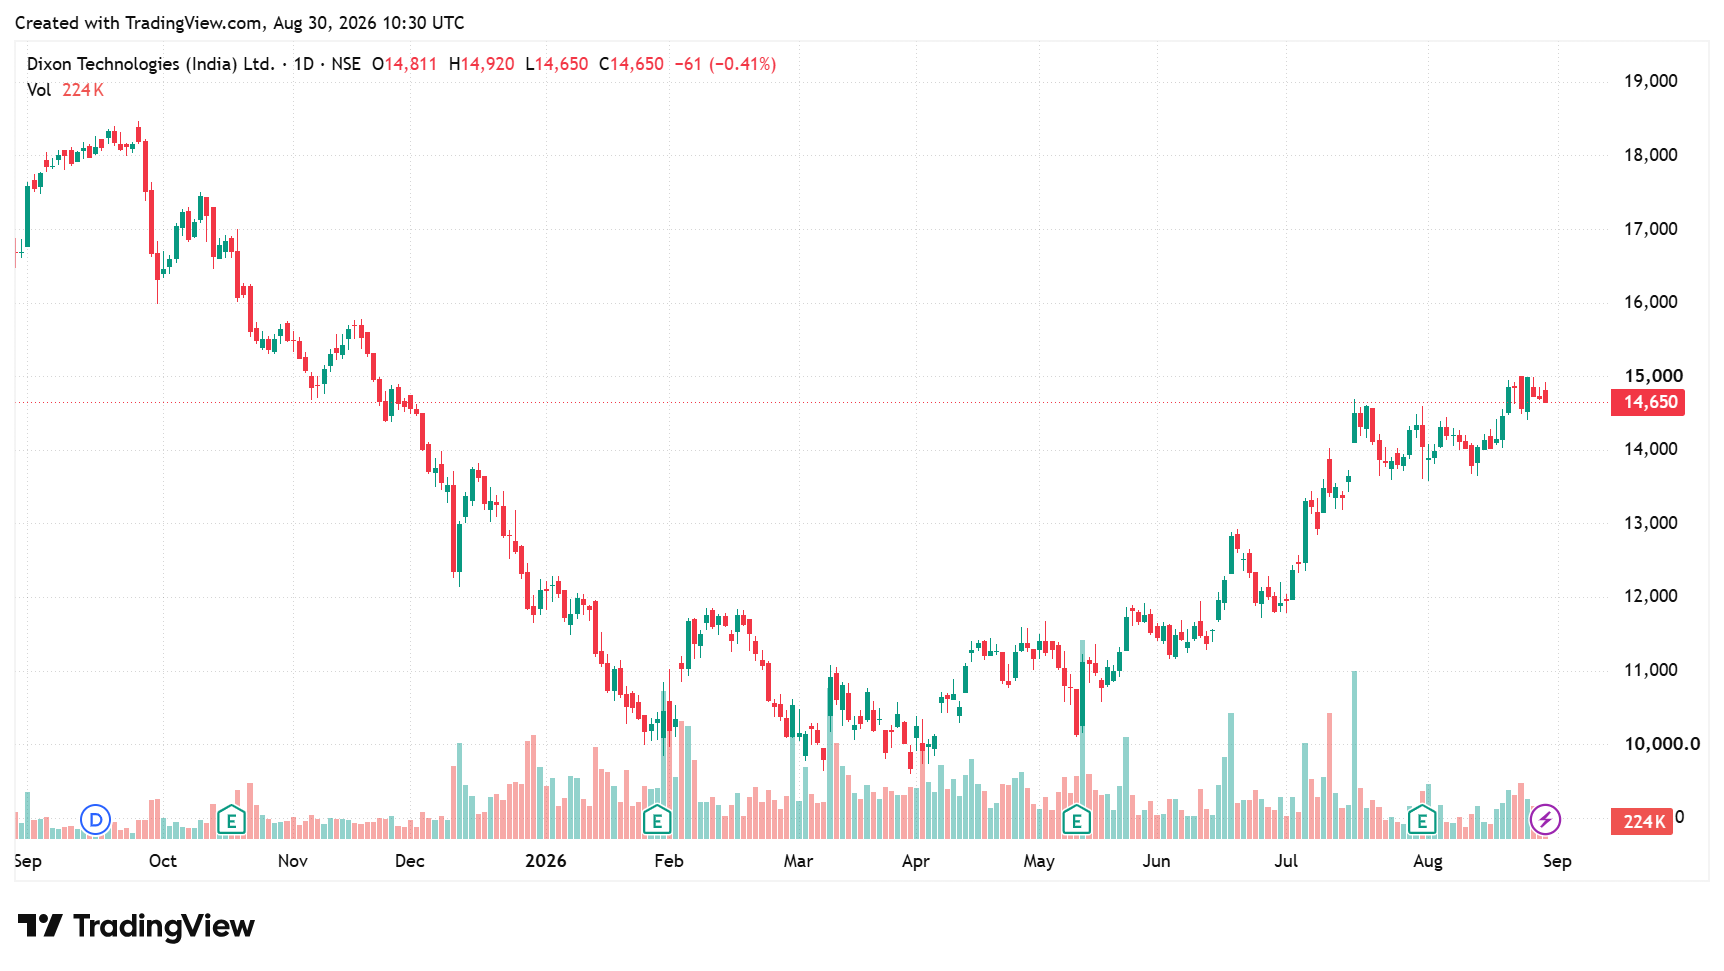
The Mobile & Other EMS Division is the largest and key contributor to Dixon Technologies’ business portfolio. Revenue for the Mobile & Other EMS Division reached ₹14,179 crores in Q1 FY27, up from ₹11,663 crore in Q1FY26. These sales put Dixon in a strong position to benefit from the scheme.
Operating profit, however, fell year-on-year to ₹373 crore in Q1FY27, compared to ₹395 crore in Q1FY26 as margins fell 76 bps to 2.6%. Margin compression was driven primarily by two factors. The closure of the Mobile PLI 1.0 scheme incentives in March 2026 and rising global memory and component prices.
Rising prices have slowed the domestic smartphone market, which shrank by 10% to 12% in the quarter. Despite this, Dixon maintained its volume levels and gained market share from competitors. The company manufactured 75 lakh smartphone units in Q1FY27. Dixon exported 6-7 lakh units during Q1FY27, with export revenue at ₹1,100 crores.
Why the Upcoming Vivo Consolidation is Critical for FY27 Volumes
Dixon expects a strong volume rebound in Q2FY27, forecasting 20% to 25% smartphone volume growth QoQ as consumer demand recovers. The Q2FY27 order book is robust, standing at 90 to 92 lakh units. Dixon is confident it will close H1FY27 at around 1.6 crore units and the full year at 3.2 crore units. The guidance excludes the Vivo volumes.
Effectively, the volume would be flat compared to last year despite industry-wide degrowth. In July 2026, Dixon received approval for its joint venture with Vivo. Revenue is expected to be consolidated in Dixon’s financials from Q3FY27. Dixon’s new manufacturing facility in Noida is scheduled to be commercialized in Q3FY27.
To further strengthen localization and support captive smartphone assembly, the company is also pursuing backward integration. Dixon is expanding its annual camera module capacity from 7.0 crore units to 18-19 crore units over the next 15 to 18 months. Mass production of displays (mobile, IT hardware, and automotive) is scheduled to start in early Q4FY27.
How PLI 2.0 Margins Will Reward Dixon’s Backward Integration
Dixon expects the Mobile PLI 2.0 scheme to be a major growth catalyst. Expected volume-based incentive rates will range between 2.5% and 5%. The upper band of 5% is designed to aggressively incentivize brand owners to shift global export bases to India. Backward integration into cameras and displays will make Dixon eligible for incremental incentives.
The Hidden Value of Capturing Global Feature Phone Exports
Dixon’s management is working closely with its two main anchor customers to target the export market. Dixon estimates that PLI 2.0 could help add 1.5-2.0 crore units to export volumes. This could increase revenue by ₹18,000 crore to ₹20,000 crore over the next few years.
Moreover, Dixon remains India’s largest feature phone manufacturer, accounting for nearly 66.7% of all feature phones produced domestically. One of Dixon’s anchor customers is shifting its global feature phone export base to India.
#2 Amber Enterprises
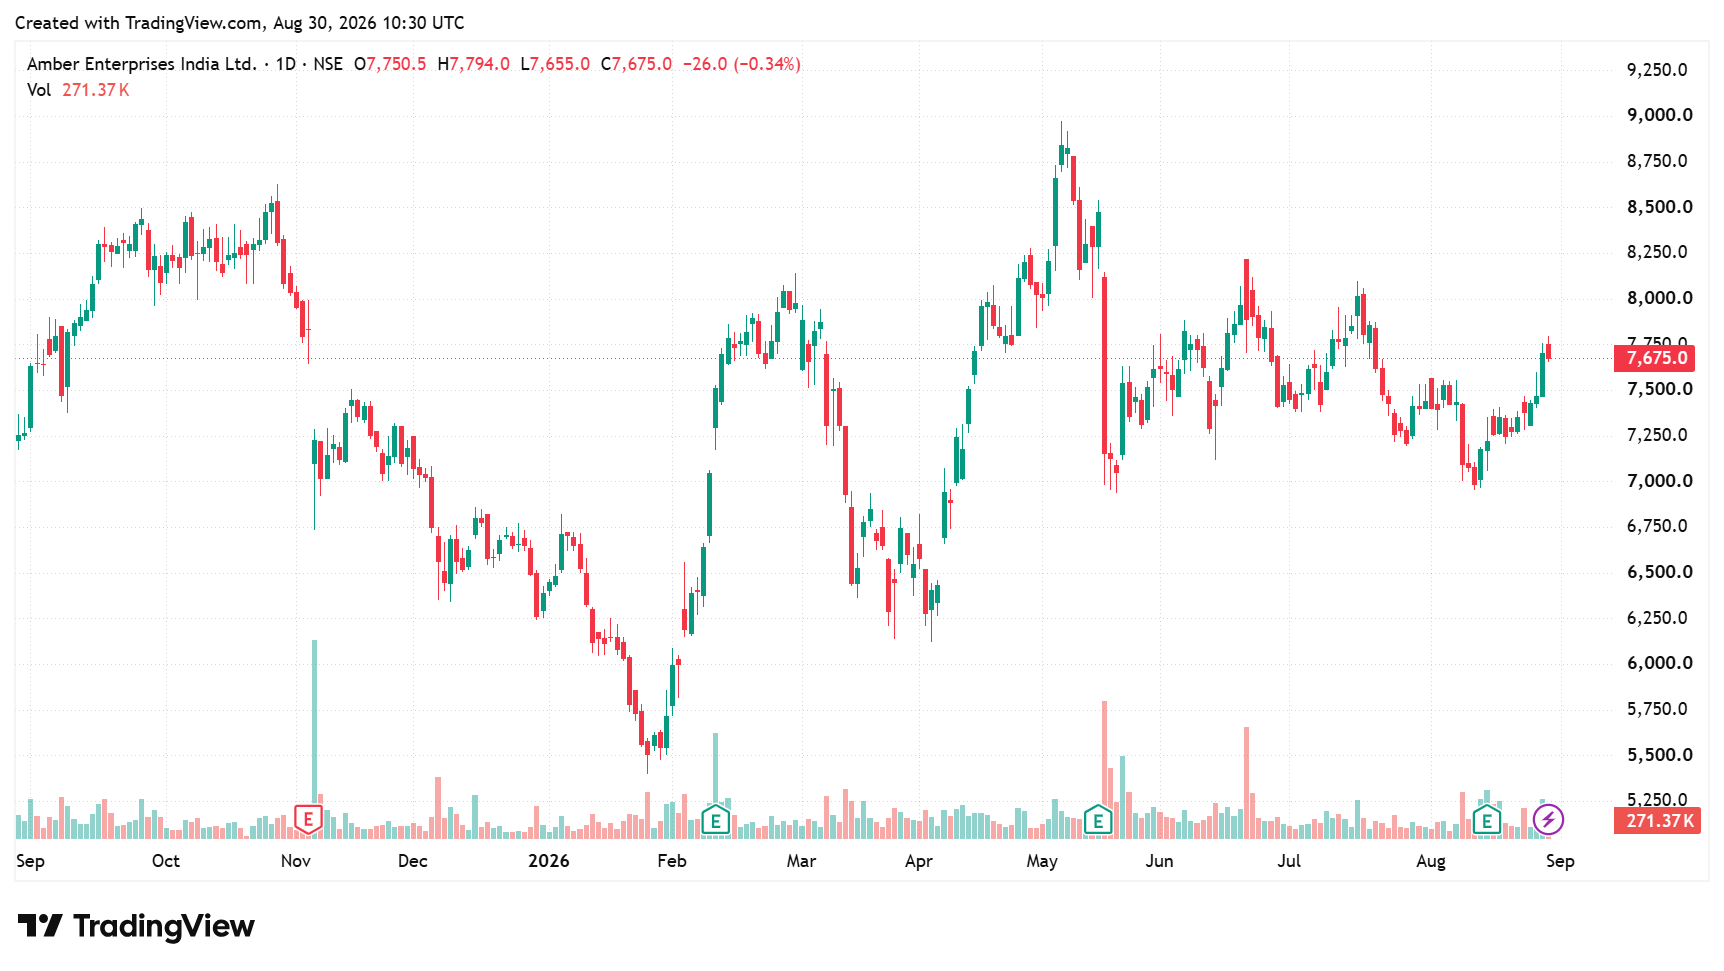
Amber Enterprises has expanded into India’s mobile phone manufacturing sector. On June 18, 2026, the Amber Group collaborated with Oppo Mobiles. This partnership represents Amber’s foray into the highest-volume consumer electronics category. The collaboration covers three major global smartphone brands (OPPO, OnePlus, and Realme) under the BBK Group umbrella.
At this juncture, Amber has no manufacturing arrangements with other major brands such as Vivo. The company intends to take small steps to stabilize operations and execute the targeted scale successfully. Thereafter, it will explore partnerships with other smartphone brands.
The collaboration is structurally designed to be asset-light, capital-efficient, and low in working capital intensity. The capital outlay to start assembly and SMT (Surface Mount Technology) operations is estimated to be below ₹50 crore. The manufacturing will be carried out at an existing facility under a sublease arrangement with Oppo India.
Why the FY28 Scale-Up is Crucial for Amber’s Mobile Ambitions
Amber and Oppo have established a calibrated phase-wise ramp-up timeline. Trial production is scheduled to begin in Q4FY27, with commercial production set to start in Q1FY28. In FY28, Amber expects to manufacture around 80 lakh units. This volume represents roughly 20% to 30% of Oppo India’s total volume.
Thereafter, volumes are expected to nearly double in FY29 to a projected range of 1.3-1.6 crore units as operations stabilize and scale. Amber aims to progressively capture higher-margin component business. In Phase-1, Amber will start with final assembly and SMT (surface mount technology) operations.
In phase-2, the company will begin integrating High-Density Interconnect Printed Circuit Boards into the assembly. By then, the HDI plant (developed under the Ascent-K JV with Korea Circuit) will be operational. From year 3 and onwards, Amber plans to localize manufacturing of other components into its ecosystem.
How PCB Integration Will Drive High-Margin Value Addition
Amber’s goal is to increase local value addition to 35% to 40% over the next 5 to 6 years, up from 10-12% in the mobile assembly industry. Management estimates initial margin to remain at 1.5-2%. However, margins are expected to rise as localized component integration (such as PCBs, which carry higher standalone margins of 15% to 16%) increases over time.
This collaboration would diversify the company’s revenue mix and offset the seasonal nature of its room air conditioner business. Amber qualifies for the ₹10,000 crore FY26 turnover criterion under TS1, with FY26 revenue of ₹12,186 crore. The company could also benefit as it ramps up smartphone and component manufacturing.
Evaluating Capital Efficiency: Premium Valuations vs Industry Medians
Dixon boasts strong Return on Capital Employed (ROCE) and Return on Equity (ROE) due to its faster growth than Amber. On valuation, Amber trades at a significant premium to both its 3-year historical median P/E multiple and to the industry median. Dixon, meanwhile, trades at a discount to its historical median and at a premium to the industry median.
| Peer Comparison (X) | |||||
| Price-to-Earnings Multiple | Return Ratios | ||||
| Company | Company | 5Y Median | Industry | ROCE (%) | ROE (%) |
| Amber | 131.0 | 91.7 | 38.8 | 10.3 | 6.0 |
| Dixon | 47.7 | 116.1 | 42.3 | 42.0 | 37.4 |
| Source: Screener.in (As of August 28, 2026) | |||||
For Dixon, PLI 2.0 could be more than an incentive support. The company expects the scheme to add 1.5-2 crore units to its export volumes. This potentially translates into ₹18,000–20,000 crore of additional revenue over the next few years. Its backward integration into camera modules and displays could further improve the incentive capture as localization increases.
Amber, meanwhile, is starting from a smaller base, but its mobile business offers a new growth avenue. With volumes targeted to rise from around 80 lakh units in FY28 to 1.3-1.6 crore units in FY29, the company aims to gradually move into higher-value components. Management is also targeting 35-40% local value addition over the next five to six years.
Meanwhile, it’s worth keeping these on your watchlist.
Disclaimer:
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation. We used an alternative, widely accepted source of information only when the data were unavailable.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
About the Author: Madhvendra has been deeply immersed in the equity markets for over seven years, combining his passion for investing with his expertise in financial writing. With a knack for simplifying complex concepts, he enjoys sharing his honest perspectives on startups, listed Indian companies, and macroeconomic trends.
A dedicated reader and storyteller, Madhvendra thrives on uncovering insights that inspire his audience to deepen their understanding of the financial world.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives and resources, and only after consulting any independent advisors as necessary.