



Growth is one of the clearest indicators of how a business has expanded over time. A company that sustains strong revenue growth for seven years has usually moved beyond a temporary demand surge or a favourable quarter. It suggests that the business has been able to increase its scale across different market conditions.
However, growth supported by excessive borrowing carries additional risk. Higher debt increases interest costs and can weaken the balance sheet when demand slows. Companies that combine long-term sales growth with low leverage therefore stand apart. They have expanded without placing disproportionate pressure on their finances.
In this article, we look at five Indian companies that have delivered strong seven-year sales growth while maintaining manageable debt-to-equity levels through this period; the current debt-to-equity level should be below 0.25 times. The idea is to identify established businesses where expansion has been accompanied by a relatively conservative balance sheet.
For the initial screen, we considered companies with a market capitalisation above Rs 5,000 crore and annual sales exceeding Rs 100 crore. Their seven-year sales CAGR had to be above 20%. We only considered companies that have declared Q1 FY27 results.
We then examined the latest balance sheets and retained only companies with current debt-to-equity below 0.25 times. SG Mart was excluded because its older financial data relates to a substantially different business and is not comparable with its present operations.
Join now
#1 Waaree Renewable Technologies: Scaling Solar EPC Without Heavy Debt
Incorporated in 1999, Waaree Renewables Technologies is engaged in the business of generation of power through renewable energy sources and also provides consultancy services in this regard.
Waaree Renewable Technologies Financial Performance
| Key metric | Value |
| 7-year sales CAGR | 152.9% |
| Q1 FY27 revenue | Rs 924.3 crore, up 53.2% |
| Q1 FY27 net profit | Rs 119 crore, up 37.7% |
| Debt-to-equity ratio | 0.12 |
Waaree Renewable Technologies has emerged as one of the fastest-growing companies in the screen, with a seven-year sales CAGR of 152.9%.
The company reported strong figures in Q1 FY27. Revenue increased 53.2% year-on-year (YoY) to Rs 924.25 crore, while profit after tax grew 37.7% to Rs 119 crore. The company executed 888.8 MWp during the quarter. Its operations and maintenance portfolio stood at 1.15 GWp.
Growth visibility comes from a consolidated unexecuted order book of Rs 5,300 crore across solar EPC and transmission and distribution. Management expects this book to be executed over 12–15 months. It is also pursuing a 27 GW domestic solar pipeline and around 10–11 GW internationally.
Operational Execution vs Acquisition Risks
Waaree has acquired a 55% stake in Associated Power Structures, adding substations, transmission lines and 108,000 tonnes of annual fabrication and galvanising capacity. The deal extends its presence from solar construction into grid and power-evacuation infrastructure.
At March 2026, borrowings were Rs 115 crore against equity and reserves of Rs 940 crore, giving a debt-to-equity ratio of 0.12 times. However, this predates the acquisition, which was funded about 75% through debt. Return on capital employed (RoCE) stood at 85.4% and return on earnings (RoE) at 69.1%.
The stock trades at 13 times EV/EBITDA, below its five-year average of 30.5 times and the peer median of 21 times. The next test is whether the company can absorb the acquisition while protecting margins and its low-leverage profile.
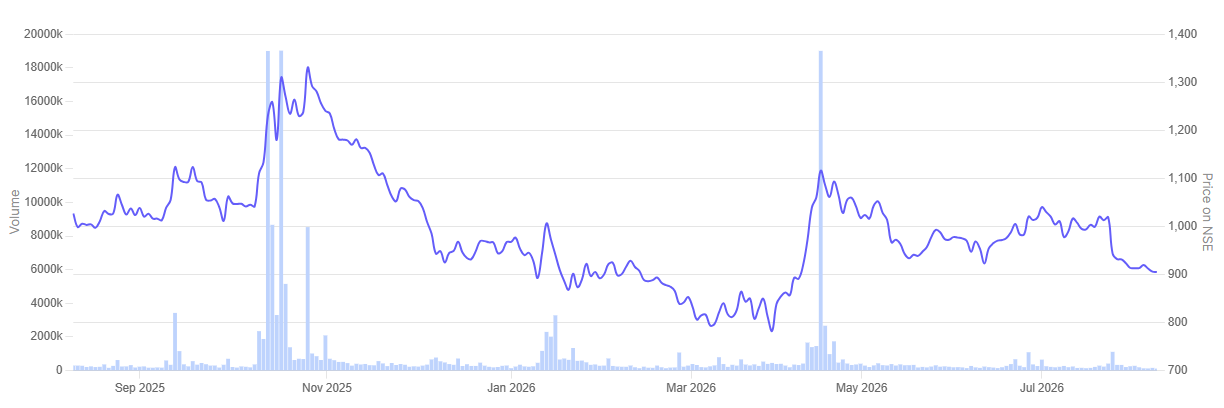
In the past year, the share price of Waaree Renewable Technologies is down 11.7%.
Waaree Renewable Technologies 1 Year Share Price Chart
#2 Eternal: Quick Commerce Drives the Next Growth Leg
Incorporated in 2010, Eternal, formerly known as Zomato, is one of the leading online food service platforms in terms of the value of food sold. Its offerings include food delivery, dining-out services, loyalty programs, and others. The expansion has been driven by food delivery and, more recently, Blinkit’s rapid scale-up in India’s growing retail-tech market.
Eternal Financial Performance
| Key metric | Value |
| 7-year sales CAGR | 70.2% |
| Q1 FY27 revenue | Rs 20,211 crore, up 182% |
| Q1 FY27 net profit | Rs 92 crore, up 268% |
| Debt-to-equity ratio | 0.15 |
Eternal has recorded a seven-year sales CAGR of 70.2%, placing it among the fastest-growing companies. The expansion has been driven by food delivery and, more recently, Blinkit’s rapid scale-up in quick commerce.
Revenue from operations jumped 182% YoY to Rs 20,211 crore in Q1 FY27. Net profit rose 268% to Rs 92 crore. Blinkit became the largest revenue contributor and reported a positive adjusted EBITDA of Rs 102 crore.
Quick Commerce Scaling and Unit Economics
The company added 200 Blinkit stores during the quarter, taking the network to 2,443 stores. Blinkit’s net order value grew 86.2%, led mainly by customers ordering more frequently. Management expects its long-term adjusted earnings before interest, tax, depreciation, and amortisation (EBITDA) margin to reach the upper end of the earlier 5–6% guidance, though it has not given a timeline.
Food delivery remained the group’s largest profit generator. Its adjusted revenue stood at Rs 3,537 crore, while adjusted EBITDA reached Rs 606 crore. District continued to report losses as Eternal invested in growing its going-out platform.
As of March 2026, borrowings stood at Rs 4,592 crore against equity and reserves of Rs 30,980 crore. This implies a debt-to-equity ratio of 0.15 times. The borrowings largely represent lease liabilities rather than conventional debt.
RoCE stood at 2.5% and RoE at 0.4%. The stock trades at an EV/EBITDA of 99.3 times, above its five-year average of 94.4 times and the peer median of 15 times. Growth remains strong, but the valuation leaves limited room for execution setbacks.
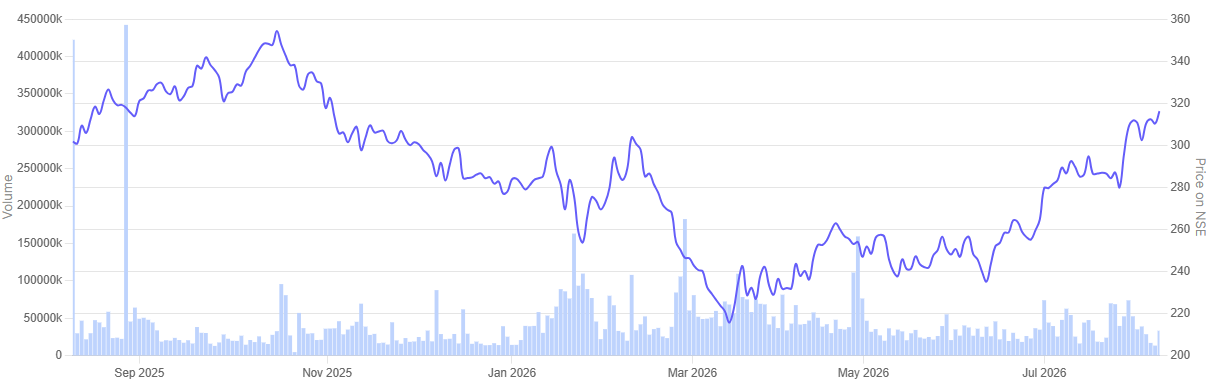
In the past year, the share price of Eternal is up 5.9%.
Eternal 1 Year Share Price Chart
#3 Le Travenues Technology: Growth Moves Beyond Ticketing
Incorporated in 2007, Le Travenues Technology runs online platforms to information and booking services for the travel industry. It also provides software development & maintenance services to its customer.
Le Travenues Technology Financial Performance
| Key metric | Value |
| 7-year sales CAGR | 62.9% |
| Q1 FY27 revenue | Rs 356.8 crore, up 13% |
| Q1 FY27 net profit | Rs 34.2 crore, up 81% |
| Debt-to-equity ratio | 0.02 |
Le Travenues Technology, which operates ixigo, recorded a seven-year sales CAGR of 62.9%. Its growth has moved beyond train and flight bookings, with buses, hotels and travel services becoming larger contributors.
The company reported strong momentum in Q1 FY27. Revenue grew 13% to Rs 356.7 crore, while profit after tax jumped 81% to Rs 34.2 crore. The bus business is now the group’s largest contributor to contribution margin.
Its gross transaction value (GTV) grew 39% in Q1. Flight GTV rose 27% despite high fares and limited airline capacity. Train volumes remained under pressure due to restrictions on Tatkal access and additional authentication requirements.
Beyond Ticketing: Diversifying Revenue in Travel Tech
Hotels are the next growth area. The company has direct partnerships with more than 10,000 hotels across nearly 700 towns. Its acquisition of a 54.66% stake in Revistay adds budget and flexible-stay inventory. It is also building AI-led hotel onboarding and travel-planning tools.
At March 2026, borrowings stood at Rs 44 crore against equity and reserves of Rs 2,047 crore. This implies debt-to-equity of 0.02 times. RoCE stood at 6.8% and RoE at 5.5%.
The stock trades at 60.8 times EV/EBITDA, below its one-year median of 90.3 times but above the peer median of 20 times. Growth remains healthy, though investment in hotels and weak aviation conditions may restrain near-term margins.
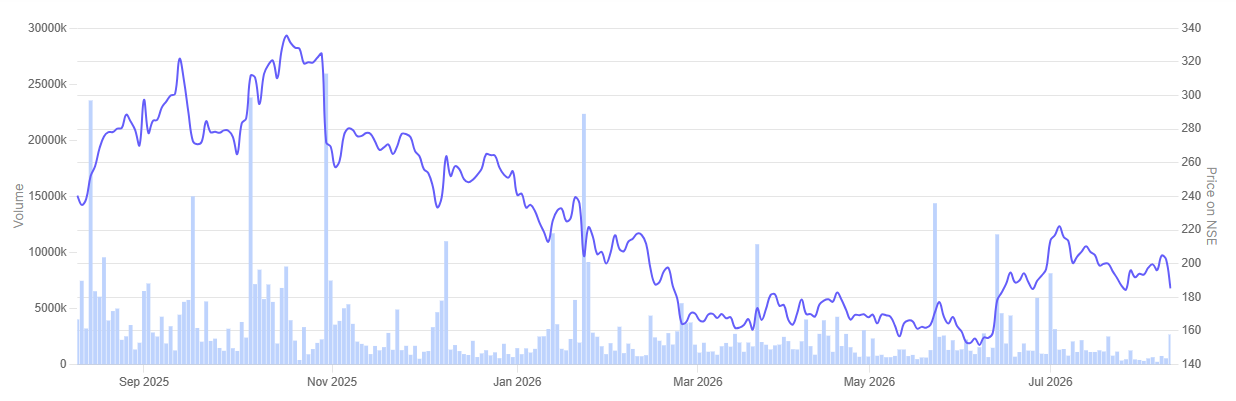
In the past year, the share price of Le Travenues Technology is down 22.6%.
Le Travenues Technology 1 Year Share Price Chart
#4 Dixon Technologies: Manufacturing Scale Meets Low Leverage
Dixon Technologies is an electronic manufacturing services company producing mobile phones, consumer electronics, home appliances, lighting products and security equipment. It has also partnered with boAt’s parent, Imagine Marketing, to manufacture wireless audio products in India.
Dixon Technologies Financial Performance
| Key metric | Value |
| 7-year sales CAGR | 49.1% |
| Q1 FY27 reported revenue | Rs 16,076 crore, up 25% |
| Q1 FY27 adjusted revenue | Rs 15,557 crore, up 21% |
| Q1 FY27 reported profit | Rs 663 crore, up 195% |
| Q1 FY27 adjusted profit | Rs 218 crore, down 3% |
| Debt-to-equity ratio | 0.21 |
Dixon Technologies recorded a seven-year sales CAGR of 49.1%. Mobile manufacturing remains its largest business. Telecom, IT hardware and consumer electronics are adding scale.
Margin Pressures Behind the Headlines
Reported revenue rose 25% YoY to Rs 16,076 crore in Q1 FY27. Reported profit after minority interest increased 195% to Rs 663 crore. However, this included a Rs 519-crore fair-value gain on Dixon’s stake in Aditya Infotech. Excluding this gain and related revenue, adjusted revenue increased 21% to Rs 15,557 crore. Adjusted profit fell 3% to Rs 218 crore. This points to pressure on underlying profitability despite strong sales growth.
Dixon received approval for its Vivo joint venture in July 2026. The venture is expected to start contributing from Q3 FY27. Its one-million-square-foot Noida facility is also scheduled to begin operations during the quarter.
The company plans to raise annual camera-module capacity from 70 million units to 180–190 million over 15–18 months. Machinery installation at its display facility is underway. Trials are expected in Q3 FY27, followed by mass production around the end of Q3 or early Q4. Telecom-equipment and lighting exports are also planned during FY27.
At March 2026, borrowings stood at Rs 994 crore against equity and reserves of Rs 4,677 crore. This gives a debt-to-equity ratio of 0.21. Dixon trades at 27.9 times EV/EBITDA, below its five-year average of 58.3 times but above the peer median of 15.4 times. Capacity additions support growth visibility, but margin recovery remains crucial.
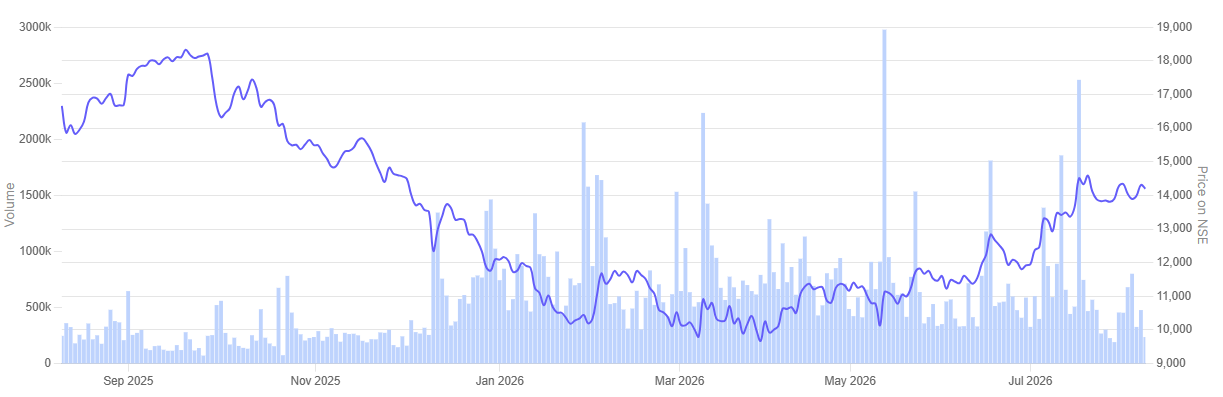
In the past year, the share price of Dixon Technologies is down 14.7%.
Dixon Technologies 1 Year Share Price Chart
#5 PB Fintech: Insurance Growth Builds on a Low-Debt Base
PB Fintech, popularly known as Policybazar, is India’s largest online platform for insurance and lending products through its flagship brands – Policybazaar and Paisabazaar platform through which it provides convenient access to insurance, credit and other financial products.
PB Fintech Financial Performance
| Key metric | Value |
| 7-year sales CAGR | 45.5% |
| Q1 FY27 revenue | Rs 1,888 crore, up 40% |
| Q1 FY27 net profit | Rs 163 crore, up 92% |
| Debt-to-equity ratio | 0.05 |
PB Fintech has recorded a seven-year sales CAGR of 45.5%, supported by the expansion of Policybazaar and Paisabazaar. Revenue rose 36.5% year-on-year to Rs 6,794 crore in FY26. Net profit increased nearly 90% to Rs 670 crore as operating margins improved.
Growth remained strong in Q1 FY27. Revenue increased 40% to Rs 1,888 crore, while profit after tax rose 92% to Rs 163 crore. Total insurance premium grew 41% to Rs 8,372 crore. New health and term insurance expanded 53%, reflecting the focus on underpenetrated protection products.
Recurring Revenue and Distribution Expansion
Renewal and trail revenue grew 55% to Rs 1,003 crore on a trailing 12-month basis. This provides a more recurring income stream as policies sold earlier come up for renewal. The credit business also recovered, with disbursements rising 33% to Rs 4,366 crore.
PB Partners is widening physical distribution. It has more than five lakh advisers and covers over 19,000 PIN codes. Around 78% of its premium comes from Tier-II and Tier-III cities. Internationally, UAE insurance premium grew 31%. The company has also received approval to begin billing at its second healthcare facility.
At March 2026, borrowings stood at Rs 360 crore against equity and reserves of Rs 7,312 crore. This implies debt-to-equity of 0.05 times. The entire borrowing comprised lease liabilities. RoCE stood at 10.3% and RoE at 9.7%.
The stock trades at 75.7 times EV/EBITDA, below its three-year median of 156.5 times but well above the peer median of 16.8 times. Sustaining premium growth while improving returns remains the key test.
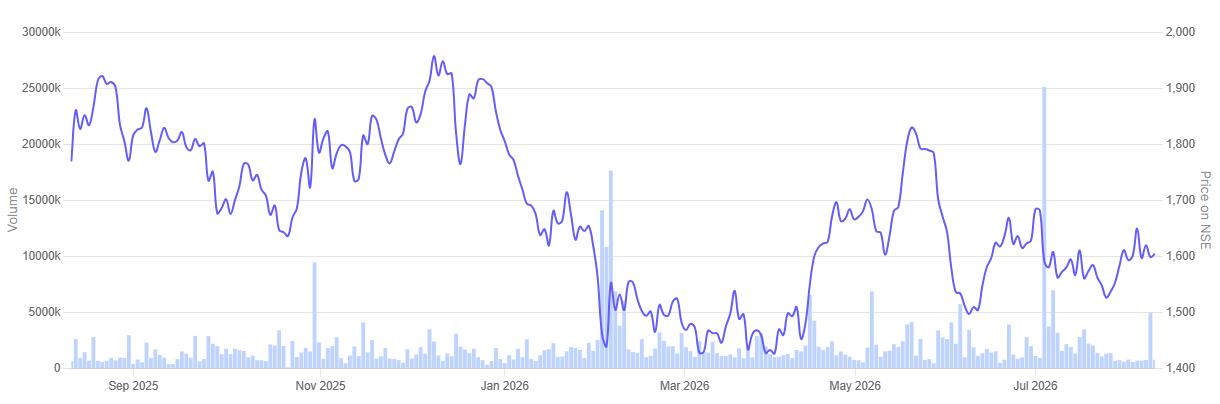
In the past year, the share price of PB Fintech is down 14.7%.
PB Fintech 1 Year Share Price Chart
Conclusion
These five companies show that rapid growth need not always come with a highly leveraged balance sheet. Each has delivered a seven-year sales CAGR of more than 20%, while keeping its debt-to-equity ratio below 0.25. Their growth drivers, however, differ widely—from renewable-energy projects and electronics manufacturing to food delivery, insurance distribution and online travel.
Low debt reduces financial risk, but it does not make every stock inexpensive or every growth trajectory durable. Several names trade well above their peer valuations, while some still generate modest returns on capital. Investors should therefore weigh execution, profitability and cash generation alongside headline growth. The screen offers a useful starting point, not a substitute for deeper research.
India’s Fastest-Growing Companies with Low Debt
| Metric | Waaree Ren. | Eternal | Le Travenues | Dixon Tech | PB Fintech |
| 7-year sales CAGR | 152.9% | 70.2% | 62.9% | 49.1% | 45.5% |
| 1QFY27 Revenue growth | 53.2% | 182% | 13% | 25%* | 40% |
| 1QFY27 Net profit growth | 37.7% | 268% | 81% | 195%* | 92% |
| Debt-to-equity ratio | 0.12 | 0.15 | 0.02 | 0.21 | 0.05 |
You can track how these are progressing by adding stocks to your watchlist.
Disclaimer:
Note: We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Ekta Sonecha Desai has a passion for writing and a deep interest in the equity markets. Combined with an analytical approach, she likes to deep dive into the world of companies, studying their performance, and uncovering insights that bring value to her readers.
Disclosure: The writer and her dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.