



India’s ethanol story is entering its next phase.
With the E20 milestone largely achieved, the government’s focus has shifted towards higher blending levels, extending the industry’s long-term growth runway. It has already introduced BIS standards for E22, E25, E27, E30, and E85 and has mandated the sale of petrol with up to 20% ethanol and a minimum RON 95 specification from 1 April 2026.
The opportunity is significant. Every 1% increase in the national blending mandate requires an additional 55-56 crore liters of ethanol. This could drive sustained demand for production capacity, technology, and downstream infrastructure.
Against this backdrop, we have selected three companies that collectively represent the key segments of India’s evolving ethanol value chain.
These companies derive a meaningful share of their business from ethanol and related biofuel technologies, making them more representative of India’s evolving bioeconomy than diversified sugar companies, where ethanol remains a secondary earnings driver.
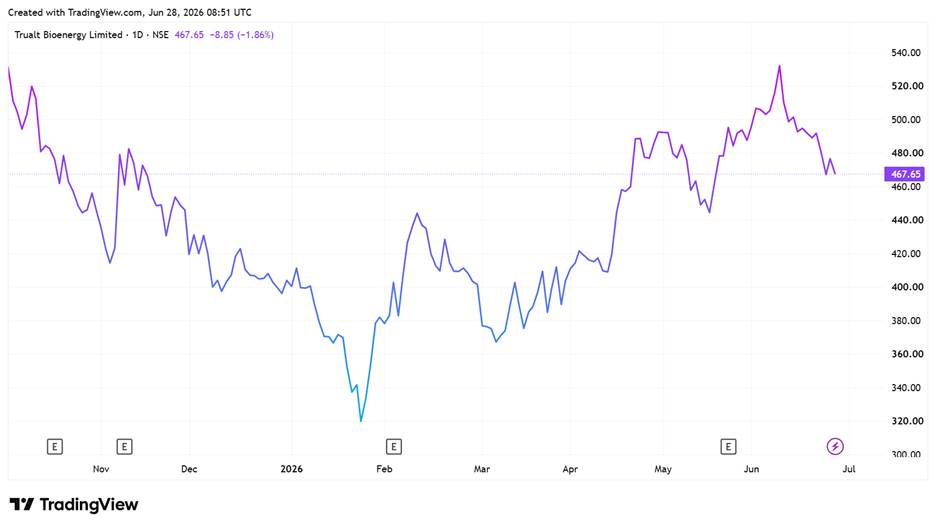
#1 TruAlt Bioenergy: India’s Largest Ethanol Production Company
TruAlt Bioenergy operates the largest ethanol production platform in India, boasting an installed capacity of 2,000 KLPD (Kilo Litres Per Day). Over the past financial year, it has strategically transformed its operations from a mono-feed business into a multi-feed bioenergy platform.
Capital Expenditures: Mitigating Crop Seasonality via Dual-Feed Integration
The company has invested over ₹400 crore to transition 1,300 KLPD of its capacity across three units into a dual-feed system. This allows the plants to operate on sugarcane syrup during the crushing season (about 100 days) and then shift to grains such as maize and broken rice for the remaining 200-230 days.
This will essentially transform the company from a seasonal producer to a nearly year-round manufacturer. This multi-feed integration not only ensures continuous production but also generates high-value co-products. It is pursuing a multi-pronged expansion strategy to drive differentiated expansion from an integrated, future-ready bioenergy platform.
The company’s expansion spans 4 key verticals: Compressed Biogas (CBG), Sustainable Aviation Fuel (SAF), its Retail Fuel Network, and Ethanol infrastructure. It is poised to become one of India’s leading CBG producers, with plans to scale its gross production capacity from the current 10 Tons Per Day (TPD) to 162.2 TPD over the next nine months.
Strategic Alliances: Scaling Compressed Biogas Capacity via Sumitomo and GAIL JVs
This growth is being driven by strategic joint ventures (JVs). The first is a JV with Sumitomo Corporation. This JV is currently building three 20 TPD plants in Mudhol, Kerakalmatti, and Badami. The under-construction plants are targeted to be operational by Q3 and Q4 of the FY27, increasing their capacity to 60 TPD.
Following GAIL’s equity infusion, TruAlt has identified land for six more CBG plants in Karnataka and Maharashtra. Construction is scheduled to begin in July 2026. These six plants will add 72 TPD and are targeted to be operational by Q4 of FY27. The expansion, with a capex of ₹340 crore, is being funded through a 70:30 debt-to-equity mix with financing from NABARD.
High-Value Diversification: The ₹2,250-Crore Sustainable Aviation Fuel Bet
To capitalize on global aviation decarbonization mandates, TruAlt is setting up a 310 KLPD Ethanol-to-Jet SAF facility. The company has signed an MoU with the Government of Andhra Pradesh and identified a site in Srikakulam. The location is strategic, as it is close to HPCL Visakh Refinery, IOCL Paradip Refinery, and an International Airport.
This provides significant logistical advantages for exports and domestic blending. The project commands an estimated investment of ₹2,250 crore. TruAlt has signed a technology licensing agreement with Honeywell UOP and is in the Front-End Engineering Design (FEED) stage.
Once financial closure and long-term offtake agreements are secured, the plant is expected to be commissioned by FY29. Once operational, this facility will consume approximately 20 crore litres of TruAlt’s own ethanol production (roughly 30% of its capacity), ensuring full utilization of its core ethanol business capacity regardless of fluctuations in domestic OMC tenders.
Downstream Retail Network Expansion and FY26 Financial Constraints
To improve profit margins through direct customer access and independent ethanol blending, TruAlt is expanding its downstream presence. It currently operates 7 retail outlets (₹103.5 crore in revenue) and has 4 more under construction, bringing the total to 11 outlets shortly.
As part of a larger 100-outlet (Phase 1) rollout, TruAlt has shortlisted 76 more locations in the high-potential logistics corridor. The company aims to reach 87 outlets soon, and construction will be accelerated depending on the stability of global crude oil prices.
Evaluating the Financial Impacts of Volatile Raw Feeds
TruAlt’s financial position was slightly affected by disruptions in the ethanol segment. Total income declined 7.8% year-over-year to ₹1,968.5 crore in FY26. Lower-than-expected ethanol tender allocations led to the revenue decline. EBITDA fell slightly by 1.8% to ₹363.4 crore with margins at 18.5%. Net profit dropped by 33.9% to ₹96.9 crore.
#2 Godavari Biorefineries
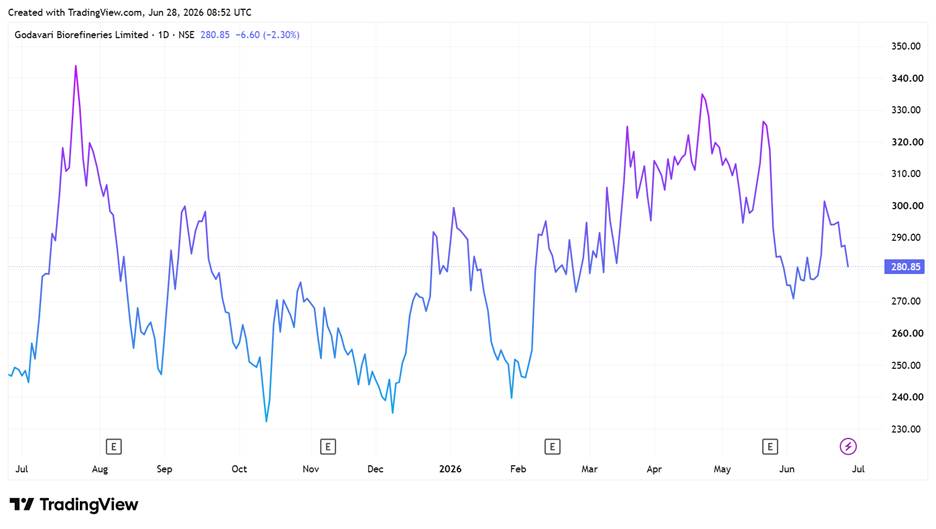
Godavari Biorefineries (GBL) is an integrated biorefinery company. In FY26, the company successfully sold 98 million liters of ethanol equivalent.
Structural Breakdown: Product Mix and FY26 Ethanol Segment Dynamics
It maintains a diverse product mix: 81% of the ethanol was supplied to the government’s Ethanol Blending Program (EBP), 13% was sold as Extra Neutral Alcohol (ENA), and 6% was sold as other grades
The ethanol segment delivered strong growth despite pricing pressures. Ethanol segment revenue rose 12.6% year-over-year to ₹658.6 crore in FY26. EBITDA grew 19.3% year-over-year to ₹97.4 crore, with margins at 14.8%. Improved feedstock availability supported the growth.
Feedstock Resilience: De-risking via the 200-KLPD Multi-Feed Conversion
To protect itself from climate, policy, and feedstock constraints, GBL is rapidly adopting a multi-feedstock strategy. The company is commissioning a new 200 KLPD grain/maize-based distillery by June 2026. This new facility will increase annual ethanol capacity by approximately 60 million liters.
Once operational, GBL will be able to pivot between sugarcane and grain/maize based on crop availability and pricing, fundamentally insulating the company from single-crop dependencies. While the volumes are strong, the industry faces regulatory pricing constraints. Ethanol prices in India are fixed by the government based on the feedstock utilized.
How Regulatory Pricing Formulas Cap Immediate Upsides
GBL currently nets about ₹60+ per liter for ethanol made from B-heavy molasses, ₹65+ per liter for juice-based ethanol, and ₹72 per liter for maize-based ethanol. In the recent crushing season, it faced margin pressure as the government increased sugarcane procurement prices.
Downstream Chemicals and Next-Gen Carbon-to-DME Technologies
In addition to selling ethanol as fuel, GBL uses ethanol as the main raw material to manufacture its high-margin bio-based specialty chemicals. Further, GBL is investing heavily in future-ready clean energy technologies.
GBL is collaborating with the Institute of Chemical Technology to pilot the conversion of carbon dioxide and hydrogen into Dimethyl Ether. The company is currently running this pilot plant. The research phase is expected to take another 3-6 months before assessing commercial scalability.
Godavari’s financial growth was muted. Total income grew 6.0% year-over-year to ₹2,000.2 crore in FY26. EBITDA grew 15.8% to ₹139.3 crore, with margins at 7.0%. Net profit rebounded to a positive ₹3.5 crore, recovering from a net loss in the previous financial year.
Godavari Biorefineries Share Price
#3 Praj Industries: This Ethanol Technology Pioneer with 10% Global Share
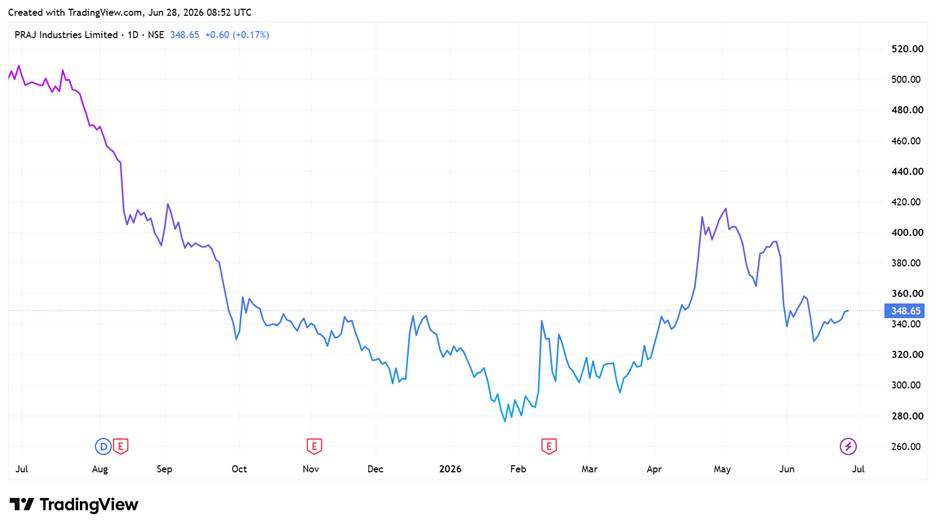
Praj Industries is a pioneer in ethanol technology, holding about 10% of the global ethanol production market. Praj operates across three primary segments: Bioenergy (67% of revenue), Engineering (22%), and HiPurity Solutions (11%).
Praj provides multi-feed and multi-product solutions for first-generation ethanol that convert agricultural feedstocks such as sugarcane juice, molasses, and starchy grains into bioethanol.
Structural Matrix: Segment Performance and 1G Market Realities
Currently, the domestic first-generation ethanol market is experiencing a slowdown. To adapt to this market shift, Praj has focused on Brownfield solutions to improve operational efficiency and co-product valorization at existing plants. The company is also seeing increased demand for greenfield ENA plants, a sector in which it maintains a clear technological advantage.
Internationally, Praj is capitalizing on global expansion opportunities. It has successfully commissioned its first grain-to-ethanol plant in Brazil. The company is also actively engaging with markets in Southeast Asia, Africa, and Latin America that have recently announced increases in the share of biofuels in their respective energy mixes.
Technological Leadership: Capturing All Active Domestic 2G Bioethanol Formations
Praj is highly active in the 2nd Generation space that uses agricultural residues such as rice and wheat straw, corn stover, bagasse, and empty fruit bunches to produce lignocellulosic ethanol. The company’s technology is critical to the domestic market, as Praj is executing all three 2G bioethanol projects currently underway in India.
Praj anticipates that any blending increases beyond 5% will necessitate entirely new capacity additions, benefiting a company like Praj. The company is also expecting a commercial order for Bio-Isobutanol in Q1FY27, a breakthrough molecule that can be directly blended with diesel.
Future Catalysts: Policy Tailwinds in Sustainable Aviation Fuel (SAF) and CBG
Further, a draft policy for SAF mandates blending by 2027. Praj anticipates that even a minimal 1% SAF blending requirement will create an additional demand for 28 crore liters of ethanol. Praj expects its 2G-produced ethanol to play a significant role in SAF production. The company is currently concluding basic engineering assignments for international ethanol-to-SAF plants
The Indian government also aims to aggressively scale up Compressed Bio-Gas blending to 5% by FY29 from 1% in FY26. Maharashtra recently approved its State CBG Policy 2026, backed by a ₹500 crore project outlay.
To this end, Praj has demonstrated its CBG capabilities on a commercial scale. Work is currently underway to expand the capacity of several plants using a mixed feedstock of Napier grass and rice straw. While the company has a strong pipeline of inquiries for new projects, management has recently experienced some delays in finalizing orders.
Strategic Alliance Pipelines and FY26 Operational Headwinds
Praj has also entered into strategic partnerships with leading Oil Marketing Companies. This includes an MoU with IOCL to establish CBG, ethanol, and SAF production facilities, as well as an MoU with BPCL for a JV focused specifically on CBG. Praj is now actively exploring international opportunities to export its CBG technologies to global markets.
Praj’s financial position was significantly affected by extended project execution cycles, escalated site costs, and a slowdown in greenfield ethanol projects. Total income declined 1.9% year-over-year to ₹3,167.9 crore in FY26. EBITDA fell significantly by 51.7% to ₹151.8 crore with margins at 4.79%. Net profit dropped by 89.1% to ₹23.8 crore.
Let’s take a quick look at a financial snapshot before we look into the valuations
| Parameter | TruAlt | Godavari | Praj Industries |
| Positioning | Ethanol producer | Integrated biorefinery | Technology provider |
| FY26 Revenue (₹ crore) | 1,968.5 | 2000.2 | 3,167.9 |
| Net Profit (₹ crore) | 96.9 | 3.5 | 23.8 |
| EBITDA (₹ crore) | 363.4 | 139.3 | 151.8 |
| Growth Trigger | Capacity expansion | Multi-feed and chemicals | 2G ethanol, SAF & CBG |
While TruAlt generated less revenue than its peers, its net profit was roughly 4x that of Praj and significantly higher than Godavari’s, and its EBITDA outperformed both.
Valuation Matrix: Comparative Multiples and Structural Return Ratios
TruAlt has a relatively higher Return on Capital Employed (ROCE) and Return on Equity (ROE). Godavari and Praj’s return ratios have been muted recently due to weak profitability.
From a valuation standpoint, historical trading multiples for TruAlt and Godavari are unavail
able due to their recent listings. Currently, TruAlt trades at a premium to the industry median multiple, while Godavari trades at a slight discount. Meanwhile, Praj continues to command a premium over both the industry median and its three-year historical median.
| Peer Comparison (X) | |||||
| Company | EV/EBITDA Multiple | Return Ratios | |||
| Company | 3Y Median | Industry | ROCE (%) | ROE (%) | |
| TruAlt | 14.8 | NA | 11.1 | 10.4 | 8.4 |
| Godavari | 13.9 | NA | 14.9 | 6.6 | 4.3 |
| Praj | 31.6 | 24.1 | 18.1 | 6.3 | 1.4 |
The three companies are positioned to benefit from India’s long-term ethanol opportunity, but through different growth levers. TruAlt is focused on scaling production and downstream integration, Godavari is leveraging ethanol to build a diversified bio-based chemicals business, while Praj is positioned as a technology enabler across ethanol, SAF, and CBG.
Although near-term earnings remain under pressure across the sector, their long-term prospects will depend on execution and the pace of policy-led capacity additions. Nonetheless, these names could be kept in your watchlist to track their execution.
Disclaimer
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation. Only in cases where the data was unavailable have we used an alternative, widely used, and accepted source of information.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
About the Author: Madhvendra has been deeply immersed in the equity markets for over seven years, combining his passion for investing with his expertise in financial writing. With a knack for simplifying complex concepts, he enjoys sharing his honest perspectives on startups, listed Indian companies, and macroeconomic trends.
A dedicated reader and storyteller, Madhvendra thrives on uncovering insights that inspire his audience to deepen their understanding of the financial world.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources, and only after consulting such independent advisors as may be necessary.