



Greater urbanization and higher disposable income inevitably lead to a bigger expenditure on health services. At the same time, we are seeing rapid aging of society with a decline in fertility rate and a higher life expectancy. Two healthcare stocks which remain resilient in the healthcare sector, and set to capitalize on this trend, are Apollo Hospitals Enterprise Limited and Max Healthcare Institute Limited.
Here is a list of factors that can deliver strong tailwinds for both these healthcare stocks.
#1 The 15,000-Bed Pipeline: Betting on India’s Structural Supply Gap
Both Apollo and Max are aggressively expanding their bed capacity, which provides a strong tailwind for future revenue growth. Apollo has announced increasing its bed count by 3,475 in the expansion phase till FY30. The current active bed capacity is close to 9,620 as of the end of FY26. This shows that the management is betting on increased demand and is also looking for geographical diversification. Sunita Reddy, Managing Director of Apollo Hospitals, has noted that India is short of 100,000 beds and Apollo will try to fill this gap by aggressive expansion.
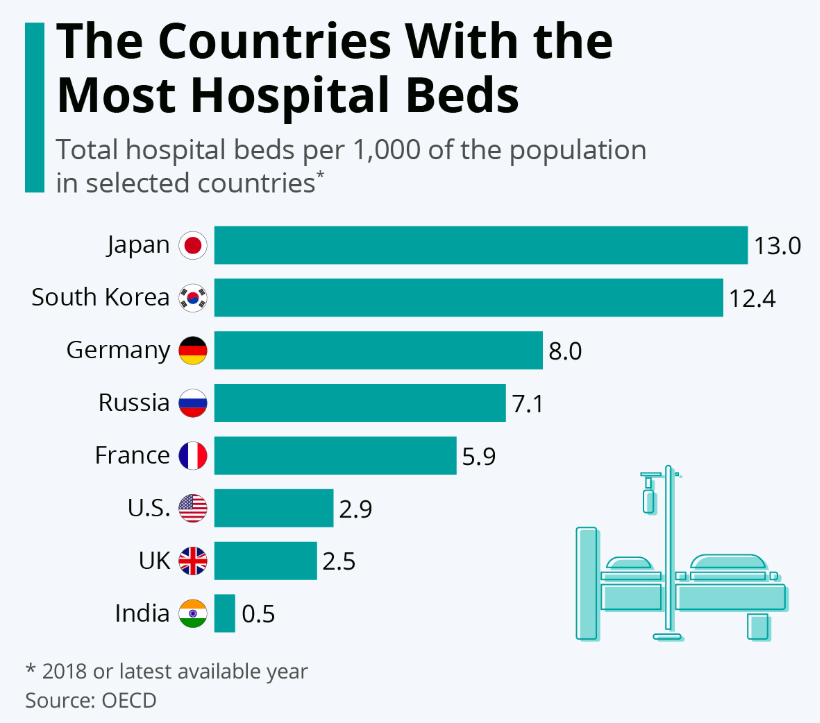
An earlier report by the Organisation of Economic Co-operation and Development, or OECD, mentioned that India has 0.5 beds per 1,000 people compared to 2.5 in UK, 2.9 in U.S., and 13 in Japan. The demand for more beds will increase in India, which should allow Apollo to deliver a more robust bed capacity expansion pipeline.
Join now
Similarly, Max Healthcare is also planning to increase its bed capacity to 10,000 by FY30 from the current bed count of close to 6,100. Max Healthcare has the bulk of its bed capacity in Tier-1 cities, which allows it to deliver higher revenue per patient and a better occupancy rate.
#2 Targeting High-Acuity Care: The Metric Driving 62% of Inpatient Revenue
Both Apollo and Max are expanding their high-acuity treatments like oncology, neurology, cardiology, etc. These treatments now make up 62% of the inpatient revenue base for Apollo. It also helps Apollo and Max to deliver a better runway for increasing the revenue per patient metric.
Life expectancy in India has been increasing steadily. We can already see the impact in states like Kerala, where an RBI report mentioned that 18.7% of the population is over 60 years. This would increase to 22.8% by 2036. We should see a similar trend in other states due to the aging of the population. An older population requires greater medical care, and a higher chunk of the disposable income is spent on healthcare.
#3 Medical Tourism & Premiumization: Defending a Premium Valuation
We are seeing the premiumization trend in many different sectors, including FMCG, quick commerce, retail, and others. Consumers are willing to pay a higher price for branded products and for greater convenience. We could see a similar trend in healthcare, where premium healthcare services gain greater traction as disposable income increases.
Within the premiumization trend, we are also seeing strong growth in medical tourism revenue for both these companies. Max Healthcare reported International patient revenue at Rs 247 cr, an 18% YoY growth. International patients now make up 9% of the total hospital revenue for the company. Apollo’s international patient revenue also makes up 8% of the total revenue. We can see from the chart below the huge disparity in key treatments which gives Apollo and Max strong growth potential for international medical tourism.
Value proposition of India vs other countries in medical treatments
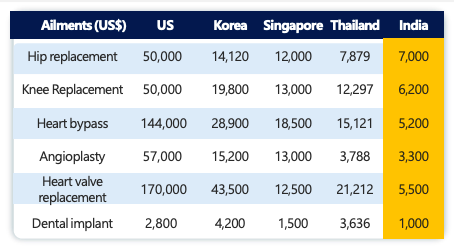
Higher bed capacity and greater geographical diversification should allow Apollo and Max to grab a bigger chunk of the premium market base.
Now let’s dig deeper into the individual performance of Apollo Hospitals and Max Healthcare.
#1 Apollo’s 38% PAT Surge: How Margins Outpaced Revenue Growth
Apollo Hospitals reported total income of Rs 7,092 cr in the recent quarter compared to Rs 5,882 cr in the year-ago quarter. This is a 20.57% YoY growth which is a good trajectory. The profit before tax increased to Rs 798 cr in the recent quarter from Rs 582 cr in the year-ago quarter.
The PAT came in at Rs 610 cr compared to Rs 441cr in the year-ago quarter. The YoY growth in PAT was 38.32% which was significantly higher than the revenue growth. This shows an expansion of margin as the company expands into more premium services and higher acuity treatments.
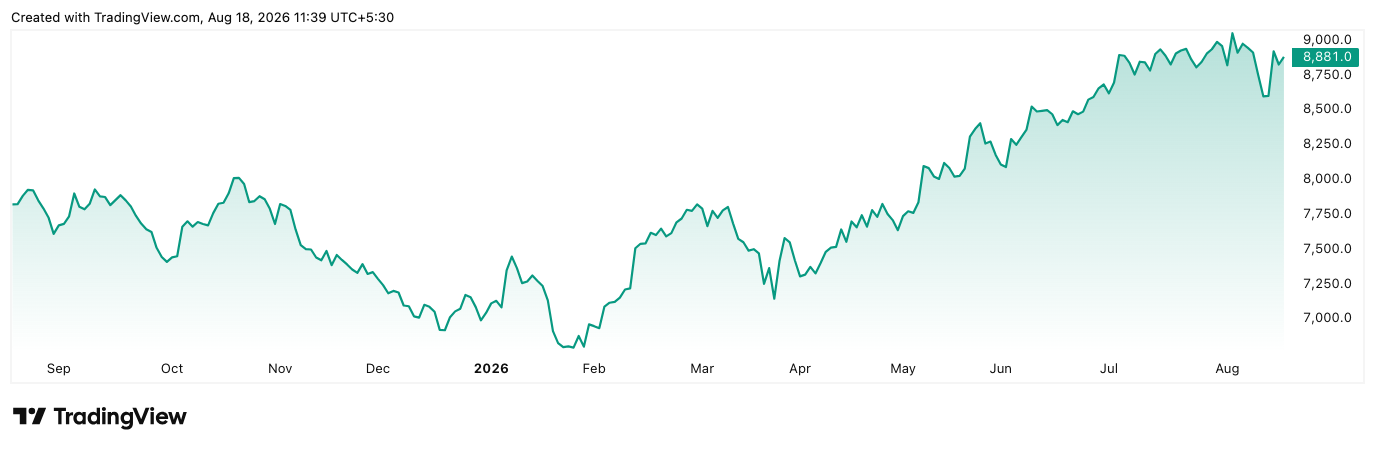
Over the last 1 year, Apollo Hospitals stock has risen by 13% and over the last 5 years it has shown 88% jump. This bullish momentum is supported by strong revenue and PAT growth.
1-year Price chart of Apollo Hospitals
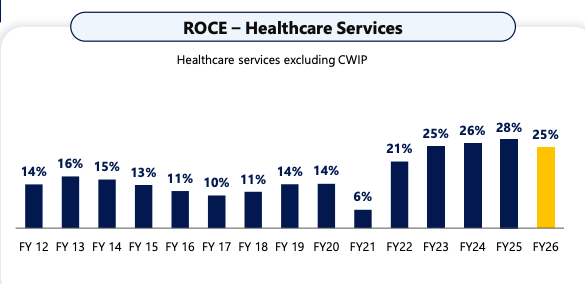
Apollo Hospitals has also shown a big jump in its ROCE for the Healthcare Services segment over the last few years. Prior to the pandemic, Apollo’s Healthcare Services ROCE was in the range of 10%-15%. However, over the last few years, this metric has increased to a steady 25%-28% range.
#2 Max’s Margin Pressures: Unpacking the 18.5% Jump in Total Expenses
Max Healthcare reported total income of Rs 2,406 cr in the recent quarter compared to Rs 2,064 cr in the year-ago quarter. This is a 16.57% YoY growth in total income. The profit before tax was Rs 436 cr in the recent quarter compared to Rs 400 cr in the year-ago quarter, which is a 9% YoY growth. The profit after tax increased to Rs 323 cr from Rs 308 cr in the year-ago period, showing a 4.8% YoY growth. A higher deferred tax charge of Rs 30.8 cr negatively impacted the PAT in this quarter.
1-year price chart of Max Healthcare
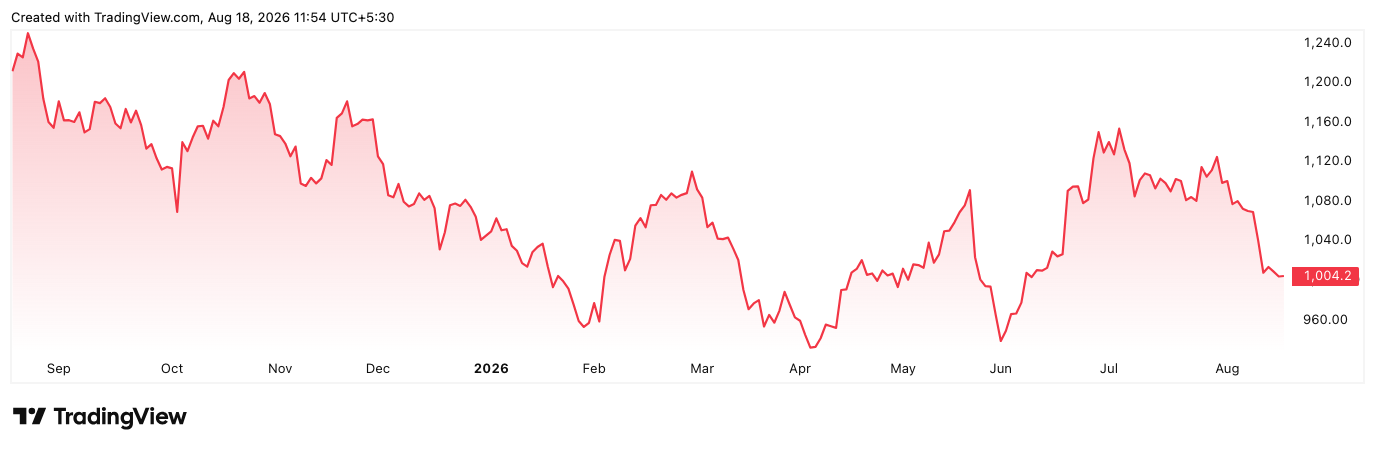
Max Healthcare’s stock has declined by 17.5% in the last 1 year. Over the last 5 years, it has risen by 193%.
The Head-to-Head: Integrated Ecosystems vs. Metro Market Dominance
| Particulars | Apollo Hospitals | Max Healthcare |
| Q1 FY27 revenue | Rs 7,092 crore | Rs 2,406 cr |
| YoY growth | 20.57% | 16.57% |
| PAT | Rs 610 cr | Rs 323 cr |
| PAT margin | 8.6% | 13.42% |
| Strengths | Integrated multi-channel ecosystem | Industry-leading average revenue per occupied bed driven by premium metro markets |
Valuation Check: Are These Growth Tailwinds Already Priced In?
Both Apollo Hospitals and Max Healthcare have a higher-than-industry median P/E ratio. Apollo’s PE ratio is at 60 while Max is close to 65. On the other hand, the industry median P/E ratio is 45.28. Apollo’s consolidated EBITDA was Rs 1,092 cr in recent quarter while Max’s EBITDA reported network operating EBITDA of Rs 704 cr. Despite a higher valuation, both these stocks are showing good growth potential.
Apollo Hospitals is trading at an EV-to-EBITDA ratio of 31.63 compared to 40.39 for Max Healthcare and the industry median of 23.23. The Return on Capital Employed (ROCE) metric of Apollo Hospital is better than Max Healthcare’s at 17.45. Similarly, the Return on Equity (ROE) of 21.15% for Apollo Hospitals is significantly better than 14.74% reported by Max Healthcare. The industry median ROE is 13.06%.
| Peer comparison | ||||
| Company | P/E ratio | EV/EBITDA | Return ratios (%) | |
| ROCE (%) | ROE (%) | |||
| Apollo Hospitals | 60.10 | 31.63 | 17.45 | 21.15 |
| Max Healthcare | 65.14 | 40.39 | 14.71 | 14.74 |
| Industry Median | 45.28 | 23.23 | 14.71 | 13.06 |
While both Apollo Hospitals and Max Healthcare are trading at a premium valuation compared to the industry median, we can see strong tailwinds due to capacity expansion and more premium services.
Whether the stocks deliver from here on, only time will tell. It may be a good idea to add Apollo Hospitals and Max Healthcare to the watchlist.
Disclaimer:
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation. Only in cases where the data was unavailable have we used an alternative, widely used, and accepted source of information
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
About the Author: Rohit is a seasoned financial writer with over a decade of experience covering Indian and international stocks. He specializes in converting complex financial data into actionable insights that can help readers make better calls. He covers macroeconomic trends globally, which gives a better analysis of the growth runway for companies in key sectors.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities, or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources, and only after consulting such independent advisors as may be necessary.