



Welcome to the latest edition of Hidden Gems Weekly. In recent weeks, we examined a company that wants to move beyond meter boxes to supplying the electrical backbone behind India’s power expansion, a hidden small-cap quietly moving into AI’s least understood opportunity, a high-value engineering solutions provider, a company that wants to move beyond selling more machine tools to selling better ones and a company quietly conquering India’s industrial supply chain. This week, we turn to a company that wants to move beyond meter boxes to supplying the electrical backbone behind India’s power expansion.
Every technology boom has a boring infrastructure layer sitting underneath it. The internet needed fibre-optic networks, smartphones needed telecom towers and artificial intelligence is discovering that it needs something even more basic: enormous quantities of reliable power.
That creates an interesting opportunity for companies that understand electricity better than they understand technology. A classic example is Siemens, having benefitted from the growing overlap between power, industrial infrastructure and digital technology as India’s infrastructure needs have expanded.
The comparison is not about size or business mix. It is about the underlying idea: a company with decades of power expertise can potentially use that moat when a new technology cycle creates a huge demand for electricity and related infrastructure.
Join now
One such company is Techno Electric & Engineering Company.
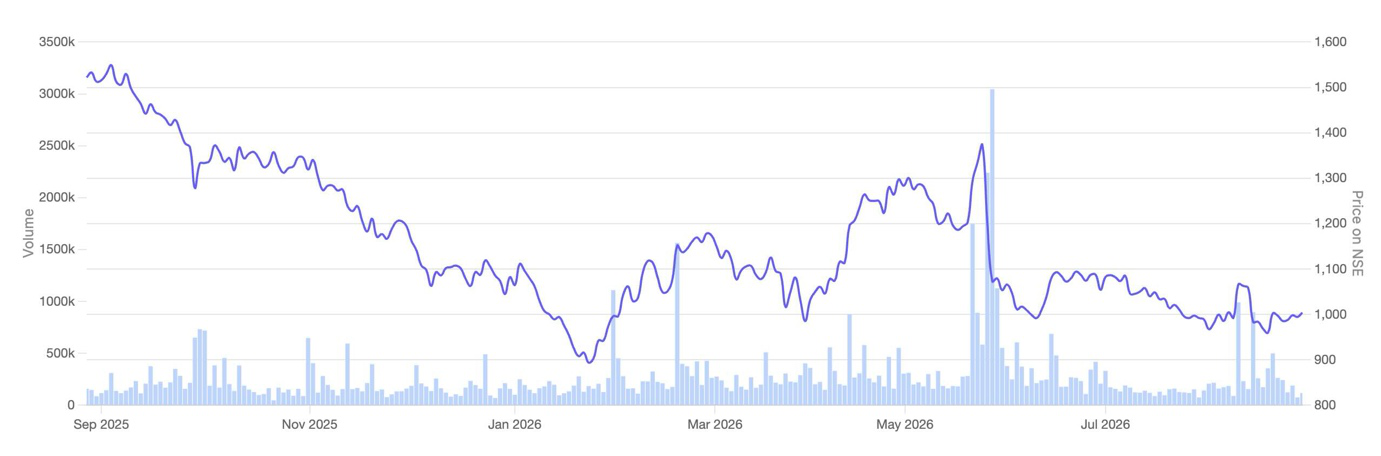
Techno Electric & Engineering Company Ltd 1-Year Share Price Chart
The old business is quietly financing a new one
Techno Electric has spent more than four decades building power infrastructure, particularly transmission systems and high-voltage substations. Around 350 of roughly 500 substations of 400 kilovolts and above built in India over the past three decades carry its work. It has completed more than 450 projects and has more than 650 engineering and commercial professionals.
That kind of history is important because a new entrant into data centres cannot easily manufacture this expertise. The company argues that a data centre is fundamentally a power asset and therefore its knowledge of electricity gives it an advantage in building digital infrastructure.
The opportunity is arriving at the right time. India is expanding its transmission network while data-centre developers are looking for reliable power and faster capacity.
India needs more transmission
The company estimates India could invest around Rs 9 lakh crore in transmission infrastructure between FY26 and FY32 as renewable generation expands and more power needs to be evacuated. Peak power demand reached 271 gigawatts in May 2026 and could move towards 480 gigawatts by FY32.
The grid is also becoming more complicated. As renewable power takes a larger share of generation, the system needs more sophisticated equipment to manage voltage, stability and long-distance power flows. New tenders are already emerging for technologies such as synchronous condensers, dynamic reactive compensation and high-voltage direct current corridors.
This gives Techno Electric a useful starting point. It is trying to enter a new business using capabilities it already possesses.
The order book is doing the talking
The Q1 FY27 numbers were strong. Standalone revenue rose 25% year on year to Rs 641 crore, EBITDA rose 13% to Rs 89 crore, but the EBITDA margin slipped to 13.8% from 15.4% a year earlier.
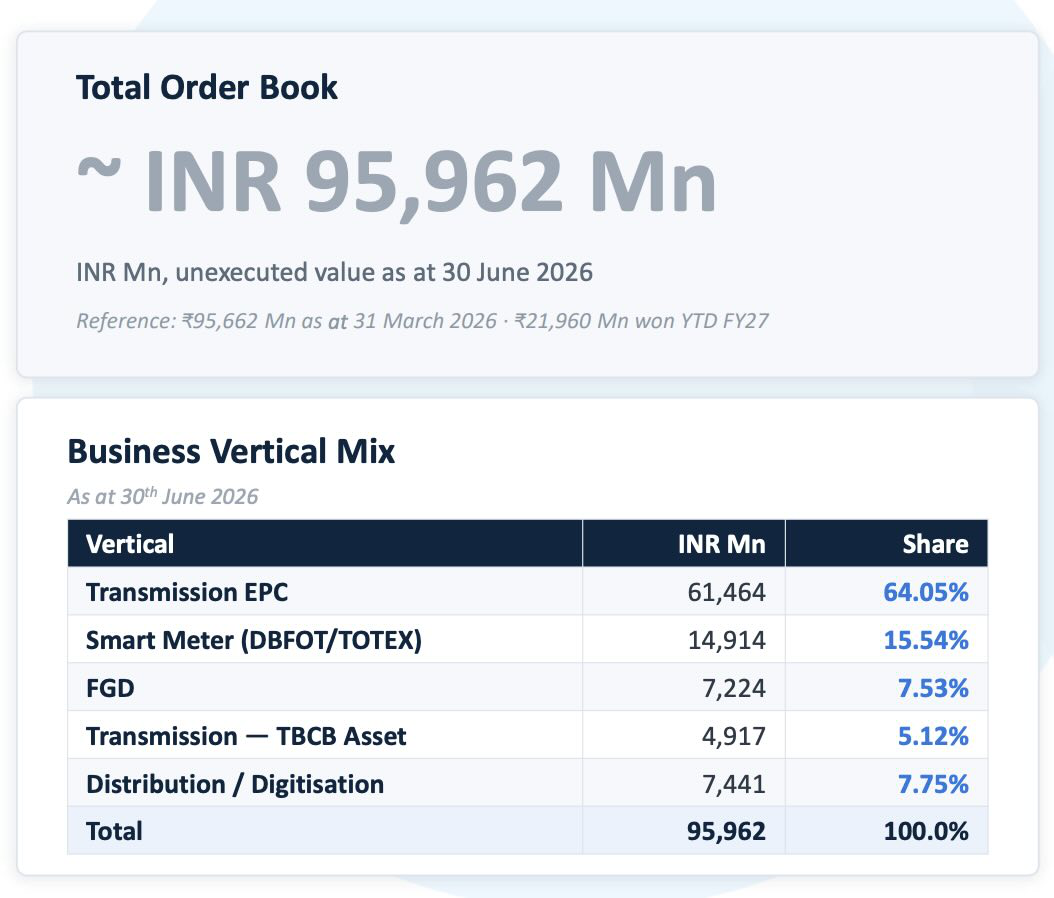
The order book is more interesting when you look at what has happened around it. At Rs 9,596 crore on 30 June, it was almost flat from Rs 9,566 crore at the end of March, up just 0.3% QoQ and about 8% below the year-earlier level. But orders won after the quarter have pushed the backlog to around Rs 11,000 crore, while another Rs 2,100 crore of bids is sitting at L1.
That is separate from the company’s FY27 order-inflow target of Rs 4,000 crore. In other words, Techno Electric already has around Rs 11,000 crore of work waiting to be delivered and wants to add another Rs 4,000 crore of new business during FY27, which would replenish the backlog as projects are completed.
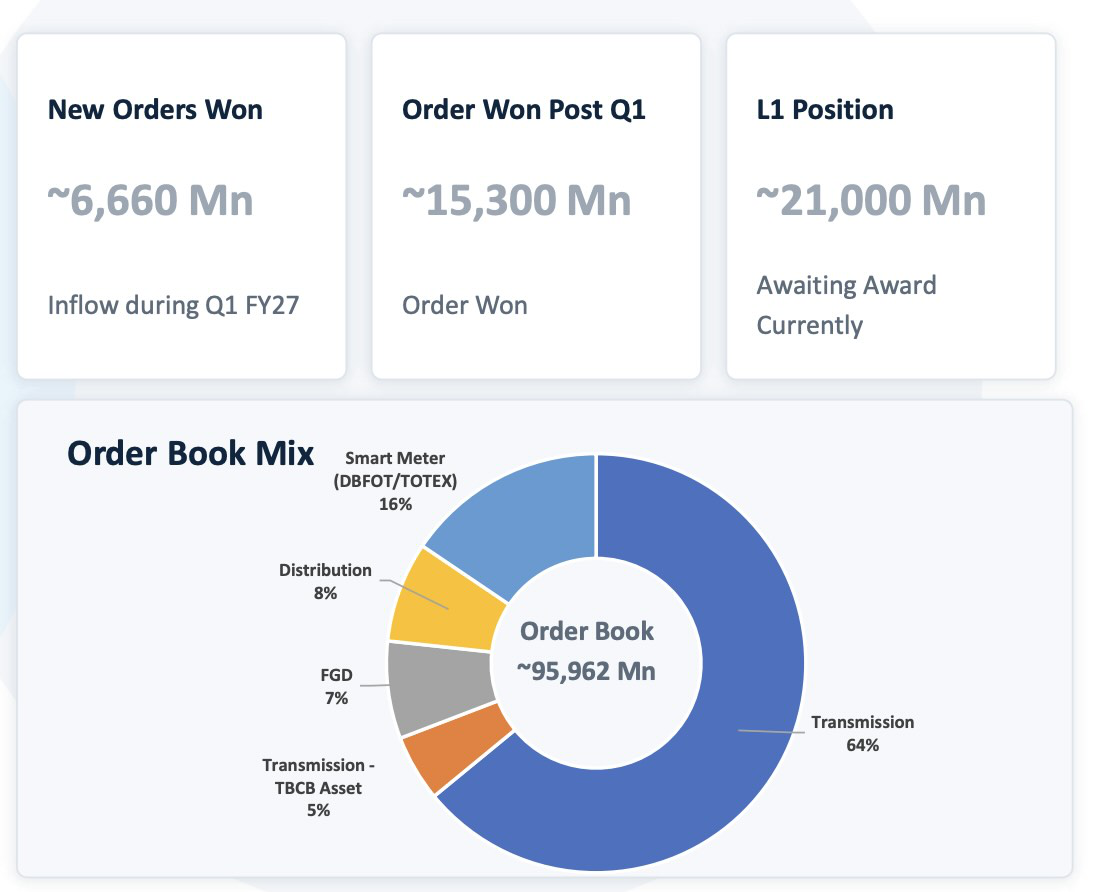
That gives the company revenue visibility for the next few years. But an order book is not revenue and revenue is not cash.
Margins are holding
Techno Electric is not currently a margin-expansion story. Transformer, CRGO steel and other long-lead equipment costs remain elevated as manufacturers’ order books have expanded sharply since FY22. Advance ordering, vendor relationships and cost controls have helped keep profitability within the company’s guided range.
For FY27, the company remains comfortable with revenue of Rs 4,000 crore or more and an EBITDA margin of around 13% to 14%.
Then came Chennai
The interesting part of the story is now Chennai. Customer demand has exceeded expectations, prompting Techno Electric to increase the campus’s designed information-technology load without buying more land or adding another building. The increase came from changes in electrical topology, cooling architecture and construction sequencing.
The company is now discussing around 150 megawatts of aggregate information-technology load with hyperscalers, artificial-intelligence infrastructure companies and enterprise customers. Six opportunities are above 3 megawatts, while more than 30 remain in the wider funnel, although these discussions are at different stages of maturity.
It also signed 10 new customer logos in Q1 across colocation, cloud and interconnection, including two leading telecom carriers that together subscribed to about 130 kilowatts, as well as its first cloud-services engagement.
The 150 MW figure, therefore, is a measure of demand under discussion rather than contracted or commissioned capacity.
Why Chennai?
Mumbai is largely committed, with large customers potentially waiting 18 to 24 months for capacity. That is pushing demand towards other cities, while Chennai benefits from its east-coast location, low latency to Singapore and five active submarine cable systems.
The West Asia conflict has also shifted some deployments towards the Asia-Pacific region, while policy changes have made India more attractive to cloud operators serving global customers.
That combination could help Chennai, but Techno Electric still has to convert interest into contracted capacity.
The data-centre business needs patience
Data-centre revenue depends on customers moving in, completing validation and starting billing, so the revenue contribution is expected to be weighted towards the second half of FY27. The business also faces the boring problems that come with a new data-centre buildout, including shortages and higher costs for servers, GPUs and switches that can delay the movement from signed contracts to actual workloads.
The earlier Rs 40 crore revenue guidance for the data-centre business remains in place. Against the company’s FY27 revenue guidance of Rs 4,000 crore or more, that is only about 1%, which makes one thing clear: data centres are not going to transform FY27 earnings. The attraction lies in what this business could become over the next few years, rather than what it contributes today.
That also explains why patience matters. There is plenty of demand being discussed, but the real test is whether that demand turns into occupied capacity, recurring revenue and eventually, attractive returns on the money being spent.
Smart meters could become the bridge
There is another business sitting quietly between the old Techno Electric and the new Techno Electric. Smart metering may not attract the same excitement as data centres, but it accounted for Rs 1,491 crore, or 15.54%, of the company’s Rs 9,596 crore order book at 30 June 2026.
The business is already moving towards its more attractive phase. Installation was 77% complete by June, with full completion targeted by the end of FY27, while Madhya Pradesh has already moved into the annuity phase.
Once the meters are installed, the economics change. The company gets 93 months of contracted operations and maintenance revenue, turning a capital-intensive installation business into a source of recurring cash flows.
That could matter to the wider business. As smart metering starts generating cash and transmission assets are monetised, Techno Electric can recycle some of that capital into newer opportunities such as data centres.
Balance sheet: strong, but cash conversion needs watching
The balance sheet is still a strength, with a net cash position. That gives the company some room to build new businesses without taking on significant financial risk.
But the cash-flow numbers deserve attention. Cash from operating activities was negative Rs 590 crore in FY26, while free cash flow was negative Rs 657 crore. Working-capital days rose sharply to 430 from 92 a year earlier, while debtor days increased to 137 from 108.
| Metric | FY26 |
| Return on capital employed | 14.8% |
| Return on equity | 11.4% |
| Borrowings | Rs 72 crore |
| Reserves | Rs 4,134 crore |
| Cash from operating activities | -Rs 590 crore |
| Free cash flow | -Rs 657 crore |
| Working-capital days | 430 |
| Debtor days | 137 |
That tells us where some of the money is going. Revenue and profits can rise, but if customers take longer to pay and cash remains tied up in receivables and projects, the growth does not immediately arrive in the bank account.
This matters more now because Techno Electric is funding several businesses at once. It is spending on data centres, completing smart-meter projects and building transmission assets, so the ability to convert reported profits into cash will determine how much of this expansion can ultimately be funded internally.
Capex is rising
The company has earmarked about Rs 1,000 crore for its data-centre expansion in FY27. Smart metering, meanwhile, has become self-funded: it expects around Rs 450 crore of collections from the business during the year against about Rs 400 crore of spending on the remaining installations.
Chennai had absorbed Rs 524 crore of capex by 31 March 2026, taking cumulative data-centre capex across the portfolio to Rs 628 crore. FY27 investment is mainly focused on Noida and Kolkata, but the eventual requirement could be higher depending on which large customer opportunities convert.
The important point is that the full burden does not have to fall on the balance sheet. Smart metering is now generating enough cash to fund its remaining rollout, while the EPC business is also expected to fund its own growth without additional working capital.
Returns are where the story will ultimately be judged
Return on capital employed is around 15.6%, while return on equity is around 11.2%. Sales have grown rapidly, but the return ratios have not risen at the same pace.
That is why the data-centre strategy needs to be watched closely. If the new campuses generate strong EBITDA on the capital invested, returns could improve; if capital keeps rising faster than earnings, the transition could become a drag on the company.
For now, investors are being asked to accept lower near-term cash returns in exchange for the possibility of a larger asset base and more recurring revenue in the future.
Valuation and the stock’s recent fall
At around Rs 997, the stock trades at roughly 27 times earnings. That is not a cheap valuation for a conventional engineering company and the market is clearly pricing in some value for the newer infrastructure businesses. The valuation starts to look more reasonable only if data centres become a meaningful source of recurring cash and the company can monetise its other assets efficiently.
The market, however, has not rewarded that transition so far. The stock trades at around Rs 997, roughly 37% below its 52-week high.
The reason is not difficult to see. Cash is being deployed into new businesses, working capital is high and the data-centre business is still too small to materially change the earnings picture.
In other words, investors are being asked to pay today for assets whose profits are still some distance away.
What to watch
The next few quarters are less about another large order announcement and more about conversion. The order book needs to become revenue, revenue needs to become cash, working capital needs to come down and the EBITDA margin needs to stay within the 13% to 14% FY27 guidance range.
Smart-meter cash flows should start becoming more visible as installation nears completion, while transmission-asset monetisation can release capital back into the business. At the same time, the data-centre pipeline needs to turn into contracted capacity and actual billing.
Techno Electric is an unusual infrastructure bet. Its old business provides the moat, smart metering could provide recurring cash, asset monetisation can recycle capital and data centres offer a chance to participate in one of India’s fastest-growing infrastructure markets.
But the balance sheet that makes this opportunity possible can also expose the biggest risk. The question is no longer whether Techno Electric can build more infrastructure; it is whether it can turn that infrastructure into attractive returns without letting working capital and rising capex overwhelm the cash flows.
Disclaimer:
Note: We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Manvi Aggarwal has been tracking the stock markets for nearly two decades. She spent about eight years as a financial analyst at a value-style fund, managing money for international investors. That’s where she honed her expertise in deep-dive research, looking beyond the obvious to spot value where others didn’t. Now, she brings that same sharp eye to uncovering overlooked and misunderstood investment opportunities in Indian equities. As a columnist for LiveMint and Equitymaster, she breaks down complex financial trends into actionable insights for investors.
Disclosure: The writer and her dependents do not hold the stocks discussed in this article. The website managers, its employee(s) and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.