



Welcome to the latest edition of Hidden Gems Weekly. In recent weeks, we examined a company transforming from a traditional industrial manufacturer into a high-value engineering solutions provider, a company that wants to move beyond selling more machine tools to selling better ones and a company quietly conquering India’s industrial supply chain. This week, we turn to a company that wants to move beyond meter boxes to supplying the electrical backbone behind India’s power expansion.
When OpenAI launches a new model or a cloud company announces another data centre, the conversation usually revolves around graphics processing units (GPUs), chips and software. Electricity rarely gets invited into that discussion.
That is odd because electricity is where the story begins.
A data centre does not become operational after servers arrive. Before a single rack is switched on, it requires substations, switchgear, current transformers, metering systems, and distribution equipment capable of safely handling enormous amounts of power. Without that electrical backbone, even the world’s most advanced AI chips remain expensive pieces of silicon.
The same story is playing out beyond data centres. India’s electricity demand is rising as factories expand, railways electrify more routes and industrial parks consume more power. The transmission tower is the visible part of this investment cycle. The less visible part sits inside substations, where hundreds of specialised components quietly decide whether electricity reaches homes, factories and data centres safely.
Join now
That is where Indo SMC’s story becomes interesting.
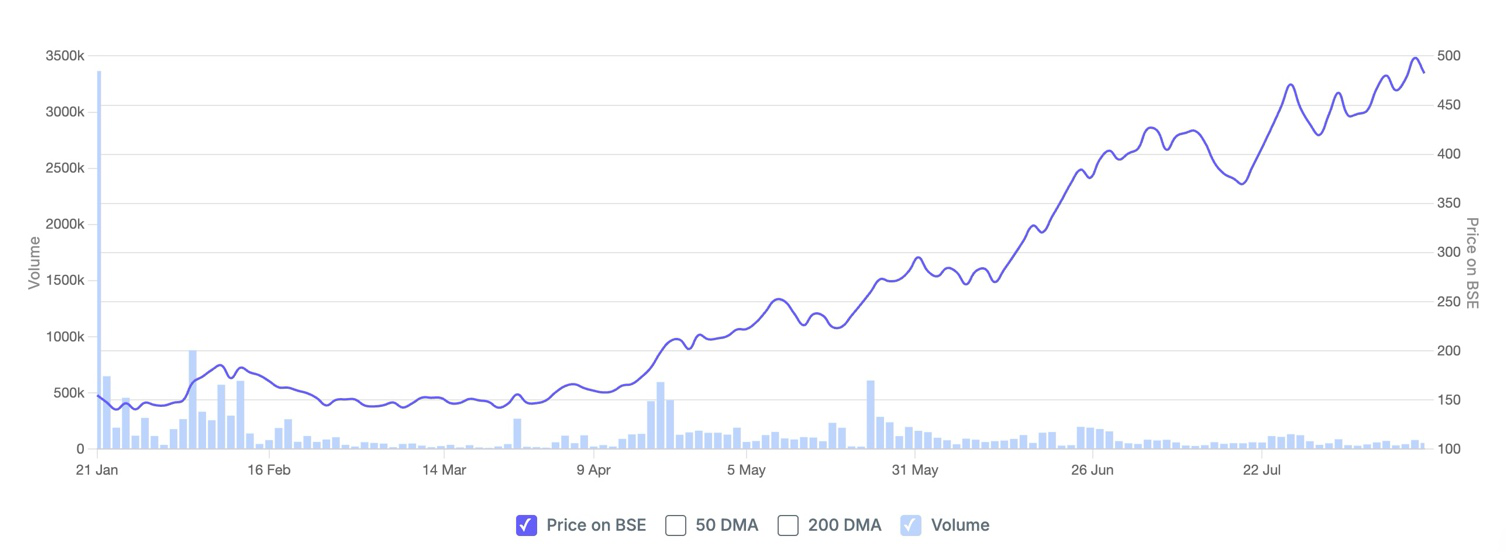
Indo SMC 1-Year Share Price Chart
The recently listed Small and Medium Enterprise (SME) company started by making durable electrical enclosures that protect electricity meters, distribution boxes and wiring from rain, heat and corrosion. It also manufactures Fiberglass Reinforced Plastic products used in industrial walkways, cable trays and utility infrastructure.
Today, it is trying to move up the value chain by supplying higher-value equipment such as Current Transformers, Potential Transformers, metering cubicles and switchgear that operate within substations and power distribution networks.
This pivot is starting to show up in the numbers. Revenue more than doubled in FY26, order visibility has improved and management believes the next phase of growth will come from products that require approvals and engineering capability rather than simply manufacturing capacity.
The invisible moat: Why approvals matter more than factories
Factories can be copied. Approvals cannot.
That is an unusual feature of the electrical utility business. A manufacturer can build a production line in months, but becoming an approved supplier to electricity utilities often takes years of testing, certifications and product validation.
Indo SMC already has approvals across 20 states and supplies multiple State Electricity Boards and Distribution Companies. Management says relatively few manufacturers have approvals in products such as Current Transformers and Potential Transformers, particularly as voltage levels move higher.
India’s power expansion is creating demand for equipment that has already cleared years of testing, certifications and utility approvals. That gives companies with an established approval network a head start that cannot be replicated simply by adding another factory.
The company currently operates largely in the 11 kilovolt and 33 kilovolt segment and plans to gradually move further up the voltage ladder. Its product portfolio already includes metering cubicles, distribution systems, current transformers and electrical panels designed for utility and industrial applications up to 33 kilovolts.
The business is changing faster than its name
Most investors still associate Indo SMC with meter boxes and composite products. That description is becoming increasingly incomplete.
The company still manufactures Sheet Moulding Compound (SMC) enclosures that protect electricity meters, distribution boxes and electrical wiring from rain, heat and corrosion. It also makes Fiberglass Reinforced Plastic (FRP) products such as cable trays, industrial walkways and gratings, which are increasingly replacing metal in utility and industrial projects because they are lightweight and corrosion-resistant.
The bigger shift, however, is happening in its electrical engineering business. Products such as Current Transformers and Potential Transformers (CTPT) (which measure and protect electricity flowing through substations), busducts (which carry large amounts of electricity inside factories and data centres), and metering cubicles (which house utility metering equipment) are becoming a larger part of the business. These products require greater engineering capability and customer approvals, which is why they typically earn better margins than traditional SMC products.
The company’s approach to winning business has also changed. Management says it no longer needs to chase every available order simply to build market presence. Instead, it now chooses contracts based on profitability while steadily expanding its portfolio of higher-value electrical products.
The next step is already planned. Indo SMC intends to launch Panel Circuit Vacuum Circuit Breakers during August 2026, products used across medium-voltage power distribution systems. It is also targeting a meaningful market share in this category over time, although that remains a management aspiration rather than a guaranteed outcome.
Revenue growth is now coming from engineering products
FY26 marked a breakout year financially. Revenue rose to Rs 310 crore from Rs 139 crore in FY25, up 123% YoY. Operating profit increased to Rs 47 crore, while net profit climbed to Rs 32 crore from Rs 15 crore.
Operating margin stood at 15%, compared with 17% in FY25. While raw material prices remained volatile, management believes the growing contribution from engineering products such as CTPT, busducts and metering cubicles should help support margins going forward.
Key Financials
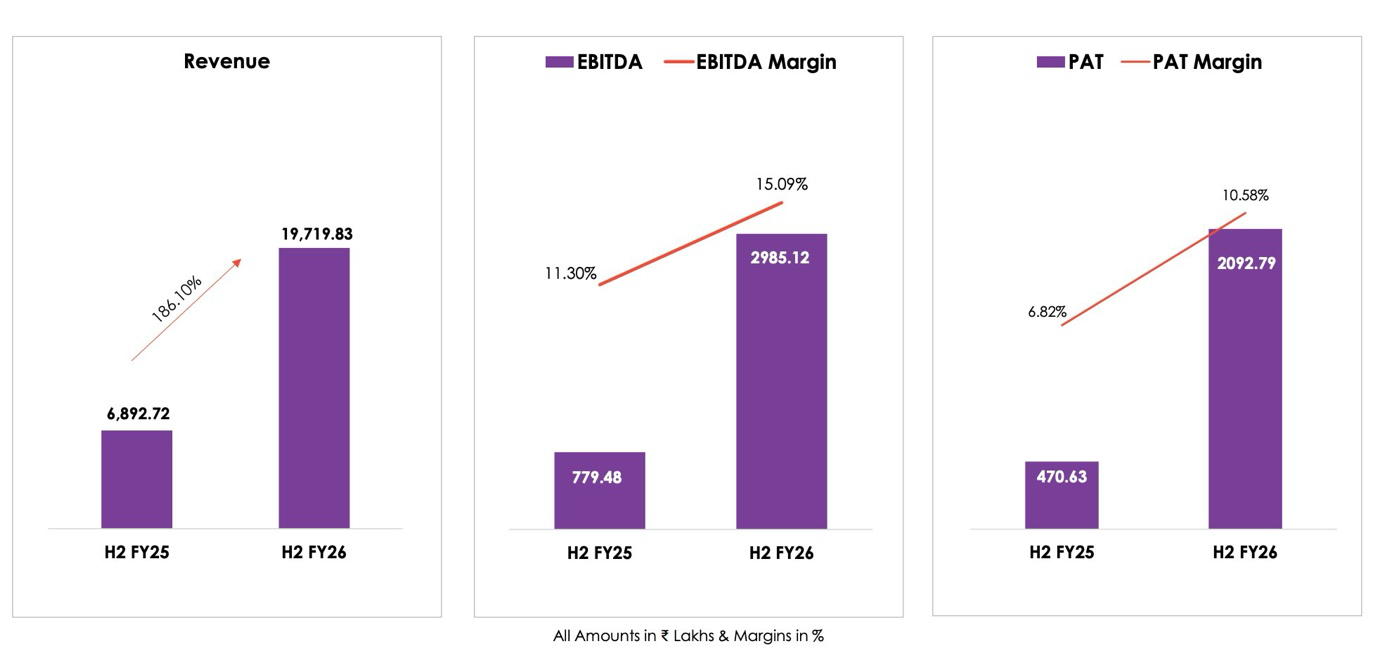
The second half of FY26 showed particularly strong momentum. Revenue reached Rs 197 crore, compared with Rs 69 crore in H2 FY25, while operating margin improved to 15% from 11%, both on a YoY basis.ent is aiming for another year of rapid growth.
Management has outlined an ambitious roadmap for FY27
The company has guided for Rs 450-500 crore in revenue for FY27, implying another year of strong growth after FY26’s sharp expansion.
That confidence comes partly from order visibility. Indo SMC entered FY27 with an order book of Rs 237 crore and subsequently secured another Rs 125 crore of fresh orders, taking total visibility to roughly Rs 360 crore. Management expects most of these orders to be completed within three to six months, allowing fresh order inflows to replenish the pipeline during the year.
Margins remain another focus area. Management expects Earnings Before Interest, Taxes, Depreciation and Amortisation (EBITDA) margin to remain above 15%, with room for gradual improvement if commodity price volatility eases.
The longer-term ambition is even bigger. Management has spoken about building a business capable of crossing Rs 1,000 crore in revenue over roughly three years, although that remains a management target rather than formal financial guidance.
Growth without betting on entirely new factories
One interesting aspect of the company’s expansion is that it is not betting everything on expensive greenfield projects.
Instead, management says much of the next phase can come through machinery, automation and testing infrastructure inside existing facilities. The immediate priority remains the Rs 25 crore capital expenditure planned during the Initial Public Offering, with investments spread across SMC, FRP and engineering products.
The expansion includes increasing SMC capacity beyond 6,000 tonnes, adding 300 tonnes of FRP production and strengthening testing facilities that support CTPT and panel businesses. Management believes these investments could eventually support revenue beyond Rs 750 crore, depending on utilisation and further product additions.
The balance sheet looks healthier, but growth still needs cash
Rapid growth often creates another problem. Companies usually sell more before they collect cash, which makes working capital one of the most important indicators to watch.
Indo SMC has made meaningful progress in collections. Debtor days fell sharply to 42 days from 124 days a year earlier, and management says it is deliberately taking shorter-duration orders with stronger payment terms.
That is only part of the picture. Inventory rose sharply as the company built nearly three months of raw material stock to secure supplies of resin, glass fibre and other inputs during periods of geopolitical uncertainty. As a result, working capital days increased to 88.5 in FY26 from 34 days in FY25, even though collections improved significantly.
The balance sheet has naturally expanded alongside growth. Borrowings rose to Rs 47 crore. Even after that increase, leverage remains relatively comfortable, with a debt-to-equity ratio of around 0.30.
Management believes IPO proceeds should provide sufficient liquidity for the current expansion phase, reducing the immediate need for fresh fundraising during FY27.
Strong returns despite rapid expansion
The company’s return ratios remain impressive despite being in an expansion phase.
Return on Capital Employed stands at 23%, while Return on Equity is 21%. Those numbers reflect rapid revenue growth, tighter receivables management and a gradual shift towards products with greater engineering content.
Return Profile
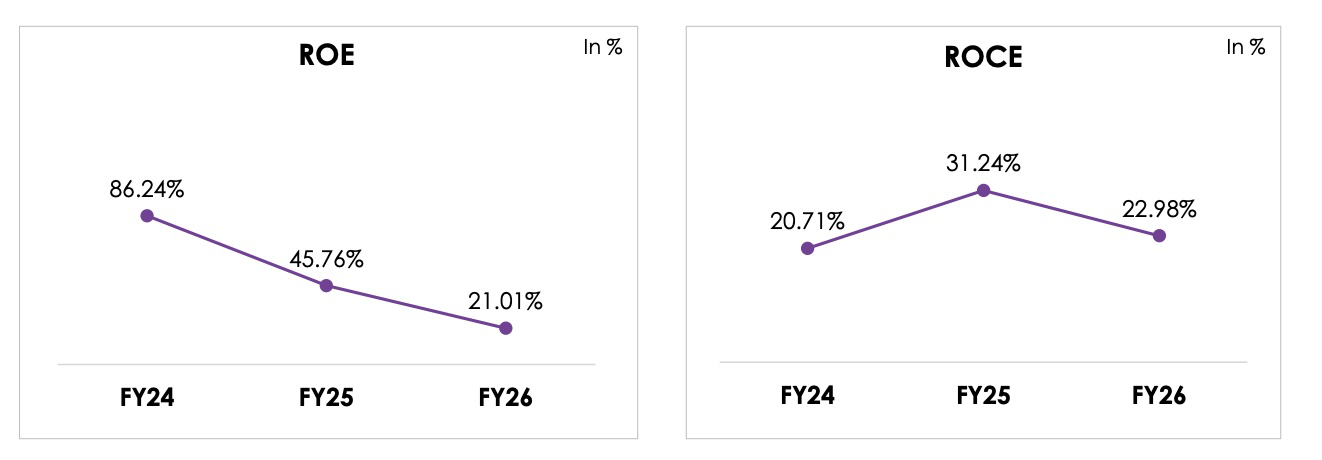
The challenge now is whether those returns can remain elevated as capacity expands and newer businesses become a larger part of the revenue mix.
Valuation already reflects high expectations
At the current market price of around Rs 449, Indo SMC trades at about 34 times earnings. That valuation already assumes another year of strong growth. The next few quarters will therefore matter because revenue growth, margin stability and order conversion will have to keep pace with those expectations.
SME investing comes with a different set of risks
Indo SMC is still an SME-listed company, which brings risks beyond the business itself.
Trading volumes can be lower than on the main board, price movements can become sharper during periods of volatility and liquidity can dry up quickly if investor sentiment weakens. That makes valuation swings more pronounced than investors might expect in larger listed companies.
Rapidly growing SMEs also face another challenge. Scaling manufacturing requires additional working capital, inventory and customer approvals, which means growth can temporarily put pressure on cash flows even when reported profits continue rising. Investors tracking Indo SMC over the next few years may therefore need to watch receivables, inventory levels and cash flows as closely as revenue growth.
The bigger story
The easiest way to describe Indo SMC is as a manufacturer of electrical products. That may also be the least interesting description.
The more interesting story is that India’s biggest investment themes, from AI and data centres to industrial expansion and power distribution upgrades, all depend on a layer of electrical infrastructure that rarely makes headlines. Substations may not generate the excitement of semiconductor factories or cloud campuses, but they become indispensable every time electricity demand rises.
Indo SMC is trying to move deeper into that invisible part of the value chain, where approvals, testing capability and engineering expertise matter as much as manufacturing capacity. If that transition continues, the company could gradually become less of an SMC manufacturer and more of an electrical infrastructure supplier that benefits from one of India’s longest-running infrastructure trends.
Disclaimer:
Note: We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Manvi Aggarwal has been tracking the stock markets for nearly two decades. She spent about eight years as a financial analyst at a value-style fund, managing money for international investors. That’s where she honed her expertise in deep-dive research, looking beyond the obvious to spot value where others didn’t. Now, she brings that same sharp eye to uncovering overlooked and misunderstood investment opportunities in Indian equities. As a columnist for LiveMint and Equitymaster, she breaks down complex financial trends into actionable insights for investors.
Disclosure: The writer and her dependents do not hold the stocks discussed in this article. The website managers, its employee(s) and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.