



Welcome to the latest edition of Hidden Gems Weekly. In recent weeks, we examined a hidden small-cap quietly moving into AI’s least understood opportunity, a high-value engineering solutions provider, a company that wants to move beyond selling more machine tools to selling better ones and a company quietly conquering India’s industrial supply chain. This week, we turn to a company that wants to move beyond meter boxes to supplying the electrical backbone behind India’s power expansion.
India’s infrastructure story has quietly entered a new phase. Roads grabbed the headlines for years. Then railways followed and defence became the market’s favourite theme. Now another sector is attracting enormous government spending without generating the same excitement, and that sector is maritime infrastructure.
Under Maritime Amrit Kaal Vision 2047, India wants to modernise ports, expand inland waterways, promote green harbour infrastructure and strengthen domestic shipbuilding. The long-term investment pipeline runs into nearly Rs 80 lakh crore, creating opportunities that extend well beyond companies that simply own ports.
Join now
Knowledge Marine & Engineering Works Ltd (KMEW)sits lower in that ecosystem, and that is precisely what makes its story interesting.
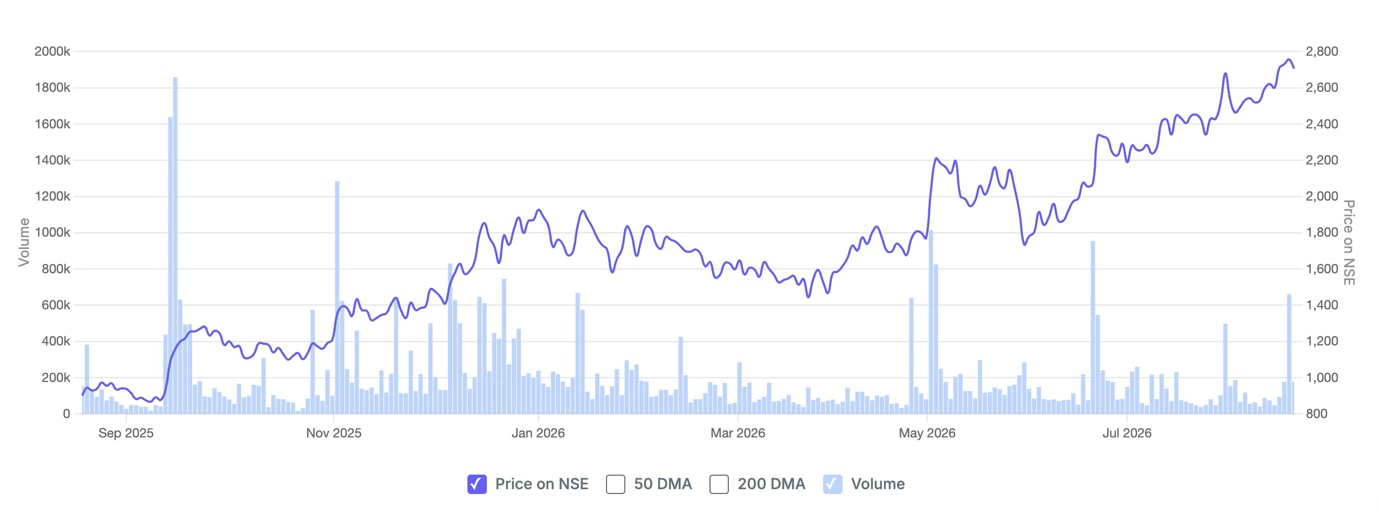
Knowledge Marine & Engineering Works 1-Year Share Price Chart
Instead of operating ports, the company dredges waterways, charters specialised marine vessels and now wants to manufacture many of those vessels itself, gradually changing how it could earn over the next decade.
The market has already begun pricing in that possibility. The stock has climbed from its 52-week low of Rs 852 to around Rs 2,706 because investors began valuing KMEW less like a contract dredging company and more like a business trying to build recurring charter income, shipbuilding capabilities and specialised marine assets.
That shift raises the real question. Can earnings grow fast enough to justify a stock that is already being valued for what management hopes the company will become, rather than simply what it is today?
The company is making a much bigger bet than it first appears
Most engineering companies grow by taking larger contracts. KMEW is expanding differently because it is trying to move beyond operating marine assets and become a company that builds, owns and maintains them as well.
That sounds like a small difference, but it is not. When a company controls both manufacturing and operations, it potentially earns at multiple stages of the value chain instead of paying another shipbuilder to construct vessels.
Management has already started building that ecosystem. The company acquired a shipbuilding subsidiary, purchased land near the upcoming Vadhvan Port for a new shipyard and has begun manufacturing vessels for government projects, making shipbuilding an increasingly important part of its long-term strategy.
If that transition succeeds, KMEW would no longer depend only on winning the next dredging contract. Instead, it would increasingly own the assets that generate those contracts, creating another layer of earnings that many specialised marine contractors do not have.
The order book is changing in quality, not just size
Investors often become obsessed with order books because large numbers create an immediate impression of future growth. But the quality of an order book matters more than the headline figure, especially when long-duration contracts create recurring revenue instead of one-time income.
KMEW finished FY26 with an order book of around Rs 1,400 crore after securing record order inflows of Rs 1,075 crore during the year. The more important detail, however, lies inside those contracts.
Segment-wise Unexecuted Order Book
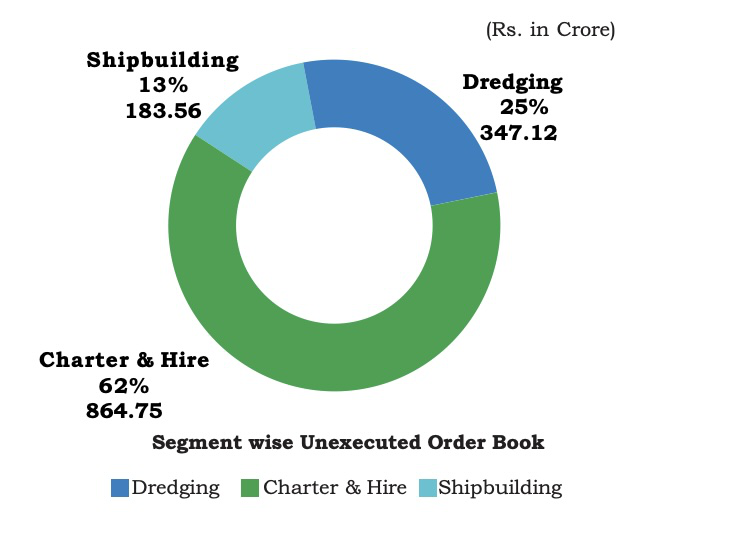
Two Green Tug Transition Program contracts worth around Rs 650 crore run for 15 years, creating unusual revenue visibility for a company of this size. Unlike a typical dredging contract that ends once work is completed, these agreements can continue generating income long after the vessels are deployed.
Those tugboats will also be built at KMEW’s upcoming Saphale shipyard, allowing the company to earn from both manufacturing and operations. That makes these contracts more valuable than a conventional order win.
One dredger explains the bigger opportunity
Most companies become larger by buying more equipment. Sometimes, one specialised asset changes the kind of business a company can compete for, and River Pearl 47 appears to be that asset for KMEW.
The vessel is India’s largest and deepest Indian-flag self-propelled backhoe dredger, capable of working at depths of up to 30 metres. That does not make KMEW bigger than Dredging Corporation of India, which still has the country’s largest dredging fleet. But it does give KMEW a niche capability because Dredging Corporation of India’s existing backhoe dredger is a non-propelled vessel with a maximum dredging depth of 21.5 metres.
That advantage became visible at the Jawaharlal Nehru Port Authority project, where Dredging Corporation of India awarded KMEW a technically demanding rock dredging contract involving underwater drilling and controlled blasting. Management believes similar work is emerging at ports such as New Mangalore, Visakhapatnam, Mumbai and Tuticorin, and expects River Pearl 47 to remain utilised for more than 240 days a year over the next two to three years.
If that happens, the vessel becomes more than a showcase asset. It becomes proof that a smaller company can expand its addressable market by solving problems that larger fleets are not always best positioned to solve.
The ambition goes beyond the next order book
Management is no longer talking only about winning the next dredging contract. It is talking about building an integrated maritime infrastructure business that can design, build, own and operate marine assets, making the company less dependent on any single segment of the maritime value chain.
The near-term targets remain ambitious. Management expects revenue to grow by around 30% year-on-year in both FY27 and FY28, while maintaining EBITDA margins between 35% and 40%. It also says the bidding pipeline exceeds Rs 2,000 crore, with a meaningful portion expected to convert into orders over the coming months.
The longer-term ambition goes beyond financial guidance. The new Saphale shipyard is being designed to build vessels ranging from 10 metres to 120 metres in length, and management says it is already marketing those capabilities in Europe with the eventual aim of delivering up to 14 vessels annually. If that plan works, KMEW would gradually earn not just from operating vessels, but from building and deploying them as well.
The financials are beginning to back the story
At first glance, FY26 looks straightforward. Revenue increased from Rs 201 crore to Rs 256 crore, up 28%. Operating profit rose from Rs 78 crore to Rs 97 crore, while net profit climbed from Rs 50 crore to Rs 79 crore, with operating margins remaining close to 38%.
Financial Snapshot
| Metric | FY25 | FY26 |
| Revenue | Rs 201 crore | Rs 256 crore |
| Revenue Growth | – | 28% |
| Operating Profit | Rs 78 crore | Rs 97 crore |
| Operating Margin | 39% | 38% |
| Net Profit | Rs 50 crore | Rs 79 crore |
The March quarter initially worried investors because operating margin dropped to around 27%. Management, however, attributed this to project accounting rather than weaker profitability, saying substantial expenses were recognised in the March quarter while revenue shifted into the following quarter because payments depended on project completion.
The June quarter certainly looked stronger, with revenue reaching Rs 115 crore and operating margin expanding sharply to 64%. That does not necessarily mean future quarters will consistently report similar margins, but it does illustrate how milestone-based billing can distort quarterly comparisons.
The tax benefit could quietly reshape profitability
One change deserves more attention because KMEW has shifted part of its business under India’s tonnage tax regime. Unlike normal corporate taxation, shipping income under this framework is taxed based on vessel tonnage rather than profits.
Management says dredging and chartering operations now fall under this regime, while shipbuilding continues under the regular corporate tax structure. The lower tax burden leaves more cash available for fleet expansion, an advantage that becomes more meaningful as capital spending accelerates.
The next phase will demand disciplined capital allocation
Management plans Rs 400-500 crore of capex in FY27, making it one of the company’s biggest investment years. Around Rs 100 crore will go towards the Saphale shipyard, while the rest will fund dredgers, tugboats and additional fleet capacity.
The expansion carries execution risk. Shipyards take time to develop, vessels need contracts before generating returns, and management has indicated future funding could come through debt or equity depending on market conditions and vessel availability.
The real test is funding the next phase of growth
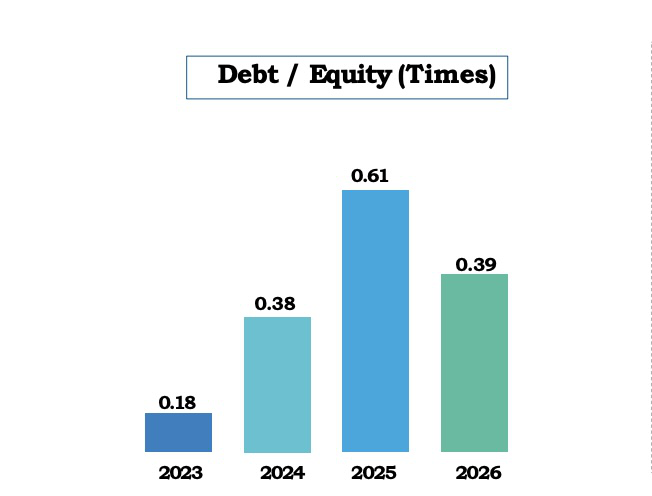
KMEW’s balance sheet is entering an investment cycle rather than simply harvesting completed projects. Short-term borrowings have risen, but management says much of that debt relates to short-duration contracts and is expected to be repaid through internal cash generation.
The company also raised Rs 285 crore through a preferential issue. Including fixed deposits, cash balances exceed Rs 350 crore, with roughly Rs 300 crore available after adjusting for bank guarantees, giving it meaningful financial flexibility ahead of expansion.
The ratios still look comfortable despite higher leverage. According to Screener.in, Debt-to-Equity stands at 0.41, Interest Coverage is 8.52 times, Return on Equity is around 20%, and Return on Capital Employed is about 16.4%. The bigger test begins when FY27’s planned Rs 400-500 crore capital expenditure starts flowing through the books.
Working capital could become the real monitorable
Order books often grab the headlines. Cash conversion rarely does. For companies executing marine infrastructure projects, however, the second number can become far more important because mobilisation costs arrive before revenue, while payments are often tied to project milestones rather than continuous billing.
KMEW’s March quarter offered a glimpse of that reality. Operating margin fell to around 27% because costs were recognised before revenue from key dredging projects, only for much of that impact to reverse in the June quarter. That is a reminder that quarterly earnings can look choppy even when the underlying business remains healthy.
The receivables trend tells a similar story. Debtor Days fell from 131 in FY25 to 109 in FY26, while the Cash Conversion Cycle also improved to 109 days from 131 days. The direction is encouraging, but both numbers remain above FY24 levels. As KMEW takes on larger contracts and builds a shipyard, converting profits into cash could become just as important as winning the next order.
Valuation
This is where the story becomes more complicated. The stock trades at around 53 times earnings and roughly 12 times book value, demanding multiples for a company entering one of its largest investment cycles.
The premium reflects expectations that KMEW will successfully transform into a broader maritime infrastructure platform rather than remain only a dredging contractor. Investors are no longer paying for the company KMEW is today. They are paying for the company management believes it can become.
Why investors should remember its SME roots
KMEW has moved beyond the Small and Medium Enterprise platform, but businesses emerging from that ecosystem often carry different risks from mature large-cap companies. Liquidity can be thinner, earnings can swing with project timing, and milestone-based government payments can delay cash flows even when reported profits look strong.
That makes quarterly cash generation, receivables and capital allocation just as important as revenue growth in judging whether the next phase of expansion is creating durable value.
One reminder that not every opportunity will convert immediately comes from Bahrain. Management has kept the overseas sand mining project outside the active order book until regional conditions stabilise, showing that overseas expansion remains dependent on factors beyond the company’s control.
The bigger picture
The easiest way to understand KMEW is not as a dredging company but as a business trying to earn at every stage of a port’s life. Build the vessel, own the vessel, deploy the vessel and maintain the vessel.
That is an ambitious strategy at a time when India is preparing for one of its largest maritime investment cycles. Whether that ambition ultimately justifies a premium valuation will depend less on winning the next order and more on converting today’s aggressive investment programme into tomorrow’s cash flows.
Disclaimer:
Note: We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Manvi Aggarwal has been tracking the stock markets for nearly two decades. She spent about eight years as a financial analyst at a value-style fund, managing money for international investors. That’s where she honed her expertise in deep-dive research, looking beyond the obvious to spot value where others didn’t. Now, she brings that same sharp eye to uncovering overlooked and misunderstood investment opportunities in Indian equities. As a columnist for LiveMint and Equitymaster, she breaks down complex financial trends into actionable insights for investors.
Disclosure: The writer and her dependents do not hold the stocks discussed in this article. The website managers, its employee(s) and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.