



Welcome to the latest edition of Hidden Gems Weekly. In recent weeks, we examined a company that wants to move beyond meter boxes, a company transforming from a traditional industrial manufacturer into a high-value engineering solutions provider and a company that wants to move beyond selling more machine tools to selling better ones. This week, we look at a company that has spent 37 years mastering a tiny but critical part of the tyre, and is now trying to turn that niche into a much bigger business.
There is a piece of steel wire inside every tyre that most people have probably never heard of. It is called bead wire, and its job is rather important: it holds the tyre to the rim and helps transfer the load of the vehicle from the rim to the road.
Rajratan Global Wire has spent the better part of 37 years doing little else. The company moved from steel trading into bead wire in 1989 and today supplies some of the world’s largest tyre makers, including Bridgestone, Michelin, Goodyear, Continental, Yokohama, MRF, CEAT, Apollo Tyres and JK Tyre.
That makes Rajratan an unusual kind of industrial company. It sells a product that is a small part of the cost of a tyre, but a failure can have very large consequences. And once a tyre maker has approved a supplier, changing that supplier is not as simple as asking another company to quote a lower price.
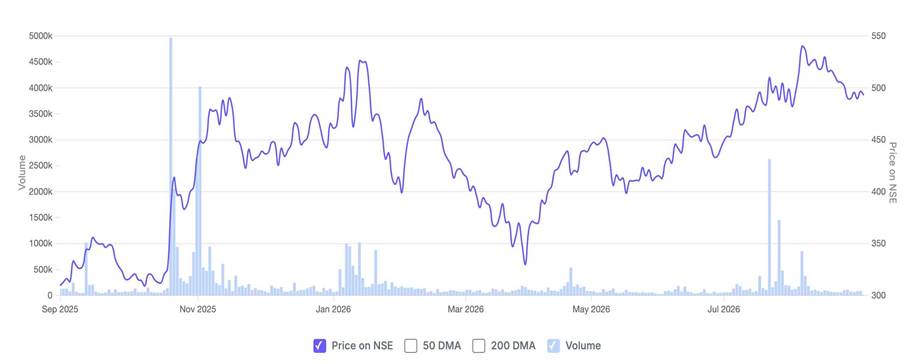
Rajratan Global Wire 1-Year Share Price Chart
The interesting question now is what Rajratan does with that position. After spending decades becoming difficult to replace, the company is adding capacity, pushing exports, expanding in Thailand and Chennai and making its first meaningful move beyond bead wire.
The real business is not wire. It is getting approved
This is where Rajratan gets interesting. A bead wire supplier has to go through qualification before a tyre manufacturer can start using its product, and Rajratan says the process can involve multi-year qualification cycles. Changing suppliers can also mean requalifying individual tyre products.
So, unlike a straightforward commodity business, the customer cannot necessarily switch suppliers every time somebody offers a slightly cheaper product. The wire has to consistently meet very narrow specifications, and the supplier has to be trusted over millions of metres of production.
Rajratan describes this as an approval moat. Global bead wire supply is concentrated among a handful of qualified names, while Rajratan says it is the market leader in India by installed capacity and market share and the only bead wire manufacturer in Thailand.
There is another interesting feature to this business. Bead wire is relatively inexpensive compared with the tyre itself, but the cost of failure is high. A tyre maker therefore has a reason to value consistency and reliability over saving the last rupee on the purchase price.
The result is a niche industrial business where customer relationships can last for years. Rajratan now has to show that this customer stickiness can translate into faster growth.
Capacity is no longer just a future promise
For several years, the investment story was largely about building capacity. The company has now reached the point where filling that capacity is becoming more important.
Rajratan currently has 162,000 tonnes per annum of installed capacity across Pithampur, Thailand and Chennai. The company plans to double Chennai’s capacity from 30,000 tonnes to 60,000 tonnes, taking its overall capacity to 192,000 tonnes.
Pithampur accounts for 72,000 tonnes of capacity, of which 60,000 tonnes is for bead wire, while Thailand has 60,000 tonnes. Chennai currently has 30,000 tonnes installed and is being expanded through additional balancing equipment.
Chennai is particularly important because it puts Rajratan closer to the large tyre manufacturing cluster in southern India. The facility has moved past the stage of being a new plant that consumes money without contributing much to profit. Management said it had crossed break-even in the previous quarter and started contributing positively in Q1 FY27.
Management expects Chennai to produce about 34,000 to 35,000 tonnes in FY27, compared with around 17,000 tonnes in the previous year. The increase is significant because it allows the company to grow volumes without having to build an entirely new plant.
That is the attraction of the Chennai expansion. Rajratan is not trying to establish a new product and then find customers for it. It is adding capacity for a product for which it already has customer relationships and approvals.
Q1 FY27 showed what higher utilisation can do
The June quarter provided an early demonstration of the operating leverage in the business. Consolidated sales volume rose 16% year-on-year to 33,300 tonnes, with India and Thailand volumes both increasing 16% to 19,710 tonnes and 13,590 tonnes, respectively.
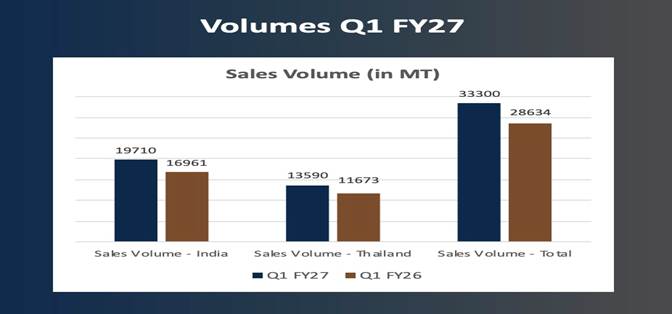
Revenue increased 29% year-on-year, while EBITDA rose 35%. The EBITDA margin improved to 13.10% in Q1 FY27 from 12.55% in Q1 FY26 and the PAT increased 70% to Rs 22.96 crore.
Management attributed the improvement to a richer customer mix, better realisations and higher capacity utilisation, which improved manufacturing efficiencies and reduced unit costs. The company is prioritising market share and sales growth over short-term margin expansion, with higher volumes helping improve utilisation and reduce unit costs.
The strategy appears to be working for now, but the key question is whether the margin improvement can hold as utilisation rises further.
The target is to sell more than the company has been selling
Management has indicated that Rajratan could reach around 155,000 tonnes of total sales in FY27 if global conditions remain normal. That would represent volume growth of roughly 17% to 18%, with Thailand expected to grow at around 10% to 11% and India providing most of the incremental growth.
The Chennai plant is to contribute 34,000 to 35,000 tonnes in FY27, almost twice the previous year’s volume. The company is also looking for higher utilisation across its other facilities as it tries to regain and expand market share.
Exports provide another leg to the growth plan as North American volumes could grow by around 30%, Europe by around 50% and Southeast Asia by around 10% to 15%, although the European growth rate starts from a relatively low base.
Rajratan is increasingly looking beyond India’s domestic tyre cycle, using its manufacturing footprint in India and Thailand to serve global customers. The weaker rupee could further support its export business by improving the competitiveness of its Indian operations.
Thailand is more than another factory
Thailand is perhaps the least obvious part of the story, but it gives Rajratan something that many Indian competitors do not have.
The company says it is the only bead wire manufacturer in Thailand and is already embedded in the plants of global tyre manufacturers operating there. It has also secured land in Ratchaburi for its next phase of growth.
This gives Rajratan a second manufacturing base in a major tyre-producing country. It also allows the company to decide where to manufacture depending on customer location, available capacity and transportation costs.
The advantage becomes more important as exports increase. A global tyre maker is unlikely to care whether a particular batch of wire came from Pithampur or Thailand. It cares whether the product meets specification and arrives when required.
Rajratan’s two-country manufacturing footprint therefore adds another layer to its customer proposition. The company can offer the same product from multiple locations while remaining inside the customer’s approved supply chain.
The company is also trying to repeat the moat outside tyres
Rajratan has spent most of its history focused on bead wire. It is now making its first meaningful attempt at diversification through steel cord for conveyor belts.
The project is being developed at Pithampur and is interesting because it uses the company’s existing metallurgy capabilities while moving into an adjacent industrial market. More importantly, the new product could have its own customer qualification barriers.
This is potentially more interesting than simply launching another steel product. Rajratan’s real competitive advantage is not necessarily the ability to manufacture steel wire. It is the ability to get qualified, maintain quality and stay embedded in a customer’s production process.
If that model works for conveyor-belt steel cord as well, the company could gradually build another niche business around the same capabilities.
But it is still early. The steel cord business should be treated as an option rather than as a major part of the current earnings story. Management has indicated that volumes from the project are not included in the 155,000-tonne FY27 sales target.
Revenue growth has returned, but margins have not fully recovered
The longer-term numbers make the current expansion story more complicated.
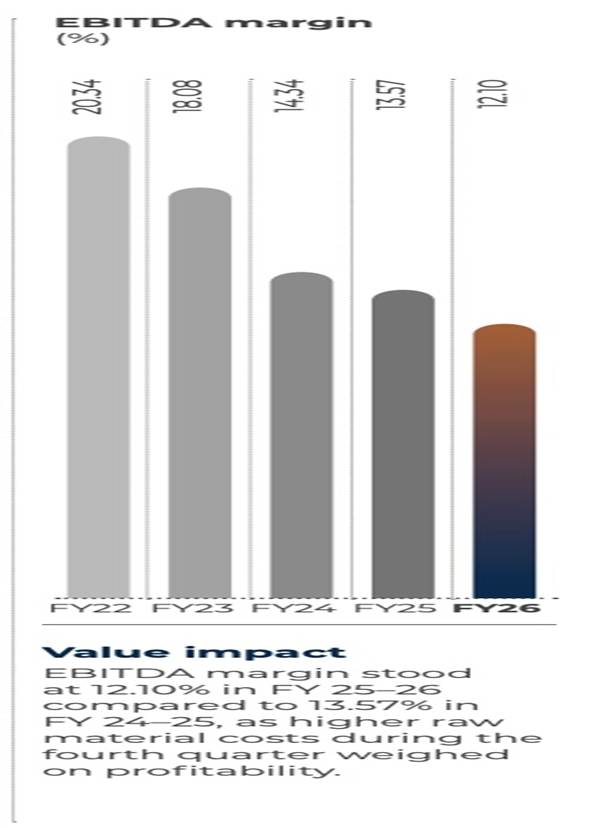
Consolidated revenue increased by 24%. Operating margin, however, declined from 14% to 12%. This is an important point because Rajratan is not a business where revenue growth automatically translates into proportional profit growth. Steel prices, realisations, customer mix, energy costs and competitive intensity can all affect margins.
The Q1 FY27 numbers are encouraging because EBITDA grew faster than revenue and the EBITDA margin improved to 13.10%, after declining to 12.10% in FY26 from 13.57% in FY25. The improvement in Q1 FY27 therefore marks a recovery from the margin pressure seen last year.
But the company itself has acknowledged that the competitive environment remains challenging and that it has been willing to prioritise market share over short-term margin expansion.
The next few quarters will therefore tell investors whether Q1 marked the beginning of a sustained improvement or simply a particularly good quarter.
The balance sheet, returns and cash flow need watching
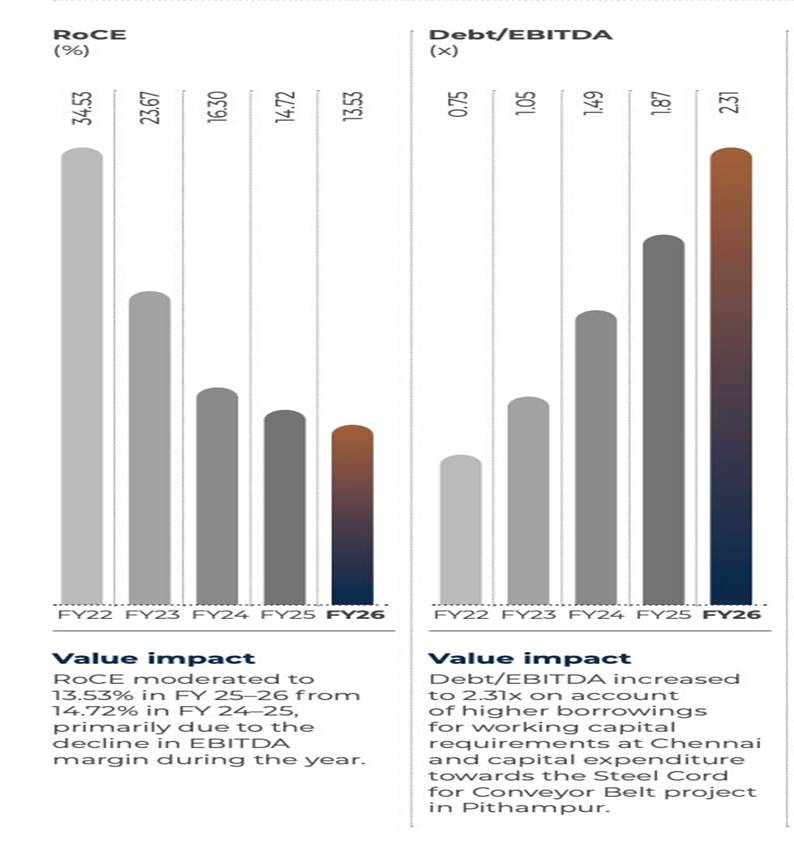
All this expansion requires money. Rajratan’s borrowings increased from Rs 237 crore in FY25 to Rs 324 crore in FY26, while its debt-to-equity ratio is around 0.50 and interest coverage is about 4.56 times.
Rajratan’s Return on Capital Employed (ROCE) stood at 13.5% in FY26, down from 14.7% in FY25 and 34.5% in FY22, while Return on Equity (ROE) stood at around 11.5%. The improvement in Chennai’s utilisation could lift returns, but only if higher volumes translate into healthy margins.
Working capital has improved on some measures, with inventory days falling from 68 to 54 and working capital days from 22 to 12. However, debtor days increased from 71 to 81, pushing the cash conversion cycle up from 59 to 62 days.
Cash generation also remains an area to watch. Cash generated from operations increased from Rs 57 crore in FY25 to Rs 75 crore in FY26, but Rs 113 crore was spent on investing, resulting in negative free cash flow. For a company in an expansion phase this is not necessarily a concern, but the new capacity will need to generate enough cash to justify the capital being deployed.
Valuation and the small-cap risk
At around Rs 494, Rajratan trades at about 31.5 times earnings. The valuation already factors in some of the benefits expected from Chennai, exports, higher utilisation and its established customer relationships, leaving less room for disappointment.
That is particularly relevant for a small-cap industrial company. Rajratan’s customer approvals provide a meaningful barrier to switching, but they do not protect the business from a weak tyre cycle, pricing pressure, higher working capital or poor returns on new capital.
With ROCE at 13.5%, ROE at 11.5%, borrowings at Rs 324 crore and negative free cash flow in FY26, the company still has to prove that its expansion can generate sufficiently high returns. The moat is visible, but the returns on the next round of capital are still to be established.
The next test is whether the moat can compound
Rajratan’s first 37 years were about becoming difficult to replace. The next phase is about proving that customer stickiness can support a much larger business.
The ingredients are certainly there. Chennai has crossed break-even, Thailand gives the company a unique position, exports are expanding and management is targeting roughly 155,000 tonnes of total sales in FY27. The company also expects Chennai to contribute around 34,000 to 35,000 tonnes, while continuing to push utilisation and market share across its manufacturing network.
But the stock now needs more than a good story. Investors will need to see whether the additional tonnes translate into higher margins, stronger cash generation and, most importantly, better returns on capital.
That is what makes Rajratan interesting. The company is not trying to become the biggest steel-wire manufacturer in the country. It is trying to remain indispensable in a very small corner of the tyre industry, and then use that position to expand into adjacent markets.
For a business that has spent 37 years doing one hard thing well, the next challenge may be harder still: making all that customer trust work harder for shareholders.
Note: We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Manvi Aggarwal has been tracking the stock markets for nearly two decades. She spent about eight years as a financial analyst at a value-style fund, managing money for international investors. That’s where she honed her expertise in deep-dive research, looking beyond the obvious to spot value where others didn’t. Now, she brings that same sharp eye to uncovering overlooked and misunderstood investment opportunities in Indian equities. As a columnist for LiveMint and Equitymaster, she breaks down complex financial trends into actionable insights for investors.
Disclosure: The writer and her dependents do not hold the stocks discussed in this article. The website managers, its employee(s) and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.