



India has spent decades building some of the world’s most complex energy projects. And there is a company that has quietly been involved in many of them. Its expertise was built around oil refineries, petrochemical plants and other large energy projects, but that expertise is now being taken into newer areas.
This transition is important because not all engineering work earns the same money. Consultancy can generate substantially higher margins than large turnkey projects, and the company is increasingly tilting its business towards it.
That raises a more interesting question than whether the company can grow revenue. Can a change in business mix turn a steady public-sector engineering company into a structurally more profitable one?
The company behind all of this is Engineers India Limited (EIL).
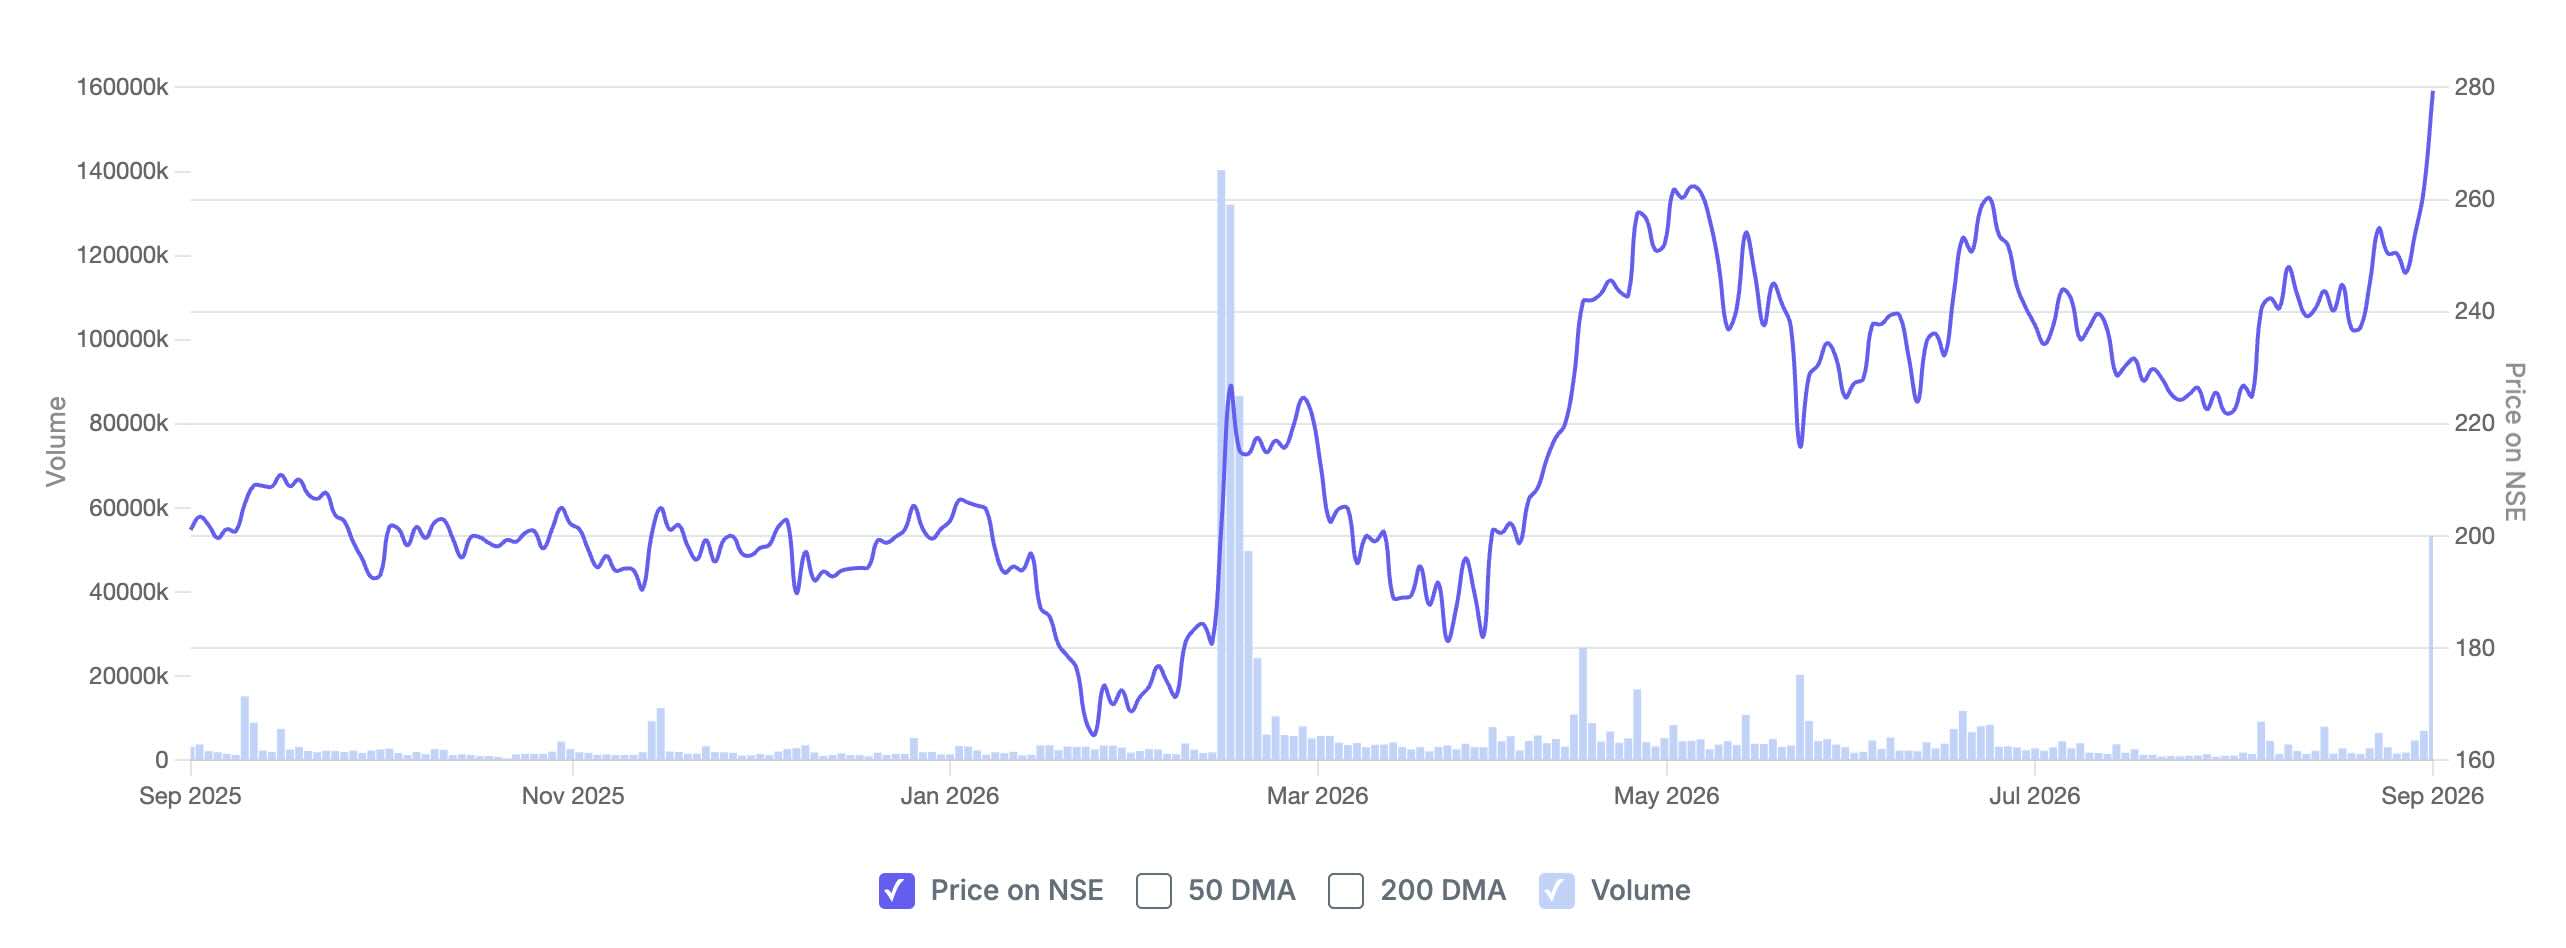
Engineers India 1-Year Share Price Chart
The business mix has already started moving. Consultancy accounted for about 62% of turnover in Q1 FY27, while it contributed 48% of total turnover in FY26. Management expects consultancy to contribute more than 50% of FY27 turnover, with 55% as the minimum figure it has indicated.
Consultancy is becoming a larger part of Engineers India’s turnover
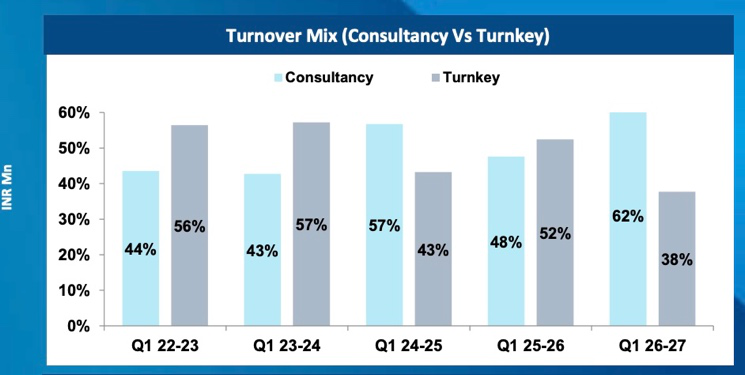
The change is not a one-quarter phenomenon. Consultancy’s share of turnover has risen steadily from 44% in Q1 FY23 to 62% in Q1 FY27, while the share of turnkey work has moved in the opposite direction.
The strange quarter when lower revenue produced much higher profit
The first quarter of FY27 gives a good idea of why the changing mix is important. Consolidated revenue was around Rs 820 crore, down about 6% year-on-year, yet consolidated profit after tax jumped 141% to Rs 157.94 crore from Rs 65.4 crore.
On a standalone basis, turnover was Rs 801 crore compared with Rs 857 crore in Q1 FY26. Earnings before interest, taxes, depreciation and amortisation (EBITDA), however, rose to Rs 155 crore from Rs 104 crore, taking the EBITDA margin to 19.35% from 12.13%. Operating profit margin was around 14%, compared with 7% a year earlier.
The reason was not complicated. Consultancy revenue increased 22% to Rs 499 crore, while turnkey revenue fell 33% to Rs 302 crore as some large projects tapered off. The company said newer turnkey orders are still at an early stage and should contribute more in Q3 and Q4.
Simply put, the company sold more of the business that earns higher margins and less of the business that earns lower margins. So, for once, lower revenue was actually not a bad thing.
From oil and gas to nuclear, coal gasification and data centres
The interesting part of the Engineers India story is that the company is no longer dependent only on the next refinery or petrochemical project. It is taking the engineering capabilities built over six decades in hydrocarbons into newer areas where the same expertise can be used.
Nuclear is one such area. The company is currently working on environmental studies for four projects, including three for a private investor and one for the government. Moreover, it is also engaged with the Nuclear Power Corporation of India Limited on consultancy assignments after having secured small modular reactor consultancy projects in the previous year.
Coal gasification is another emerging opportunity. Following the government’s revised policy and proposed Rs 34,000 crore viability-gap funding, Engineers India has seen more enquiries for feasibility studies and is bidding for projects, while already working on an NTPC gas-to-synthetic natural gas project.
Then there is specialized infrastructure. The company secured a major data centre assignment from PowerTel and is also looking at research and development facilities, institutional projects and other specialized infrastructure. The company is deliberately avoiding ordinary construction and focusing on projects where its existing engineering and project management capabilities give it an advantage.
These businesses are still too small to change the financials on their own. But they give Engineers India something it did not have earlier: more markets in which to sell the same expertise.
The order book is changing too
The company entered FY27 with an order book of Rs 14,424 crore, of which Rs 10,498 crore was consultancy and Rs 3,926 crore was turnkey. Consultancy therefore made up about 73% of the order book, compared with 56% a year earlier.
Order book mix
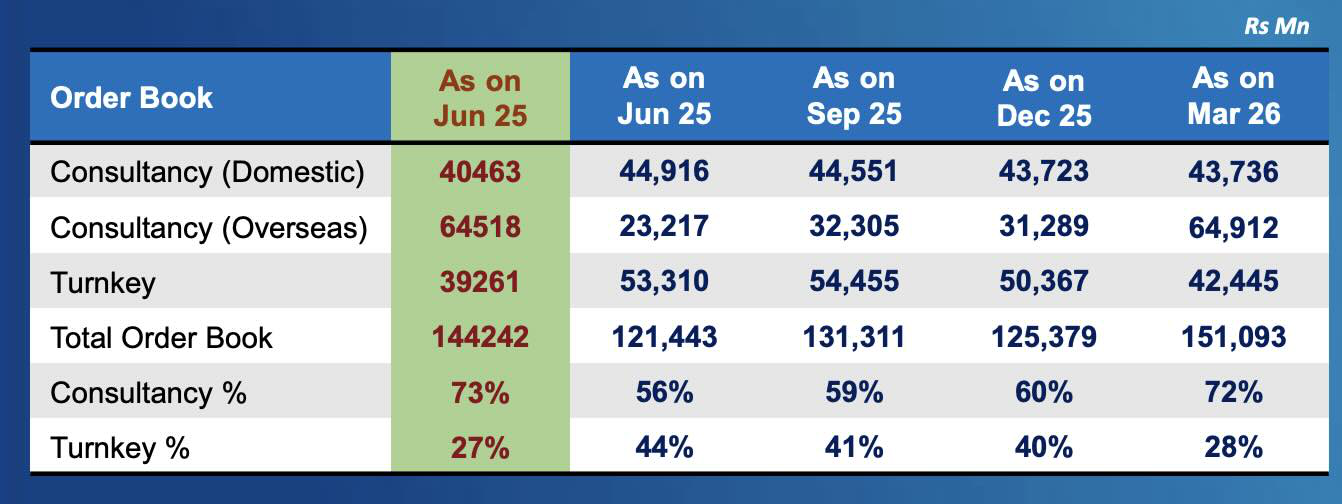
That mix matters more than the headline order-book number. Consultancy carries much higher margins than turnkey work, so a larger consultancy book could support better profitability as these projects turn into revenue.
There is a catch, though. Large projects can take four to five years to complete, while mid-sized projects can take two to three years and smaller studies around a year. So a large order book does not automatically mean a similar jump in revenue in the next quarter.
Management has set two targets
For FY27, management is targeting at least 10% growth in turnover and an order inflow of Rs 8,000 crore. It has not changed the order inflow target and said it was hopeful of meeting it, or even crossing it.
The other target is more interesting for investors. Management expects consultancy to contribute more than 50% of turnover, with 55% as the minimum figure it has indicated, and said consultancy revenue could reach around Rs 2,300 crore to Rs 2,400 crore during FY27.
That is where the earnings story gets interesting.
The margin difference changes the equation
Consultancy is simply a better business for Engineers India. Its segment profit margin was 24% in Q1 FY27, up from 17% a year earlier, while the lump sum turnkey (LSTK) projects segment margin was 7.5%. Management expects consultancy segment margins to remain around 24% to 25%.
This means Engineers India does not necessarily need spectacular revenue growth to produce strong profit growth. If consultancy keeps taking a larger share of revenue, the company can potentially grow earnings through a better mix as well as higher sales.
And that, rather than the sheer size of the order book, is probably the most important thing to watch over the next few quarters.
Balance sheet: almost no debt, plenty of capital
The balance sheet is another quiet strength. As of March 2026, borrowings were only around Rs 17 crore, while reserves stood at about Rs 2,865 crore and investments at around Rs 1,606 crore.
Working capital remains favourable, although receivables are worth watching as the business grows. Management also expects recurring profits and dividends from the Ramagundam Fertilizer Project, while saying it is not currently looking to monetise its strategic investments.
The bigger question is what Engineers India does with its surplus cash. Management said other investment plans are under consideration, but there is currently no plan to distribute the entire cash reserve to shareholders.
The return ratio is quite healthy for a company carrying so little debt. Return on net worth (RoNW) was around 22%.
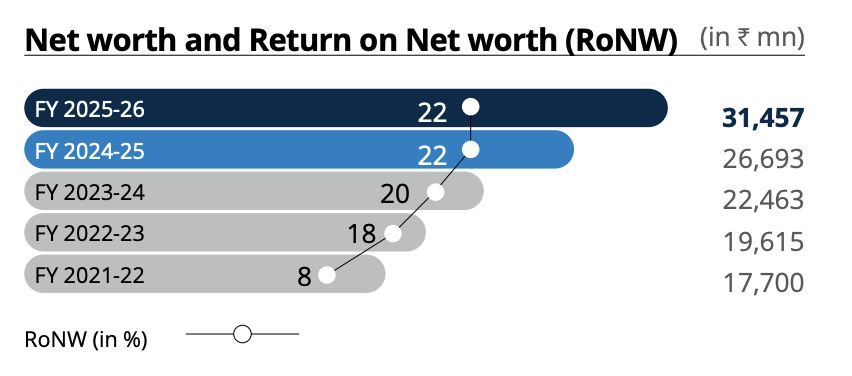
The improvement has not happened overnight. RoNW has risen from 8% in FY22 to 22% in FY26, while net worth increased from Rs 1,770 crore to Rs 3,146 crore over the same period.
Valuation is no longer an afterthought
At Rs 278, Engineers India is no longer the sort of stock where the valuation can be ignored. It trades at roughly 20 times earnings and close to 5 times book value, which means the market is already paying for some improvement in the business.
That does not necessarily make the stock expensive. It does, however, change the question an investor has to ask. The story now has to move from “what could happen?” to “how much of it is already in the price?”
The answer will depend largely on the shift towards consultancy. If the company can keep consultancy at around 55% or more of revenue and sustain segment margins of 24% to 25%, earnings have room to grow faster than revenue.
But at the current valuation, that improvement cannot remain merely a possibility. The market has already noticed the better margins and the changing business mix, so the next phase of the story will have to be delivered through actual earnings growth.
The 1.8% dividend yield is not enough to make the stock a dividend play, but it does provide a small additional return while investors wait for the earnings story to play out.
The risks are not difficult to see
The Middle East is the most obvious near-term concern. Existing projects remain on track, but new mega projects and tenders have slowed, although the company secured more than Rs 500 crore of Middle East business in Q1.
There is also a risk in assuming that every new sector will quickly become a large business. Nuclear, coal gasification and data centres are promising, but they are still opportunities at different stages rather than established earnings streams.
The stock’s recent rerating also leaves less room for disappointment. If order inflows or margins fall short of expectations, the correction could be sharper simply because the valuation is no longer particularly undemanding.
The next few quarters will tell the real story
Engineers India is not a conventional turnaround story. What is changing is the mix: consultancy is becoming a larger part of the business, margins are higher, and the company’s hydrocarbon expertise is being taken into areas such as nuclear, coal gasification and specialized infrastructure.
The numbers to watch are straightforward: consultancy’s share of revenue, consultancy margins, the Rs 8,000 crore FY27 order inflow target and at least 10% revenue growth. If these move in the right direction, Engineers India could gradually become a more profitable business without needing to become a completely different one.
Note: We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
Disclaimer:
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Manvi Aggarwal has been tracking the stock markets for nearly two decades. She spent about eight years as a financial analyst at a value-style fund, managing money for international investors. That’s where she honed her expertise in deep-dive research, looking beyond the obvious to spot value where others didn’t. Now, she brings that same sharp eye to uncovering overlooked and misunderstood investment opportunities in Indian equities. As a columnist for LiveMint and Equitymaster, she breaks down complex financial trends into actionable insights for investors.
Disclosure: The writer and her dependents do not hold the stocks discussed in this article. The website managers, its employee(s) and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.