



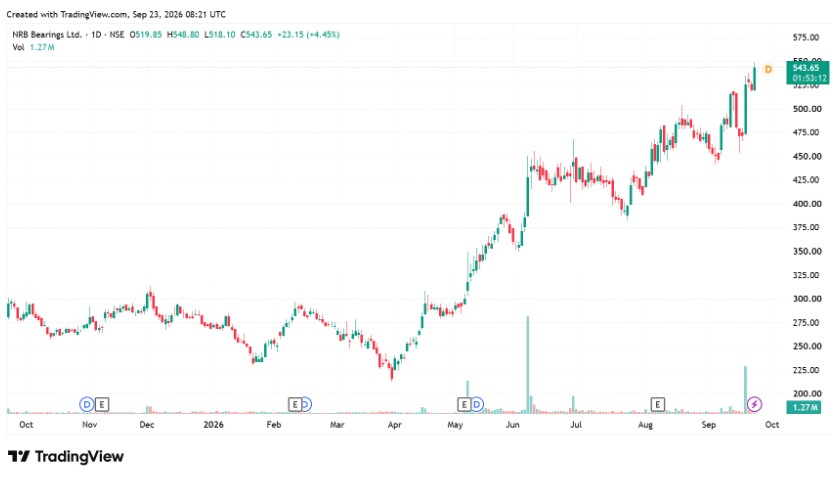
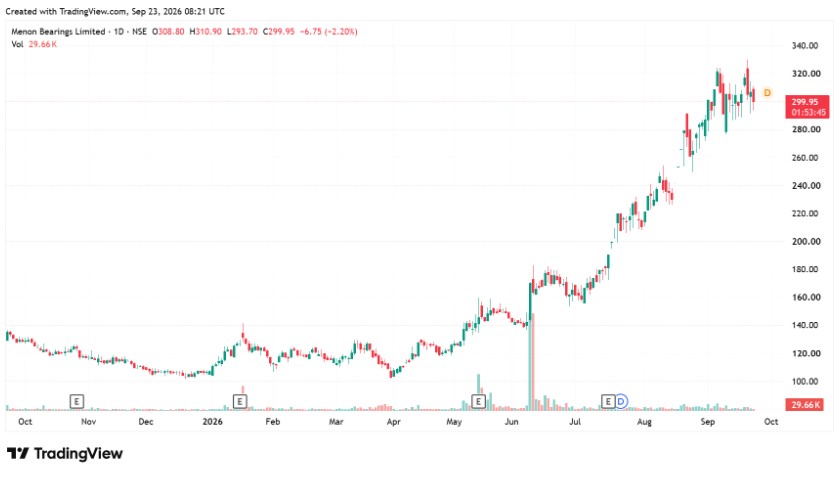
Two bearing stocks have surged up to 150% to date in 2026. There are multiple reasons behind the move, but one key aspect is defence and aerospace. Defence equipment may look very different from a car, but it has one component in common: bearings. Small and often unnoticed, bearings help critical systems move, rotate and operate with precision.
A bearing reduces friction between moving parts while supporting the loads placed on them. In a car, it helps wheels and other mechanical systems rotate smoothly. Traditionally, the automotive sector has been the largest end market for Indian bearing manufacturers.
However, defence and aerospace are opening up a new growth opportunity for bearing manufacturers as India expands its domestic defence production and aerospace manufacturing capabilities. Bearings are used in aircraft engines, helicopter rotors, landing systems, missiles, radars and other equipment.
Against this backdrop, this article looks at two bearing companies.
#1 NRB Bearings: Expanding from automotive into aerospace and defence
NRB Bearings is an engineering company that designs, manufactures and supplies high-precision ball and roller bearings, as well as customized micro-precision friction management solutions. It produces over 4,000 distinct product part numbers.
Revenue Engine: Why the Core 2-Wheeler Business Still Dominates
Needle Roller Bushes & Cages is the foundational product line and accounts for 53% of turnover. NRB is the largest producer of rocker arm bearings for the two-wheeler industry and is actively expanding these applications into four-wheeler passenger cars globally. Ball and roller bearings account for around 29% of revenue.
Ball and roller bearings include tapered roller bearings, spherical roller bearings, cylindrical roller bearings, thrust bearings, and wide inner ring bearings. Precision Automotive and Engineering Components contributes another 18% of revenue.
Within this, NRB provides custom-engineered components including planet pins, custom shafts, housings, unitized thrust bearings, and one-way clutches. NRB has positioned Aerospace and Defence as the premier vector among its six strategic growth initiatives.
Inorganic Growth: The ₹37.5 Crore Mahant Tool Acquisition
To enter the aerospace market without the multi-year lead time and lengthy OEM certification process, NRB adopted an inorganic growth strategy. In January 2026, the company acquired Bengaluru-based Mahant Tool Room, a specialized sole proprietorship in aerospace precision machining.
Management has proposed a ₹37.5 crore investment in Mahant Tool to scale production facilities for defence, aviation, and aerospace components. The acquisition pairs Mahant Tool’s pre-certified operational platform with NRB’s computer design technology and global delivery network to build those components at a much larger scale and sell them worldwide.
Securing the Sukhoi-30 & FY31 Defence Targets
Furthermore, NRB supplies bearings and custom components for defence vehicles, armored gun carriers, tanks, and heavy defence launch equipment. It is also an accredited supplier for US and French defence heavy launch equipment. It secured a production order to manufacture plain spherical bearings for the Sukhoi-30 fighter jet developed by Hindustan Aeronautics Limited.
Management claims that fewer than 5 companies globally possess the technological capability to design and produce this specific type of bearing. The company’s defence order book stands at ₹50 crore as of 30 June 2026. Management targets ₹300 crore in revenue from the aerospace segment by FY31, with a profitability contribution of ₹90 crore and a high 30% profit margin.
Management views the initial defence win as similar to its previous successes in luxury automotive platforms, such as winning initial transmission orders for BMW and Mercedes, which later expanded to every model line. Similarly, winning the initial defence platform could drive more orders and production volumes.
Financially, revenue grew 19.2% year-on-year to ₹370 crore. Operating profit surged 25.5% to ₹64 crore, while margin stood at 17%. Net profit increased by 15% to ₹38 crore. Management claims it is on track to reach ₹2,730 crore in revenue by FY31, up from ₹1,335 crore in FY26.
#2 Menon Bearings: Diversifying beyond automotive into defence and aerospace
Menon Bearings manufactures high-precision, heavy-duty engine bearings, bushes, thrust washers, aluminum casting components, and friction braking materials. Original Equipment Manufacturers contribute 48% of revenue, followed by exports (34%) and Aftermarket (8%).
Record Financials: Q1FY27 Net Profit Rises 67% as Margins Expand
The company is a key supplier to global manufacturers including John Deere, Cummins, Eaton, Honeywell, Allison Transmission, Magna, and Linamar. In Q1FY27, Menon Bearings delivered its highest-ever quarterly revenue, EBITDA, and net profit. Revenue grew 37.2% year-on-year to ₹94 crore.
EBITDA surged 56.8% to ₹22.4 crore while margins expanded 298 bps to 23.8%. Net profit grew 67.3% to ₹14.1 crore. Bi-Metal Division (Bearings, Bushes, Washers) accounted for 73.1% of revenue, followed by Alkop (Aluminum Die Casting) (23.8%) and Braking Systems Division (3.2%).
Defence Inroads: Supplying US Military & Honeywell Platforms
Menon Bearings also supplies high-precision engine bearings, bushes, and thrust washers that serve as secondary auto-ancillary components within defence vehicles. US-based Allison Transmission is an established customer to whom Menon Bearings supplies engine washers and bearings, including parts for US military vehicles.
In India, management plans to leverage its Tier-2 capabilities to participate in domestic “Make in India” defence opportunities. In aerospace, the company is developing precision components including airport lighting components and specialized wheel parts for Honeywell. The company has multiple growth triggers ahead.
Revenue Roadmap: Projecting ₹500 Crore on Strong Tier-1 RFQ Conversion
Looking ahead, Overall, export share is projected to grow from 34%-35% to 37% of net sales by FY27. Management considers its FY27 revenue target of ₹360 crore (FY26 revenue of ₹299 crore) to be conservative. It is aiming to achieve ₹500 crore in annual revenue within the next 2 to 3 years.
The company has established vendor profiles, signed Non-Disclosure Agreements and received Requests for Quotations (RFQ) from global automotive tier-1s including Magna and Linamar. This initiative is projected to unlock ₹65 crore to ₹75 crore in additional business across FY27 and FY28.
The company’s bi-metal and Alkop (aluminum) divisions have an active domestic RFQ pipeline of ₹75 crore. With a historical conversion rate of 75% to 80%, management expects this to generate new domestic revenue of ₹60 crore over the next two years. The Alkop division (through intermediaries) supplies parts for electric vehicles, including to Porsche and Tesla.
EV parts are targeted to scale to 8-10% of Alkop’s revenue by FY27. Moreover, the company has developed and tested 38 high-value components for a major customer. This holds an estimated annual revenue potential of ₹50 crore to ₹60 crore within two years. Total new component approvals hold a revenue potential of ₹55 crore.
Rail & EV Diversification: Supplying Luxury EVs and Vande Bharat Bogies
Following the setup of an imported testing dynamometer by September 2026, it will take about 1 year before full commercialization. Management projects initial railway revenues of ₹5-6 crore in year one. This is expected to increase to ₹25-30 crore annually within two years across passenger bogies, cargo bogies, Vande Bharat and metros.
Valuation Realities: Price-to-Sales Multiples and Unit Economics Compared
Menon Bearings has a higher Return on Equity (ROE) and Return on Capital Employed (ROCE) than NRB Bearings. Valuation-wise, both companies have recently re-rated and are trading at a premium to the industry and their respective 5-year historical medians.
Particulars | Price-to-Earnings Multiple (X) | Return Ratios | ||
| Company | 5Y Median | ROE (%) | ROCE (%) | |
| NRB Bearings | 35.2 | 22.4 | 15.6 | 18.4 |
| Menon Bearings | 38.6 | 25.7 | 22.3 | 25.5 |
| Industry | 30.8 | 14.0 | 15.9 | |
| Source: Screener.in (As of 23 September 2026) | ||||
The bearing industry is gradually moving beyond its traditional automotive base, with defence and aerospace adding new avenues for growth. NRB Bearings is building its aerospace and defence presence through precision components and its acquisition of Mahant Tool.
Meanwhile, Menon Bearings is expanding into defence, aerospace and other non-automotive applications. However, both companies have also seen their valuations re-rate, making future earnings growth and execution important factors to track. You can keep these companies on your watchlist.
Disclaimer
Note: Throughout this article, we relied on data from http://www.Screener.in and the companies’ investor presentations. We used an alternative, widely accepted source only when the data were unavailable.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, we strongly advise you to consult your advisor. This article is strictly for educational purposes only.
About the Author: Madhvendra has been deeply immersed in the equity markets for over seven years, combining his passion for investing with his expertise in financial writing. With a knack for simplifying complex concepts, he enjoys sharing his honest perspectives on startups, listed Indian companies, and macroeconomic trends.
A dedicated reader and storyteller, Madhvendra thrives on uncovering insights that inspire his audience to deepen their understanding of the financial world.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, their employees (s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities, or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives and resources, and only after consulting any independent advisors as necessary.