



As India’s manufacturing ecosystem deepens and new opportunities emerge across multiple industries, select companies are using their existing capabilities, customer relationships, and manufacturing expertise to diversify.
While most of the companies are diversifying by adding new products to an existing portfolio to capture the growth potential, there are a few companies that are developing new independent growth engines altogether.
For these companies, diversification is about gradual change in the earnings mix and long-term growth profile, without completely moving away from their core strengths.
Amber Enterprises India Ltd. and Texmaco Rail & Engineering Ltd. are two such examples, although their diversification journeys are quite different.
Amber is expanding from its traditional air-conditioner manufacturing business into a full-fledged electronics and components manufacturer, including businesses with applications beyond consumer durables.
Texmaco, meanwhile, is building on its long-standing railway manufacturing and engineering capabilities and expanding into a broader engineering platform by tapping defence and other emerging sector opportunities.
So, in this article, we will try to decode whether these newer ventures can turn from diversification initiatives into meaningful, scalable growth and profitability contributors for these two companies.
Join now
#1 Amber Enterprises: From AC Manufacturing to Electronics
From being a leading Refrigeration and Air conditioner (RAC) manufacturer, Amber Enterprises is gradually building a diversified electronics and engineering platform around its established consumer-durables business.
The shift is visible in the company’s Q1FY27 numbers, where the Electronics division grew much faster than its traditional Consumer Durables business and delivered a sharp improvement in operating profitability.
The Electronics division’s revenue rose 29% YoY to Rs 985 crore in Q1FY27 from Rs 766 crore a year earlier. Operating earnings before interest, tax, depreciation, and amortisation (EBITDA) more than doubled to Rs 107 crore from Rs 49 crore, registering a growth of 117% YoY.
Meanwhile, the Consumer Durables division, which is the core business of Amber, generated revenue of Rs 2,758 crore in Q1FY27 against Rs 2,560 crore in the corresponding quarter last fiscal year, logging only 8% YoY growth. Similarly, operating EBITDA increased to Rs 214 crore from Rs 192 crore, growing at 12% YoY.
Electronics Business Gains Scale
The improvement in Electronics is not limited to higher revenue. Amber has steadily moved towards businesses with higher value addition.
Management stated the division’s margins have improved from 2.8% in 2018 to 10.8% currently. The company is now focusing on adding more value-added businesses to sustain double-digit margins.
The division now covers three main areas — Electronics Manufacturing Services (EMS), Printed Circuit Board (PCB), and Industrials & Automation. The company has expanded its applications from consumer durables into areas such as wearables, telecom, automobiles, and defence.
The Core Strategy: Value Over Volume
Apart from organic growth, Amber is also scaling its electronics business via strategic acquisitions such as the acquisition of Unitronics and Power-One to add industrial automation and power-electronics capabilities. Management describes this as a strategy of balancing volume with value: applications such as consumer electronics and automotive provide scale, while industrial electronics and PCB add greater value, entry barriers and potentially better margins.
The management also stated that the company has plans to enter medical, defence and aerospace applications as well over the next three to four years.
This expansion is important because it reduces Amber’s dependence on the seasonal consumer-durables market while opening opportunities in several industrial and technology segments.
Large PCB Investments To Drive Next Phase
Amber is also putting significant capital behind the electronics expansion, which aligns with the government’s Electronics Component Manufacturing Scheme (ECMS) as well.
The company has announced around Rs 3,200 crore of investment for an HDI PCB facility at Jewar and about Rs 1,000 crore for a multi-layer PCB facility at Hosur. Management expects the Hosur facility to be operational during FY27, while trial production at Jewar is expected in about 18 months.
Amber has also received ECMS approvals for the Jewar, Hosur and Shogini, Pune projects. Construction is progressing at the facilities, while the Pune PCB-assembly facility is also being expanded.
Management estimates the current addressable market for its PCB, Printed Circuit Board Assembly (PCBA) and power-electronics businesses between $16 billion and $17 billion while projecting this opportunity to reach around $35 billion to $40 billion by FY30 even under a conservative scenario.
Smartphone Entry Adds Another Growth Avenue
Amber is also moving into mobile phone manufacturing through its collaboration with Oppo Mobiles India, covering OPPO, OnePlus and Realme. Trial production is expected by the end of this fiscal year, followed by commercial production in Q1FY28.
The move gives Amber exposure to a new product category and could also help reduce the seasonality of its RAC business.
High-growth expectations priced in?
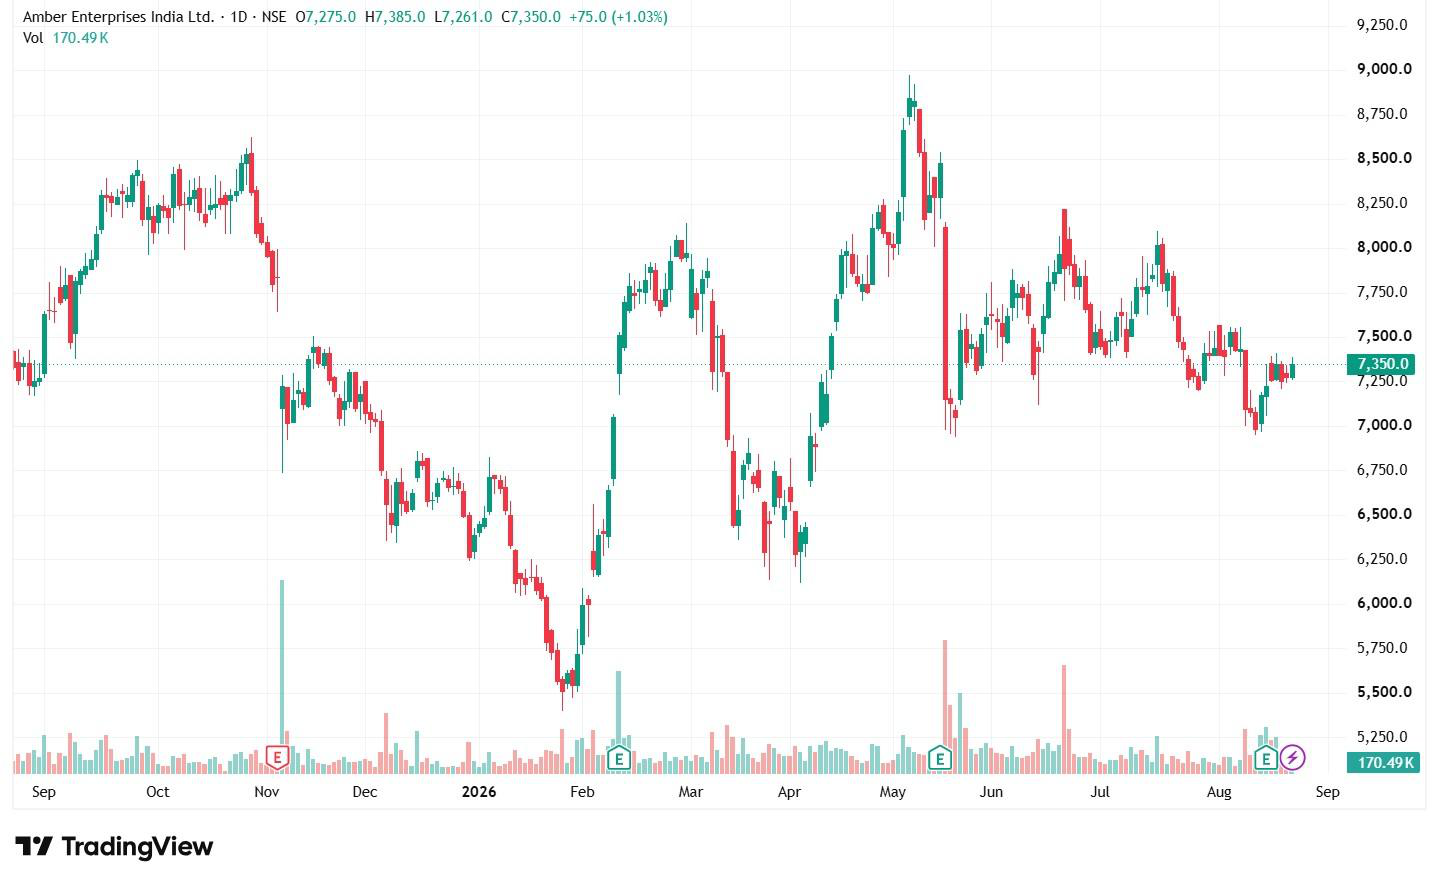
Amber Enterprises is trading at a premium to its industry peers, with a price-to-earnings (PE) of 125.5x against the industry median of 38.7x. The price-to-earnings-to-growth (PEG) ratio is at 16.8x compared to the industry median of 1.6x, suggesting that the market is already pricing in strong growth from its expanding electronics and other new businesses.
1-Year Share Price Chart of Amber Enterprise India Ltd.
#2 Texmaco Rail: From Wagons To A Broader Engineering Platform
Texmaco Rail is gradually moving beyond its traditional freight-car business to build a broader rail, infrastructure and engineering platform. While freight cars remain the core, the company is expanding into electrical infrastructure, signalling, passenger mobility, leasing, renewable energy and defence.
The management has envisioned the company’s topline to double within 2030 by adding new businesses, while keeping the core freight rolling stock stronger and more profitable.
Beyond Freight Cars
Texmaco Rail’s diversification is already visible in the revenue mix as Freight Cars accounted for 68.8% of standalone revenue, while Infra–Rail & Green Energy and Infra–Electrical contributed 8% and 23.2%, respectively.
Bright Power, the company’s electrical infrastructure business, reported 76.8% YoY revenue growth to Rs 175 crore in Q1FY27. Management stated Texmaco has spent several years building capabilities in electrical and electronics, including electrification, signalling and EPC, which were not part of its traditional business.
Even within Freight Cars, the customer mix is changing. Private-sector and export orders contributed to 96.4% of the segment’s order book in the April-June quarter 2026, compared with 21% at the end of FY25 and 79% at the end of FY26. Management said the shift is helping diversify the order book, improve visibility, and support margins.
Building A Wider Rail Platform
Texmaco is also moving towards supplying more of the railway value chain. Its Wabtec partnership covers air-brake equipment, predictive maintenance, condition monitoring and new wagon and bogie designs. The company has also entered passenger mobility through Saira Asia and has a presence in Vande Bharat interiors.
Scaling Leasing Operations
Leasing is another segment through which Texmaco is expanding beyond manufacturing. The company has strengthened its strategic partnership with Trinity Rail Global Inc. through the Touax Texmaco Railcar Leasing platform to build a large-scale railcar leasing business in India.
The platform currently has around 35 rakes operating under leasing, while the company is targeting to add another 100 rakes.
Order Book Shows A Broader Business Pipeline
Texmaco’s order book has expanded sharply, but the mix shows that the company’s transition beyond freight cars is still evolving. The consolidated order book stood at Rs 9,923 crore as of June 30, 2026, compared with Rs 5,408 crore at the end of FY26. In Q1FY27, Freight Cars accounted for 62.3% of the order book, while Infra–Electrical contributed 18.2%, Infra–Rail & Green Energy 9.9%, and other subsidiaries and JVs 9.6%.
Unpacking the Consolidated Order Pipeline
The comparison with Q4FY26 is particularly revealing. At the end of FY26, Freight Cars made up 38.5% of the consolidated order book, while Infra–Electrical accounted for 34.8%, Infra–Rail & Green Energy 9.8%, and other subsidiaries and JVs 16.9%. The higher freight-car share in Q1 reflects a sharp increase in freight-car orders alongside new wins in signalling, electrification and transmission infrastructure. The company secured more than Rs 5,200 crore of orders during Q1FY27, taking the overall order book to a multi-year execution pipeline.
The orderbook reflects that the diversification is not a straight-line shift away from wagons. Instead, Texmaco is growing its core freight-car franchise while building additional businesses around it. The key change is that the company now has a sizeable order pipeline spanning rolling stock, railway signalling, electrical infrastructure and transmission, giving it multiple avenues for growth rather than dependence on a single product category.
Defence And New-Age Opportunities
The next leg includes Kavach, renewable energy and defence. Texmaco recently signed an MoU with Belgium-based The Signalling Company NV to explore European Train Control System (ETCS) solutions, including contemplated Kavach development in India.
In defence, Texmaco has agreed to invest up to Rs 200 crore in its defence subsidiary alongside Vagus Def Tech & Aerospace Fund-1, with Texmaco retaining 70%. However, the business is still at an early stage and had no revenue as of Mar. 31, 2026.
The transition is therefore still unfolding. The key for investors will be whether these adjacent and newer businesses can scale sufficiently to create the second revenue pool management envisages by 2030, while the core freight-car business continues to improve its profitability.
Does The Discount Leave Room for Re-Rating?
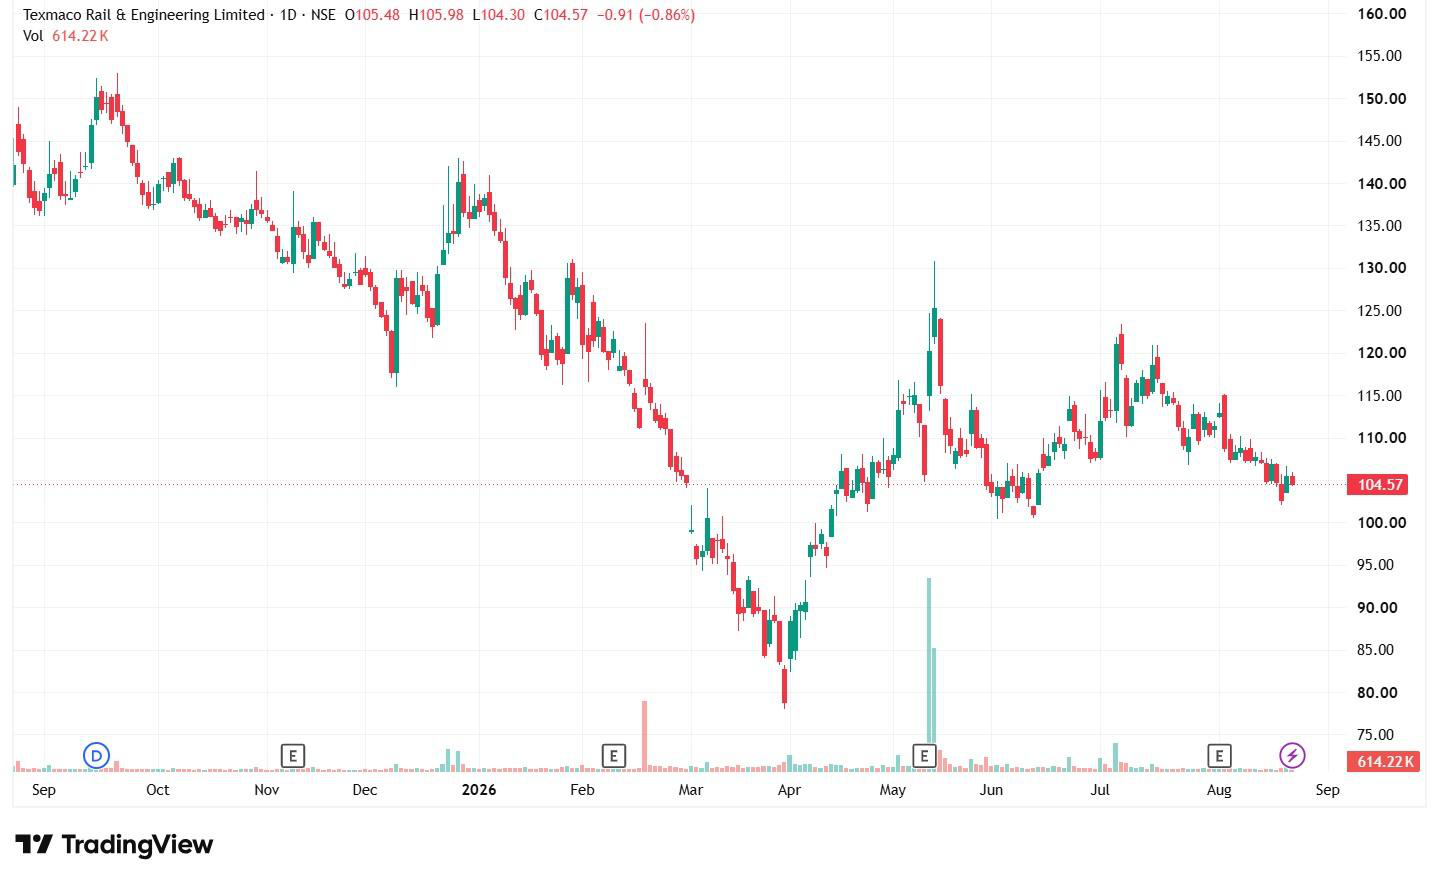
Texmaco Rail is currently trading at a PE of 19.6x, lower than the industry median of 58.6x. The PEG ratio of 0.20x is also lower than the industry median of 4x, suggesting that the stock is relatively cheaper than its peers.
1-Year Share Price Chart of Texmaco Rail & Engineering Ltd.
Two Different Paths To The Next Growth Cycle
Amber Enterprises and Texmaco Rail are pursuing the same broad strategy that is building new growth engines without abandoning their established businesses. However, they are at different stages of the transition cycle. For investors, the key will be monitoring the pace at which these new businesses scale, their contribution to revenue and margins, capital deployment and returns, and the ability to convert expansion plans into sustainable cash flows. For the same, you could add these stocks to your watchlist.
We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available have we used an alternate, but widely used and accepted source of information.
Disclaimer:
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
Maumita Mitra is a seasoned writer specializing in demystifying the world of investment for a broad audience. She has a keen eye for detail and a knack for explaining complex financial concepts in the simplest manner possible.
Disclosure: The writer and her dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities, or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives and resources, and only after consulting such independent advisors as may be necessary.