



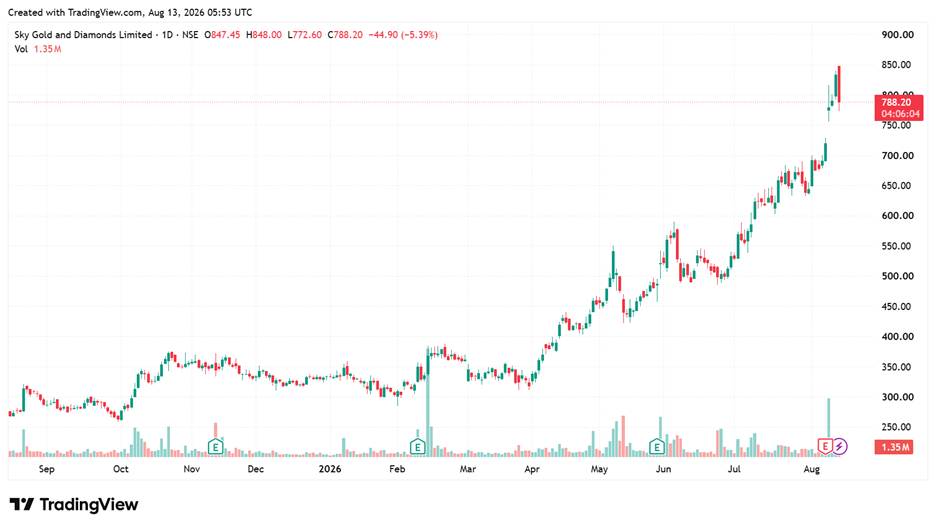
India’s jewellery market is entering a phase where the biggest opportunity may not sit only with the brands customers see in stores. It is also emerging behind the scenes, with B2B jewellery manufacturers playing a bigger role in the industry’s next leg of growth. This is reflected in the share price performance of Sky Gold and Diamonds, which has surged 200% over the past year.
Organised Retail Transition
The numbers explain why. India’s domestic jewellery retail market is projected to reach US$145 billion by FY28 (around ₹14 lakh crore), driven by rising disposable incomes, changing consumer preferences and favourable demographics. Within this, the organised jewellery market is expected to expand from US$19.2 billion in FY20 to US$82.6 billion (₹7.8 lakh crore) by FY28.
But a major shift is taking place in the market structure. Today, only 40% of B2C jewellery retail is organised, while the remaining 60% is still dominated by unorganised players. This gap is even wider in B2B jewellery manufacturing, where only 20% is organised, and 80% is unorganised.
Join now
This leaves a large market waiting to be formalised. It is expected that the B2B manufacturing sector will follow the same path of organisation as the B2C jewellery industry. Around 75% of the overall jewellery market is projected to be organised by FY30. For B2B jewellery players, this transition could be significant.
As retailers increasingly look for scale, consistency, design capabilities and reliable supply chains, organised manufacturers are better placed to capture this shift. Here are three B2B jewellery players that could benefit from this shift…
#1 Sky Gold & Diamonds: The Advanced Gold Manufacturing Pivot
Sky Gold & Diamonds Limited is an Indian jewellery design and manufacturing company. Beyond traditional retail, Sky Gold creates lightweight casting jewellery for B2B companies. It supplies to major national retail brands such as Malabar Gold, Joyalukkas, Kalyan Jewellers, and CaratLane.
Margin Expansion: Why Sky Gold’s EBITDA Doubled
The company’s revenue increased 77.9% year-over-year to ₹2,012.8 crore. EBITDA (earnings before interest, taxes, depreciation, and amortisation) doubled (+119.6%) to ₹156.7 crore, while margins expanded 149 bps to 7.8%. Consequently, operating leverage led to a 140.7% increase in net profit to ₹104.9 crore.
The company also achieved positive cash flow of ₹30 crore, compared with negative cash flow in FY26 and FY25. As gold prices have risen, customers have shifted to lower carat jewellery such as 18 carat, 14 carat, and 9 carat. This shift is already visible, with volumes for such jewellery increasing from 10.5% in Q4FY26 to 14%.
Strategic Shifts and Future Revenue Guidance
Sky Gold estimates revenue of ₹8,100 crore in FY27. EBITDA margin is expected to be between 7.0% and 7.5%, while PAT margin is estimated at 4.5% and 4.7%. In the long term, the company is targeting revenue of ₹19,000 crore with a margin of 5.25%. Management also aims to reach ₹1,000 crore in net profit.
Management aims to reduce its working capital days to 52 (from 60 in Q1FY27) and achieve net debt-free status. With strong all-round performance, the company aims to convert 20%+ of net profit into operating cash flow.
Expanding the Advanced Gold Manufacturing Model
Most of Sky Gold’s volume (83% in Q1FY27) currently comes from traditional manufacturing. In this, it creates jewellery using its own gold inventory. This is a high-working capital business. In the Advanced Gold model, the jeweller will supply the gold, and Sky Gold will simply bill for the job work.
Management aims to increase this business’s share to 15% of total gold volumes in FY27, 20% in FY28, FY29 (20-25%), and FY30 (30%). Because the Advanced Gold model bills solely for manufacturing, management estimates that including the value of the gold would yield an equivalent top-line projection of ₹27,000 crore by FY30.
#2 Goldiam’s International: The Lab Grown Diamond Leader
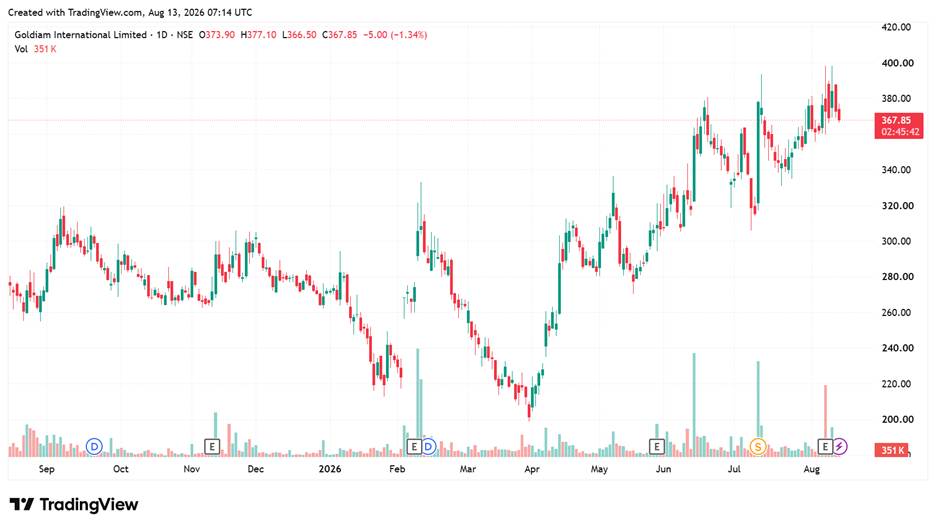
Goldiam International is a fully integrated manufacturer of luxury diamond jewellery. It is a key vendor partner for large corporate retailers primarily in the US and other regions like the Middle East, Australia, and Israel. It is also expanding into India through its retail brand, ORIGEM.
Pivot to Lab-Grown Diamonds and Tariff Mitigation Strategy
Goldiam has pivoted from a pure natural diamond supplier to a major producer of lab-grown diamond jewellery (LGD). LGD jewellery exports reached 90.7% of its overall B2B export sales mix in Q1FY27, up from 87.8% in Q1FY26. It controls the entire value chain from diamond cultivation to design and export of finished jewellery.
The company also changed a part of its business model to avoid US tariffs. In September 2025, the company launched its hybrid casting model. Its subsidiary in the USA will create unfinished jewellery pieces from raw gold within the US.
These castings are then sent to India for final polishing and diamond setting. This makes the finished product a legally recognised US product of origin. This effectively shields the business from any import tariffs. Beyond the US, Goldiam now has 26 operational LGD brand ORIGEM stores. The business generated ₹8.2 crore in revenue and ₹5-6 crore in operating loss in Q1FY27.
Robust Financial Performance and Margin Expansion
Financially, the company’s total income increased 54% year-over-year to ₹363.7 crore. EBITDA increased 120.5% to ₹103.9 crore, and margin expanded 858 bps to 28.6%. Steady EBITDA margin (after tariff refunds) increased 400 bps to 24%. Net profit more than doubled (+120%) to ₹74 crore.
A shift towards higher caratage per jewellery piece in LGD, coupled with higher B2B realisations compared to natural diamonds, gives the company significantly higher margins. In Q1FY27, LGD realisation stood at $722 versus $495 for mined. The company’s order book stood at ₹225 crore as of June 30, 2026, which is planned to be completed within four months.
Expanding Retail Footprint and Long-Term Growth Runway
In addition to the 26 ORIGEM stores, the target is to open seven more stores soon. In the long term, management is targeting a 100-store milestone. Notably, top-performing ORIGEM stores are already generating monthly sales of ₹40-45 lakh. ORIGEM’s average transaction value stands around ₹70,000, which is significant.
Goldiam represents a play on the rise of LGDs and the subsequent market share gains. LGD has reached 40-60% penetration among large US corporate retailers. Goldiam’s market share with its largest US retail client (which generates wholesale purchases of $2 billion to $2.5 billion) is still less than 2%. This leaves significant room to triple or quadruple sales with existing partners.
#3 Shringar House of Mangalsutra: The Mangalsutra Manufacturer
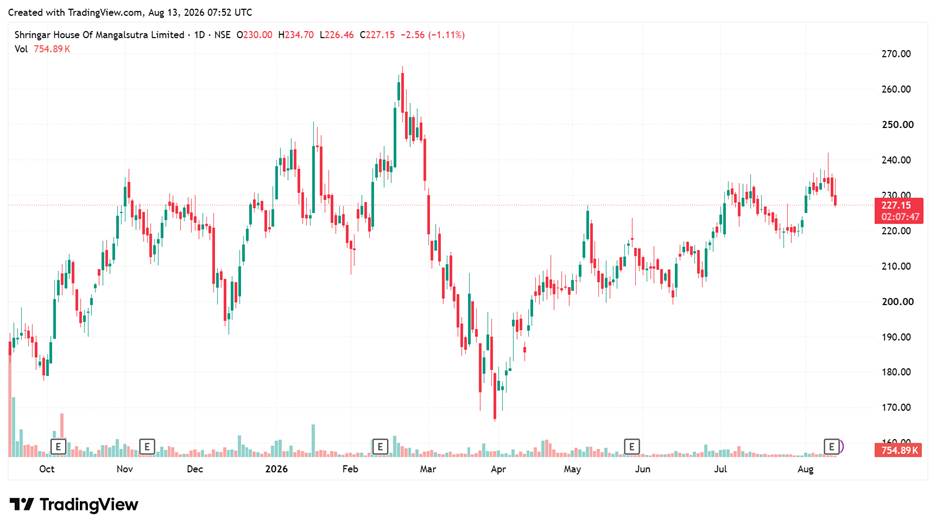
Shringar House of Mangalsutra is a well-known Indian B2B jewellery manufacturing company. The company designs, manufactures, and distributes mangalsutras and bridal jewellery. It has 1,333 corporate and unorganised retail clients. The Mangalsutra segment is the core business and has expanded into the Bridal Jewellery segment in Q4FY26.
Business Model Pivot and Retailer Partnerships
The company has long-term partnerships with major retail jewellers such as Joyalukkas, Tanishq, Reliance Retail, Kalyan Jewellers, and Malabar Gold. Job work (like the Sky Gold Advanced Gold model) accounts for 30% of volume, whereas the sales model accounts for 70% of transactions.
In the sales model, Shringar utilises its own gold inventory, resulting in 2-3x higher profits due to the company’s direct capital investment. To strengthen working capital, Shringar is consciously shifting from unorganised players to organised corporate retailers. These clients offer payment cycles of 12-15 days, which helps ease working capital pressure.
This shift is already underway as organised corporate clients now account for 49% of revenue, up from 30% in FY23. The company has recently expanded in-house production capacity to 4,000 kgs from 2,500 kgs. This aims to meet rising demand across Tier-2 to Tier-4 geographies.
Shringar’s Shift to Organised Clients Stabilises Margins
The company has reported strong financial growth. Revenue increased 64.9% year-over-year to ₹548.5 crore in Q1FY27, as it sold 5.6% higher quantity. However, EBITDA grew more slowly by 18.7% to ₹48.9 crore, while margin fell 350 bps to 8.9%. Net profit increased 19.3% to ₹34 crore.
Long-Term Growth Outlook and Strategy
Looking ahead, management aims to report 30% CAGR value growth over the next two to three years. Unlike Sky Gold, which is gradually moving towards a job-work model, Shringar is moving to a relatively higher-margin sales model. Management estimates that converting the job-work volume of ₹28 crore into direct sales will increase the revenue of that segment by ₹70-80 crore.
Evaluating Capital Efficiency: Premium Valuations vs Historical Medians
With stronger growth, Sky Gold has a stronger Return on Capital Employed (ROCE) and Return on Equity (ROE), followed by Shirngar and Goldiam. In terms of valuation, except for Shringar, which has been trading at a discount to the industry median in its short trading history, Sky Gold and Goldiam are trading at a premium to both their 5-year historical and the industry median.
| Peer Comparison (X) | ||||
| Price-to-Earnings Multiple | ||||
| Company | Company | 5Y Median | ROCE (%) | ROE (%) |
| Sky Gold | 36.2 | 33.8 | 27.0 | 29.2 |
| Shringar | 18.4 | NA | 26.8 | 26.3 |
| Goldiam | 26.5 | 22.8 | 23.9 | 18.5 |
| Industry | 20.3 | 20.9 | 20.2 | |
The B2B jewellery opportunity is becoming more interesting as the industry gets organised. Sky Gold is scaling its Advanced Gold model, Goldiam is using lab-grown diamonds and its hybrid casting model to tackle global demand, while Shringar is shifting towards organised retailers and a higher-margin sales model.
The strategies are different, but all three are positioning themselves for the same structural shift. Keep them on your watchlist to find out who ultimately becomes the winner.
Disclaimer
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation. Only in cases where the data were unavailable have we used an alternative, widely accepted, and widely used source of information.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
About the Author: Madhvendra has been deeply immersed in the equity markets for over seven years, combining his passion for investing with his expertise in financial writing. With a knack for simplifying complex concepts, he enjoys sharing his honest perspectives on startups, listed Indian companies, and macroeconomic trends.
A dedicated reader and storyteller, Madhvendra thrives on uncovering insights that inspire his audience to deepen their understanding of the financial world.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources, and only after consulting such independent advisors as may be necessary.