



Private sector banks have expanded their presence across India. They play a major role in mobilising deposits and extending credit. Their digital platforms have also made banking faster and more accessible. The sector now supports households, businesses and wider economic activity.
However, this growth has not translated into high market valuations for every bank. Concerns about margins, asset quality or future earnings can weigh on share prices. Some profitable banks may therefore trade at subdued valuations. A low valuation alone, however, does not make a stock attractive.
This article examines private sector banks where valuation and profitability present an interesting contrast. The aim is to identify banks that appear inexpensive but continue to generate reasonable returns from shareholders’ funds.
The selected stocks have a Price-to-Book (P/B) ratio below 1 and a double-digit Return on Equity (RoE). The P/B ratio is particularly relevant for banks because their balance sheets mainly contain financial assets and liabilities. RoE indicates how effectively a bank uses shareholders’ capital to earn profits. Together, these measures provide a useful starting point for assessing valuation alongside profitability.
Based on these parameters, two private sector banks make the cut. Let us examine them one by one.
#1 Karnataka Bank: Capitalizing on Retail and MSME Lending Expansion
Karnataka Bank is engaged in providing a wide range of banking & financial services involving retail, corporate banking and para-banking activities in addition to treasury and foreign exchange business.
Karnataka Bank trades at 0.9 times book value. This is above its five-year P/BV of 0.6 times, but below the peer median of 1.3 times. Return on Equity (RoE) stands at 10.4% and Return on Capital Employed (RoCE) at 6.1%. This suggests that the stock is not particularly cheap compared with its own history, although it remains discounted to peers.
Part of this discount may be linked to the gap between loan and deposit growth. Advances grew 17% in Q1FY27, while deposits increased 7%. The CASA ratio also declined sequentially. This can place pressure on funding costs when the bank is trying to expand higher-yielding retail lending.
A sustained rerating will therefore depend on stronger low-cost deposit growth and controlled slippages. The bank must also show that its improving RoE can continue as the loan book expands.
Growth Engine & FY27 Outlook: Digital Execution & Branch Network
Management expects advances to grow by 15-20% in FY27. Deposit growth is projected at 10-15%. The bank plans to open 31-32 branches during the year. One has opened, while another 12-13 are expected before the end of the first half.
Three MSME products have been launched, with two more under development. Other projects include digital gold loans, secured credit cards, digital fixed deposits and a new treasury platform.
Asset quality improved. The gross non-performing asset (NPA) ratio fell to 2.58% from 3.46% a year earlier. The net NPA ratio declined to 0.87% from 1.44%. Credit cost remained low at 0.03%. However, higher special mention accounts and a sequential increase in the cost-to-income ratio remain points to watch.
Gold-loan growth resumed in April after internal checks and board approval. The bank also raised about Rs 60 crore in fresh Foreign Currency Non-Resident deposits.
Margin Expansion & Asset Quality
Karnataka Bank reported a strong improvement in its June 2026 quarter. Aggregate business reached a record Rs 1.97 lakh crore, up 11% year-on-year (YoY).
Net interest income (NII), the bank’s core operating revenue, rose 24% to Rs 938.3 crore. Profit after tax increased 43% to Rs 418.95 crore. Net interest margin improved to 3.2% from 2.8% a year earlier. Lower funding costs and better-yielding loans supported earnings.
Retail, agriculture and micro, small and medium enterprise loans grew 12%. Housing, gold, vehicle and medium, small, and micro enterprises (MSME) loans contributed around Rs 1,980 crore to sequential growth. The bank also reduced its low-yield inter-bank participation certificate portfolio by Rs 243 crore.
Karnataka Bank Financial Performance
| Metric | Value |
| Current P/BV | 0.9x |
| RoE | 10.4% |
| Q1FY27 NII growth | 24% |
| Q1FY27 profit growth | 43% |
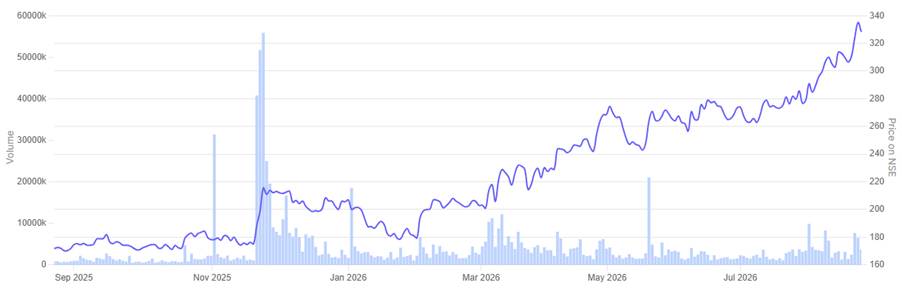
In the past year, the share price of Karnataka Bank surged 90.7%.
Karnataka Bank 1-Year Share Price Chart
#2 Jammu and Kashmir Bank: Rapid Advance Growth Offsets Net Profit Squeeze
Jammu & Kashmir Bank (J&K Bank), incorporated in Jammu & Kashmir, India, is a publicly held banking company engaged in providing a wide range of banking services including Retail Banking, Corporate Banking & Treasury Operations. The bank has also attracted investor interest. Mukul Agarwal acquired a 1.3% stake in J&K Bank during the June 2025 quarter.
The stock trades at 0.9 times book value. This is above its five-year P/BV of 0.8 times, but below the peer median of 1.3 times. RoE stands at 15.4%, while RoCE is 5.8%. The stock is therefore not unusually cheap compared with its own history. However, it continues to trade at a discount to peers.
The valuation reflects a trade-off. The bank is expanding its loan book and growing outside its core market. However, margin pressure, weaker profit conversion and reliance on costlier deposits remain concerns. Possible dilution from the proposed capital raise may also be limiting the rerating.
Sustaining Credit Growth Beyond Core Regional Dominance
Loan growth was led by selective corporate lending. Retail, agriculture and MSME loans still formed about two-thirds of the portfolio. Agriculture advances grew around 18%. Car loans rose more than 20% across the bank and over 30% outside its home market. Management expects overall credit growth of 18-20% in FY27.
Geographic expansion remains a key part of the plan. Rest of India operations contributed 26% of business, up from less than 20% a year earlier. The bank plans to add 15-20 branches annually in Jammu and Kashmir. It also targets 50-70 new branches across the rest of India over the next two years.
Supporting this expansion will require stable asset quality and adequate capital.
Asset quality continued to improve. Gross NPA declined to 2.37%, while net NPAs stood at 0.60%. The provision coverage ratio remained above 90%. A Rs 1,250 crore capital raise has been approved. Management is considering a larger issue, but further approvals are awaited.
Q1FY27 Performance: Business Growth vs Margin Squeeze
J&K Bank crossed Rs 3 lakh crore in total business during Q1 FY27. Advances grew 25% year-on-year to Rs 1.31 lakh crore. Deposits increased 17% to Rs 1.73 lakh crore. Total business rose more than 20%. The quarter also marked the bank’s first sequential deposit growth in six years.
Net interest income rose 2% to Rs 1,497 crore. Operating profit increased 4.5% to Rs 703 crore. Net profit, however, fell 12.5% to Rs 424.2 crore. Higher standard asset provisions and lower recoveries from written-off accounts weighed on earnings. Net interest margin narrowed to 3.28%.
J&K Bank Financial Performance
| Metric | Value |
| Current P/BV | 0.9x |
| RoE | 15.4% |
| Q1FY27 NII growth | 2% |
| Q1FY27 profit growth | – 12.5% |
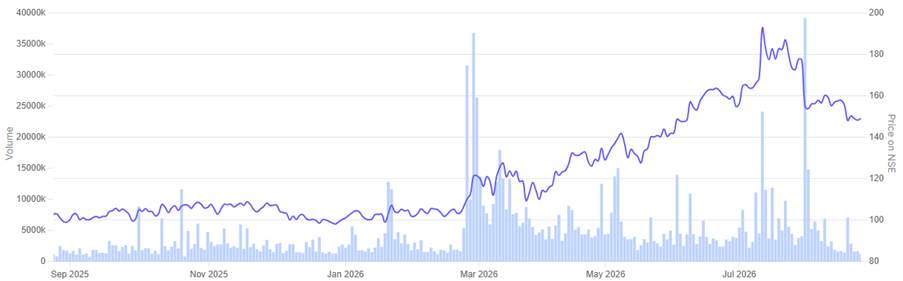
In the past year, the share price of Jammu & Kashmir Bank surged 45.1%.
Jammu & Kashmir Bank 1-Year Share Price Chart
Conclusion
The valuation gap is not as straightforward as it first appears. Karnataka Bank and J&K Bank trade below book value and report double-digit RoE. Yet their current P/BV multiples are already above their respective five-year averages. They are cheaper mainly in relation to peers, not their own trading history.
Karnataka Bank has reported stronger profits, wider margins and improving asset quality. The concern is whether it can sustain this performance while loans grow faster than deposits. J&K Bank is expanding at a quicker pace, particularly outside its home market. However, margin pressure, slower profit conversion and a possible capital raise explain part of its discount.
A lasting rerating will require more than rapid loan growth. Both banks must strengthen low-cost deposits and maintain lending discipline. They must also protect margins without weakening asset quality. If double-digit RoE continues without higher credit costs or significant dilution, the gap with peer valuations could narrow. Otherwise, the low P/BV may continue to reflect genuine execution risks.
Private Banks Trading Below Book Value with Double-Digit RoE
| Metric | Karnataka Bank | J&K Bank |
| 1QFY27 NII growth | 24% | 2% |
| 1QFY27 net profit growth | 43% | -12.5% |
| RoE | 10.4% | 15.4% |
| Current P/BV | 0.9x | 0.9x |
| Peer Median P/BV | 1.3x | 1.3x |
You can track how these are progressing by adding stocks to your watchlist.
Note: We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Ekta Sonecha Desai has a passion for writing and a deep interest in the equity markets. Combined with an analytical approach, she likes to deep dive into the world of companies, studying their performance, and uncovering insights that bring value to her readers.
Disclosure: The writer and her dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.