



Over the last two decades, cars have changed dramatically. Earlier, features such as air-conditioning, power steering, and basic comfort were enough to differentiate a vehicle. Today, even a mass-market car is packed with large screens, connected features, sunroofs, premium interiors, advanced safety systems, and more sophisticated drivetrains.
That creates a new growth lever for auto component makers: increasing content per vehicle. As vehicles become more feature-rich and technologically complex, suppliers that can move up the value chain can grow faster than the underlying auto market.
SJS Enterprises and Divgi TorqTransfer Systems offer two different ways to play this shift. SJS is increasing its content per vehicle through premium aesthetics, displays and new-generation products. Divgi, meanwhile, is moving deeper into the drivetrain through transfer cases, AWD systems and transmission technology.
The distinction matters for investors. SJS is trying to capture more value by supplying more and higher-value content, while Divgi is trying to capture a larger share of the vehicle’s value. The question is whether either strategy can translate rising content per vehicle into sustained earnings growth.
Join now
#1. SJS Enterprises: Betting on more content per vehicle
SJS Enterprises offers a direct play on the rise in content per vehicle. The company supplies aesthetic and functional components such as badges, chrome-plated parts, dials, overlays, decorative surfaces, and automotive displays.
At first glance, these may appear to be small-ticket components. But as vehicles become better equipped, they also require more components and higher-value content. Features such as illuminated logos, premium displays, backlit controls and integrated cockpit elements create additional opportunities for suppliers such as SJS.
This is already visible in the company’s kit value. SJS says the value of its content supplied per passenger vehicle has increased from around ₹1,200-1,500 to ₹3,500-5,000. Management is targeting a further 5-8x expansion in its addressable kit value as integrated cockpit assemblies scale up.
SJS Enterprise: Quarterly Financial Performance
| Period | Q1FY26 | Q2FY26 | Q3FY26 | Q4FY26 | Q1FY27 |
| Revenue (₹ crore) | 210 | 242 | 244 | 260 | 261 |
| YoY Revenue Growth (%) | 11.2 | 25.4 | 36.4 | 29.7 | 24.5 |
| Operating Margin (%) | 27.0 | 28.0 | 29.0 | 29.0 | 29.0 |
| Net Profit (₹ crore) | 35 | 43 | 45 | 49 | 74 |
Increasing Operational Efficiency
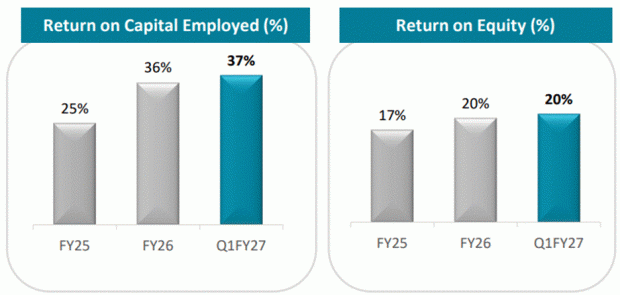
SJS’s financial performance suggests that the company is already benefiting from this higher-content strategy. Revenue growth accelerated from 11.2% YoY in Q1FY26 to 24.5% in Q1FY27, while operating margins remained close to 30%.
As per the management, Q1FY27 marked the 27th consecutive quarter in which SJS outperformed the underlying automotive industry.
The sharp increase in Q1FY27 net profit also calls for attention. Profit rose to ₹74 crore from ₹35 crore a year earlier, faster than revenue. The sharp rise in profitability can be explained by improving operational efficiency. Return on capital employed (ROCE) improved from 25% at the end of March 2025 to 37% in Q1FY27.
Capturing Higher Value Streams
To maintain the growth momentum, SJS is expanding into newer, higher-value products including premium automotive displays and optical products. In FY26, new-generation products accounted for around 24% of consolidated revenue.
The company also works with OEMs from the styling and design stage, giving it a chance to influence component choice early in the vehicle-development process. If SJS can source more content at this stage, it can increase its wallet share when the vehicle goes into mass production.
Scaling Global Footprints
SJS is also expanding its international business. Export revenue increased 60.5% in FY26 to ₹91.1 crore, accounting for 9.5% of revenue. Management is targeting exports to reach 14-15% of revenue by FY28.
The combination of rising domestic content per vehicle, new-generation products and exports could allow the company to grow faster than the underlying domestic auto market.
The key question is whether SJS can sustain this pace as its revenue base becomes larger and as newer product categories become a more meaningful part of the business.
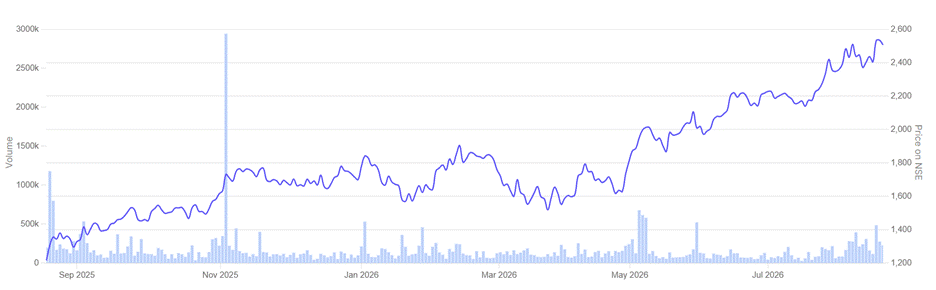
SJS Enterprise: 1-yr Stock Price Chart
Divgi TorqTransfer Systems: Moving deeper into drivetrain technology
Divgi TorqTransfer Systems offers a different way to play the rise in value per vehicle. While SJS is increasing its content through premium aesthetics and new-generation products, Divgi is moving deeper into the drivetrain.
The company supplies torque-transfer systems, 4WD transfer cases, EV transmissions and transmission components, and is working towards localising complete automatic transmission technology.
The distinction is important. Divgi is not simply trying to sell more components as vehicle production rises. It is attempting to move towards larger and more technically complex drivetrain systems, which can increase the value of content supplied per vehicle. Their strategy is showing up in financials.
Divgi TorqTransfer: Quarterly Financial Performance
| Period | Q1FY26 | Q2FY26 | Q3FY26 | Q4FY26 | Q1FY27 |
| Revenue (₹ crore) | 72 | 83 | 91 | 108 | 137 |
| YoY Revenue Growth (%) | 32.0 | 54.0 | 73.0 | 85.0 | 90.3 |
| Operating Margin (%) | 20.0 | 20.0 | 20.0 | 20.0 | 27.0 |
| Net Profit (₹ crore) | 9 | 11 | 12 | 15 | 25 |
Divgi’s growth has accelerated sharply since the beginning of FY26. Revenue increased 90.3% YoY to ₹137 crore in Q1FY27, while operating margin expanded to 27% from 20% a year earlier. Net profit rose nearly 178% YoY to ₹25 crore.
Transfer cases are driving the near-term growth
The major contributor to Divgi’s current growth is its transfer-case business. Transfer cases are drivetrain components that distribute engine power between the front and rear axles, enabling four-wheel drive or all-wheel drive.
The company has secured transfer-case programmes for pickup trucks exported by Mahindra & Mahindra and Tata Motors to Indonesia. Together, the two programmes cover around 70,000 vehicles, with approximately 35,000 units each.
Divgi has also secured a five-year AWD system programme from an Indian OEM covering around 6,000 vehicles annually, with production scheduled to begin in Q1FY28.
Automatic transmissions could be the next growth opportunity
The bigger opportunity, however, lies in automatic transmission localisation. India remains heavily reliant on imported automatic transmissions from Japan, Korea, and Europe. Divgi is attempting to address this gap by developing indigenous automatic transmission technology for domestic OEMs, including Tata Motors and Mahindra & Mahindra.
The company has developed automatic transmission technology demonstrators for these OEMs. Management estimates that localisation could generate more than 10% cost savings on transmission units priced at over ₹1 lakh.
EV transmissions provide another opportunity
Divgi is also developing dedicated transmission solutions for electric vehicles. As vehicle architectures evolve, the drivetrain itself is changing, creating a new opportunity for suppliers with transmission and torque-transfer expertise.
The company is developing its Sigma architecture to support EV drivetrain applications and increase utilisation of its drivetrain manufacturing capabilities.
Expanding Export Opportunity
Exports provide another potential growth lever. Divgi’s export contribution stood at around 16% of revenue in Q1FY27, and management is targeting 20–25% over the medium term.
The opportunity, therefore, is significant. But the execution risk is also real. For investors, it is important to track whether transmission demonstrators convert into firm OEM orders and serial production, how quickly new transfer-case programmes ramp up, and whether the new capacity can achieve sufficiently high utilisation.
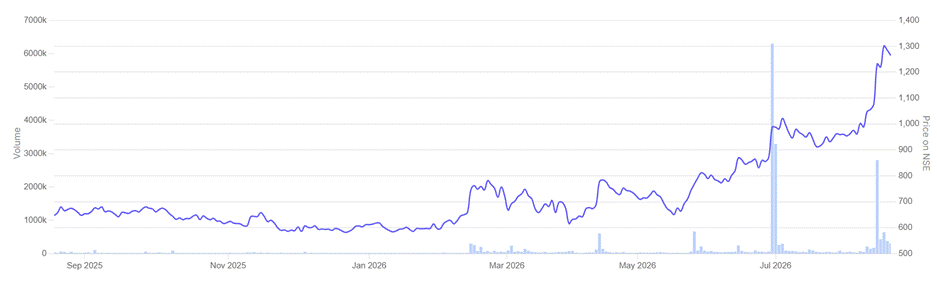
Divgi TorqTransfer: 1-yr Stock Price Chart
How is the market valuing the two opportunities?
The market is already placing a premium on both companies, but the nature of that premium is different.
Valuation Trend
| Metrics | Trailing P/E | 5-yr Median PE |
| SJS Enterprise | 41.5 | 28.6 |
| Divgi TorqTransfer | 61.4 | 57.7 |
SJS is trading at 41.5 times trailing earnings, well above its five-year median P/E of 28.6 times. The premium suggests that investors are already assigning significant value to the company’s premiumisation strategy, rising kit value, new-generation products and export expansion.
Divgi trades at an even higher 61.4 times trailing earnings, but the premium to its own historical valuation is much smaller. Its five-year median P/E is 57.7 times. It seems the market is waiting for more commercial success around its new projects before assigning a higher valuation.
The comparison, therefore, is not simply about which stock is cheaper. SJS carries a much larger premium to its own historical valuation, while Divgi carries a much higher absolute multiple but has delivered significantly faster recent earnings growth.
Value Creation Beyond Volume Growth
The opportunity in auto components is shifting from how many vehicles are sold to how much value suppliers capture from each vehicle. SJS and Divgi represent two distinct approaches to this shift, but neither is a straightforward volume play.
SJS is pursuing this through a wider and richer content portfolio, with kit values, new-generation products and exports providing multiple levers. Divgi is taking a more concentrated bet on drivetrain technology, where successful commercialisation can materially increase its wallet share per vehicle.
That makes the two stocks different bets: SJS offers greater visibility on the content-expansion story, while Divgi offers greater upside if its drivetrain pipeline converts into scaled programmes. Add these stocks to your watchlist and monitor how they execute their growth plans.
Note: We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Deepan Datta has spent over a decade studying stocks and mutual funds. His passion is to uncover interesting stories in the financial markets and share them through his writings with investors at large. He is focused on delivering clear, easy to understand and research-backed insights. Deepan began his career as a Research Associate at S&P Global, where he developed a strong foundation in financial research and data analysis.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, their employees (s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.