



Indian equity markets have witnessed a sharp sell-off over the past month, with midcap and smallcap stocks bearing the brunt. According to Financial Express, the Nifty Midcap 150 and Nifty Smallcap 250 declined 10.13% and 10.60%, respectively, over the one-month period ending October 23. In comparison, the Nifty 50 fell 4.5%. Foreign investor selling, elevated crude oil prices and concerns over corporate earnings have weighed on market sentiment.
However, not every falling stock represents a weakening business. Several companies have reported strong September-quarter earnings despite substantial corrections in their share prices. Some are also trading below their historical valuations.
To identify such opportunities, we screened companies with market capitalisation above Rs 1,000 crore, trading more than 20% below their 52-week highs and at P/E ratios below their five-year historical levels. The screen considered companies that had announced their Q2FY27 results as of October 26, reporting revenue growth above 10% and profit growth exceeding 15% year-on-year (YoY).
We further prioritised companies with strong capital efficiency, consistent three-year sales and profit growth, low debt, positive operating cash flow and zero promoter pledging, using sector-appropriate measures where necessary. We have excluded any insurance companies from the list because their earnings depend on underwriting profitability, claims and investment income. Comparing its current P/E with historical P/E alone can be misleading.
Eight companies initially qualified. However, only four had at least five complete years of listed trading history, allowing for a meaningful comparison with historical valuations.
These four stocks have corrected between 22% and 43% from their 52-week highs and are trading at discounts of approximately 8% to 33% to their historical P/E levels.
But do these corrections offer opportunities for long-term investors, or are the lower valuations signalling risks that strong quarterly earnings may be masking? Let’s examine.
#1 Nestlé India: 24% Below Its High Despite 36% Profit Growth
Nestlé India is a leading packaged food and beverage company, with brands spanning noodles, confectionery, coffee and nutrition. Its growth strategy focuses on expanding rural distribution, increasing household penetration and introducing premium products.
According to its August 2026 management call transcript, the company invested over Rs 6,400 crore in manufacturing capacity over five years. Recent additions include a Maggi production line costing over Rs 170 crore and a Munch line involving approximately Rs 225 crore.
Maggi Expands Rural Reach, KitKat Gains Share, but Stock Remains Under Pressure
In Q2FY27, sales rose 20.5% YoY to Rs 6,782.2 crore, while standalone net profit increased 36.3% to Rs 1,026.8 crore. Double-digit volume growth supported earnings despite advertising expenditure rising 46%.
KitKat gained market share, while Maggi expanded its rural reach. Premium coffee and quick commerce supported growth. Exports also expanded, with new product launches in Canada and West Africa.
Yet, the stock has corrected 24.4% from its 52-week high. Its P/E of 56.1 is 28% below its five-year median of 77.9. Return on Capital Employed (ROCE) stands at 84.1%, while Return on Equity (ROE) is 73.2%.
However, the stock still trades above the peer P/E of 36.8. Volatile cocoa prices, elevated input costs and continued advertising investments remain key risks.
Nestlé India Financial Performance
| Metric | Q2FY27 |
| Sales | Rs 6,782.2 crore |
| Sales growth | 20.5% YoY |
| Net profit | Rs 1,026.8 crore |
| Profit growth | 36.3% YoY |
Source: Nestlé India Q2FY27 Financial Results
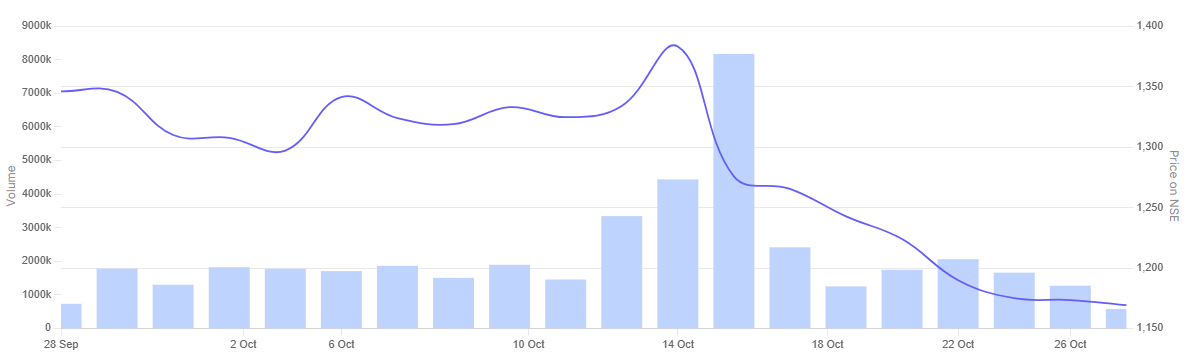
In the past month, the share price of Nestle India is down 12.9%.
Nestle India 1-Month Share Price Chart
Source: Screener.in
#2 Polycab India: Share Price Down 24% Despite 43% Profit Growth
Polycab India is a leading manufacturer of wires, cables and electrical goods. Demand from infrastructure, power distribution and private-sector investment continues to support its core business. Solar products are also emerging as an important growth driver.
According to its October earnings call, the company spent Rs 609 crore on capacity expansion and related investments during H1FY27. Its Project Spring strategy remains on track, with growth and margin targets extending to FY30.
Solar Business Doubles as Cable Demand Holds Firm
In Q2FY27, consolidated revenue surged 53% YoY to Rs 9,898.9 crore, while net profit rose 43% to Rs 990 crore.
Wires and cables revenue grew 47%, supported by domestic demand. However, underlying volume growth was in the mid-to-high single digits, with higher copper-linked realisations also contributing.
The fast-moving electrical goods (FMEG) segment recorded 124% revenue growth, led by solar products. Its earnings before interest and taxes (EBIT) margin reached a record 10.1%.
Despite these results, the stock has corrected 23.6% from its 52-week high. Its current P/E of 37 is 19.1% below its five-year median of 45.7. ROCE stands at 33.2%, while ROE is 23%.
However, Polycab still trades above the peer P/E of 24.4. Rising competition, copper-price volatility and uncertainty surrounding the ongoing insolvency dispute remain key risks.
Polycab India Financial Performance
| Metric | Q2FY27 |
| Revenue | Rs 9,898.9 crore |
| Revenue growth | 53% YoY |
| Net profit | Rs 990 crore |
| Profit growth | 43% YoY |
Source: Polycab India Q2FY27 Earnings Presentation
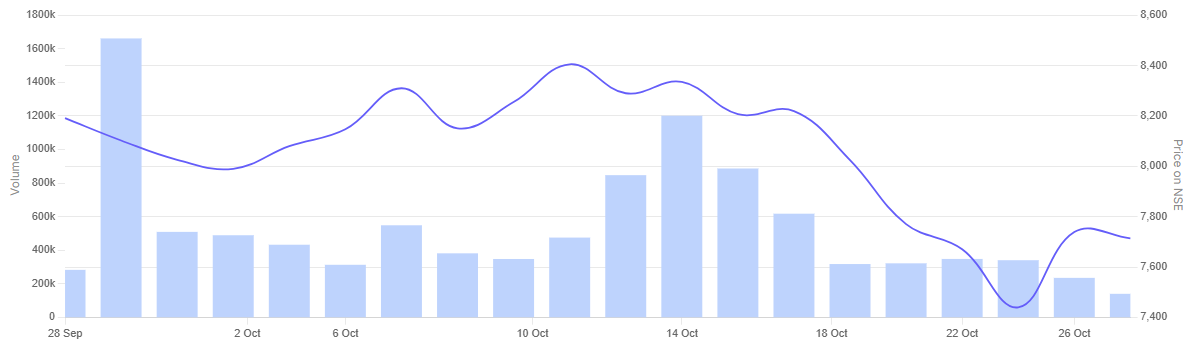
In the past month, the share price of Polycab India is down 5.8%.
Polycab India 1-Month Share Price Chart
Source: Screener.in
#3 Swaraj Engines: Share Price Down 22% Despite Record Quarterly Profit
Swaraj Engines manufactures diesel engines and components for Mahindra & Mahindra‘s Swaraj tractors. Its performance is closely linked to tractor demand, which depends on monsoon conditions, farm incomes and agricultural mechanisation.
According to its FY26 annual report, the company is expanding annual manufacturing capacity from 1.95 lakh to 2.40 lakh engines. The expansion is progressing, although a commissioning date has not been disclosed.
The company sold a record 2 lakh engines in FY26, supported by strong tractor demand. It is also developing higher-horsepower engines and upgrading existing models to meet evolving emission requirements.
Engine Sales Rise 20%, but Share Price Remains Below Its Peak
In Q2FY27, revenue increased 26% YoY to Rs 635.2 crore, while net profit rose 21.9% to a record Rs 60.6 crore.
Engine sales grew 19.6% to 61,216 units, reflecting sustained demand from its principal customer.
Despite these results, the stock has corrected 21.9% from its 52-week high. Its P/E of 19.2 is 9.4% below its five-year median of 21.2 and below the peer P/E of 37.8. ROCE stands at 58.4%, while ROE is 43.6%.
However, dependence on a single customer remains a significant risk. Any slowdown in Swaraj tractor production or adverse monsoon conditions could affect engine demand.
Swaraj Engines Financial Performance
| Metric | Q2FY27 |
| Revenue | Rs 635.2 crore |
| Revenue growth | 26% YoY |
| Net profit | Rs 60.6 crore |
| Profit growth | 21.9% YoY |
Source: Swaraj Engines Q2FY27 Financial Results
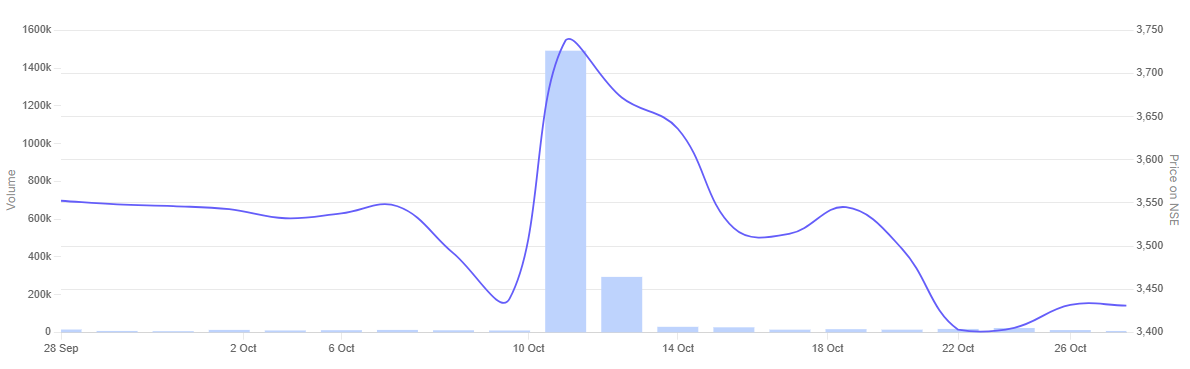
In the past month, the share price of Swaraj Engines is down 14.9%.
Swaraj Engines 1-Month Share Price Chart
Source: Screener.in
#4 Tinna Rubber and Infrastructure: Share Price Down 43% Despite 45% Profit Growth
Tinna Rubber and Infrastructure recycles end-of-life tyres into rubber products used in road construction, tyre manufacturing and industrial applications. Growing demand for recycled materials and higher rubber content in roads supports its expansion plans.
According to its October 2026 investor presentation, the company plans to invest up to Rs 250 crore over three years in a 40-acre integrated recycling facility in Andhra Pradesh. It has also established a subsidiary in Chile to strengthen international tyre sourcing.
Tyre Processing Jumps 30% as New Capacity Nears Commissioning
Tyre processing volumes in India increased 30% YoY to 86,000 tonnes in H1FY27. An additional 3,500-tonne annual micronised rubber powder capacity is expected to be commissioned by Q3FY27.
In Q2FY27, consolidated revenue grew 31% YoY to Rs 156.6 crore, while net profit increased 44.8% to Rs 17 crore.
Despite stronger earnings, the stock has corrected 43% from its 52-week high. Its P/E of 20.3 is 32.3% below its five-year median of 30. ROCE stands at 22.5%, while ROE is 22.1%.
However, the valuation remains above the peer P/E of 17.2. Start-up costs at overseas operations and the unresolved Panipat plant land dispute remain key concerns.
Tinna Rubber and Infrastructure Financial Performance
| Metric | Q2FY27 |
| Revenue | Rs 156.6 crore |
| Revenue growth | 31% YoY |
| Net profit | Rs 17 crore |
| Profit growth | 44.8% YoY |
Source: Tinna Rubber Q2FY27 Investor Presentation
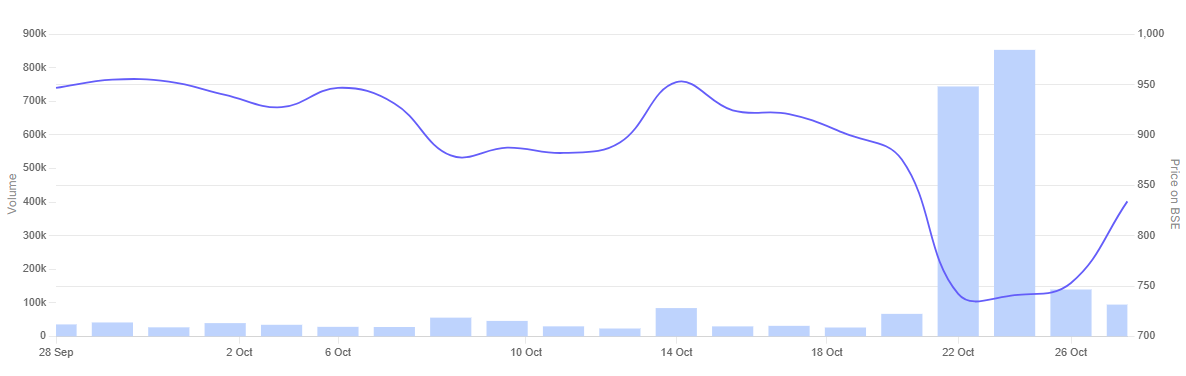
In the past month, the share price of Tinna Rubber and Infrastructure is down 13.7%.
Tinna Rubber and Infrastructure 1-Month Share Price Chart
Source: Screener.in
Conclusion
The sharp corrections in these four stocks show that strong quarterly earnings do not always translate into higher share prices. While all four have reported healthy revenue and profit growth, their valuations remain below historical levels. However, a discount to past valuations does not necessarily make a stock inexpensive.
The coming quarters will be important in determining whether earnings growth can be sustained. Investors should assess demand trends, operating margins, cash flows and sector-specific risks. Valuations also need to be compared with industry peers, as some stocks continue to command a premium despite their corrections.
Ultimately, a falling share price backed by strong earnings deserves attention, but not automatic investment. The key is whether the correction reflects temporary market sentiment or a more lasting change in business prospects.
Four Stocks Down Over 20% Despite Strong Q2 Earnings
| Metric | Nestlé | Polycab | Swaraj Engines | Tinna Rubber |
| Fall from 52W high | 24.4% | 23.6% | 21.9% | 43.0% |
| Q2 revenue growth | 20.5% | 53% | 26% | 31% |
| Q2 profit growth | 36.3% | 43% | 21.9% | 44.8% |
| Current P/E | 56.1 | 37.0 | 19.2 | 20.3 |
| 5Y median P/E | 77.9 | 45.7 | 21.2 | 30.0 |
Source: Nestlé India Q2FY27 Financial Results, Polycab India Q2FY27 Earnings Presentation, Swaraj Engines Q2FY27 Financial Results, Tinna Rubber Q2FY27 Investor Presentation and Screener data for Nestle India, Polycab India, Swaraj Engines and Tinna Rubber.
You can track how these are progressing by adding stocks to your watchlist.
Disclaimer
Note: We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Ekta Sonecha Desai has a passion for writing and a deep interest in the equity markets. Combined with an analytical approach, she likes to deep dive into the world of companies, studying their performance, and uncovering insights that bring value to her readers.
Disclosure: The writer and her dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.