



Customer preferences within India’s Quick Service Restaurants (QSR) are evolving rapidly. Driven by diversifying palates and expanding household dining-out budgets, many QSR companies are showing good growth momentum and improvement in margins. This analysis examines the performance of Jubilant FoodWorks, Devyani International, and Westlife Foodworld.
These three major QSR companies have built strong brand recognition along with massive depth of store penetration. This allows them to grab a greater chunk of the total QSR spend and provides a bigger runway for future growth as new meal options are launched to attract customers. With the increase in options for customers, it has become more important for companies to ensure that they provide efficient delivery options, good store ambience, and have a strong digital presence.
These three QSR companies are charting their own course in improving their business.
Jubilant FoodWorks, which manages a master franchise network for brands like Domino’s Pizza, Popeyes, Dunkin’ and others, has been able to leverage its massive store base of over 2,000 stores and an exceptional delivery network to build a strong presence in this niche. Its complete control over the supply chain allows cost control and ingredient consistency. The company also operates in international regions like Bangladesh, Sri Lanka, Nepal and others. The ability to have its own digital and delivery network reduces dependence on third-party aggregators and increases customer loyalty via its own platform.
Devyani International has over 2,250 stores. It has master franchise rights for chains like KFC and Pizza Hut. It operates in India as well as Thailand, Nigeria, and Nepal. It also has its own homegrown brands like Vaango and Biryani By Kilo. Devyani International is able to use its diverse categories, including fried chicken, pizza, premium coffee, and other regional food formats, to deliver strong growth.
Westlife Foodworld is an exclusive master franchise for McDonald’s in Western and Southern India. It has an expansive network of 482 restaurants across 79 cities. Westlife has built its omnichannel strategy of dine-in, drive-thrus, and a robust digital app. The menu is focused on providing value to customers at different price points.
The advanced digital platform, including self-ordering kiosks and its app, has captured 74% of the total system sales. This has significantly improved the efficiency of the overall system. The supply chain is highly localized, which allows for cost and quality control and limits any headwinds due to global freight disruptions.
Recent quarterly performance by these three QSR companies:
| Jubilant FoodWorks | Devyani International | Westlife Foodworld | |
| Revenue (Rs crore) | 2,569.65 | 1,580.52 | 735.64 |
| YoY Revenue growth | 13.66% | 16.47% | 11.86% |
| Operating margin | 19.48% | 16.10% | 12.86% |
Now, let’s look at the quarterly performance of these three QSR companies.
#1 Jubilant FoodWorks: 19.5% EBITDA Margins Anchor ₹2,500 Cr Base
Jubilant FoodWorks reported 13.66% YoY revenue growth in the recent quarter with revenue of Rs 2,569.65 cr. The operating margin came in at 19.48%. The operating margin of Jubilant has been very stable over the last few quarters ranging between 19%-20%.
Despite some higher ingredient costs and other headwinds, the company is able to deliver a very stable operating margin. The recent quarterly EBITDA was Rs 500.57 cr, up from Rs 456.69 cr in the year-ago quarter.
| Period | Q1FY26 | Q2FY26 | Q3FY26 | Q4FY26 | Q1FY27 |
| Revenue (₹ crore) | 2,260.86 | 2,340.15 | 2,437.22 | 2,499.47 | 2,569.65 |
| YoY Revenue Growth (%) | 13.80 | 12.11 | 11.83 | 18.84 | 13.66 |
| Operating Margin (%) | 20.20 | 20.37 | 20.57 | 18.95 | 19.48 |
| EBITDA (₹ crore) | 456.69 | 476.69 | 501.34 | 473.65 | 500.57 |
Popeyes Delivers 40% Like-for-Like Growth to Build ₹1,000 Cr Engine
In the recent earnings call, Jubilant’s management mentioned that Popeyes has shown more than 40% like-for-like sales growth. This has made Popeyes a second growth engine for the company. The management also mentioned that they would like to build Popeyes’ into a Rs 1,000 cr brand over the next three to four years.
Delivery Moat Intact, but Domino’s Pushes Value to Revive Dine-In
Another major issue raised in the earnings call was the attention to dine-in sales. Jubilant has been able to show very high delivery and app-based sales. However, its dine-in sales have suffered over the last few quarters. The management is looking to add more deals for dine-in customers to improve this revenue stream. Domino’s reported like-for-like sales of 2.5% in the recent quarter, which is up from 0.2% in the preceding quarter. However, this is below the long term annual target of 5%-7%.
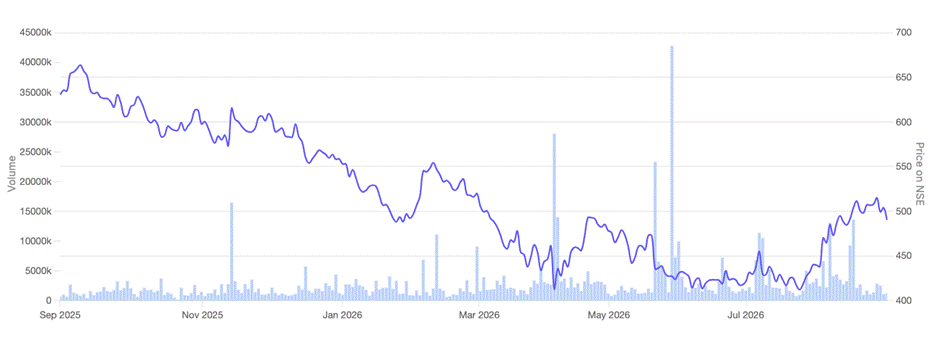
1-year price chart of Jubilant FoodWorks
#2 Devyani International: Leading Sector Growth with 16.5% YoY Expansion
Devyani International reported 16.47% YoY revenue growth in the recent quarter with revenue of Rs 1,580.52 cr. The operating margin was 16.10% compared to 15.10% in the year-ago quarter. The EBITA has also increased to Rs 254.80 cr from Rs 204.91 cr in the year-ago quarter.
| Period | Q1FY26 | Q2FY26 | Q3FY26 | Q4FY26 | Q1FY27 |
| Revenue (₹ crore) | 1,357.00 | 1,376.75 | 1,440.89 | 1,436.86 | 1,580.52 |
| YoY Revenue Growth (%) | 11.10 | 12.60 | 11.30 | 18.50 | 16.47 |
| Operating Margin (%) | 15.10 | 15.40 | 15.90 | 15.17 | 16.10 |
| EBITDA (₹ crore) | 204.91 | 212.02 | 229.10 | 218.00 | 254.80 |
Store-Level Productivity: Revenue Growth Outpaces Store Additions 3x
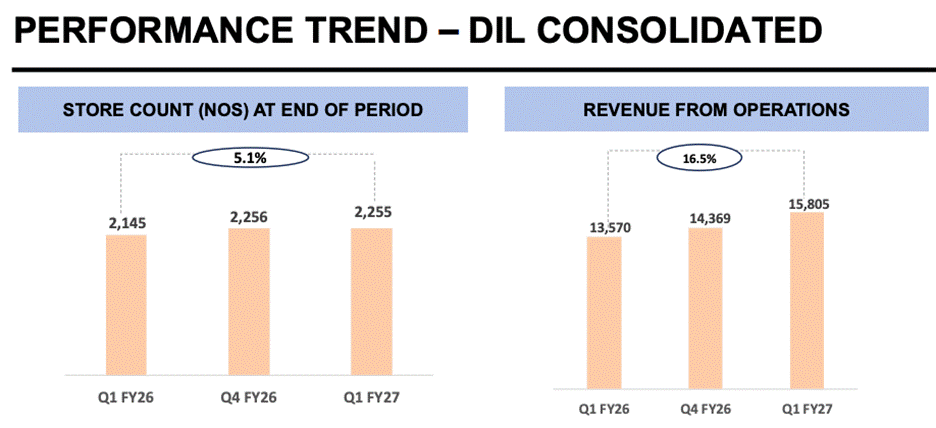
A key trend for Devyani in the recent quarter was the significant gap between YoY consolidated revenue growth and store count growth. The Q1 FY27 consolidated revenue was Rs 1,580.5 cr with a 16.5% YoY growth. However, the store count increased at a lower pace of 5.1% YoY to 2,255 stores in the recent quarter. This shows that the company is able to drive a much higher revenue growth from the same stores.
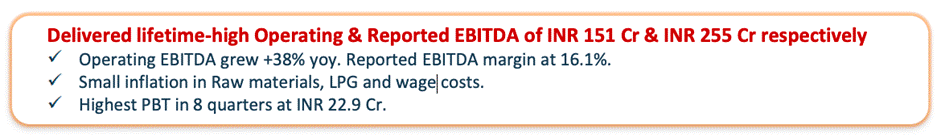
The operating EBITDA grew 24.4% YoY in the recent quarter. There were some headwinds due to inflation in raw materials, LPG, and wage costs. Despite these challenges, the company delivered the highest Profit before Tax in 8 quarters.
Scaling of high-potential brands like Costa Coffee and Biryani By Kilo provides a major growth lever for the company. The company is also integrating self-ordering kiosks, which should improve the ticket size and operational speed.
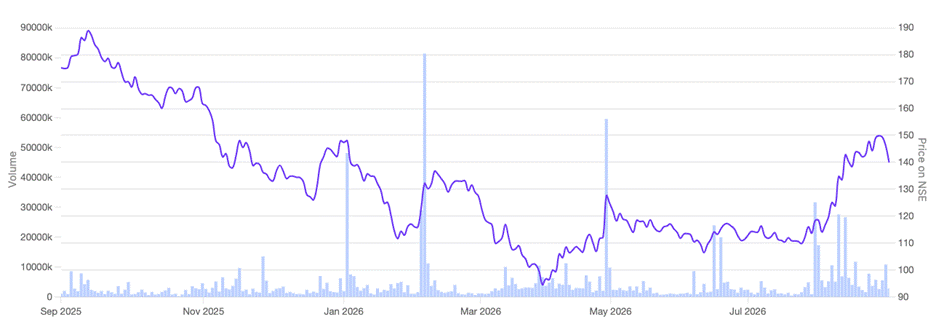
1-year price chart of Devyani International
#3 Westlife Foodworld: Top-Line Hits 11.9% High Amid Margin Defence
Westlife FoodWorld reported YoY revenue growth of 11.86%, which was the highest in the past few quarters. The operating margin came in at 12.86%, and EBITDA was Rs 94.60 cr.
| Period | Q1FY26 | Q2FY26 | Q3FY26 | Q4FY26 | Q1FY27 |
| Revenue (₹ crore) | 657.64 | 652.54 | 671.00 | 655.36 | 735.64 |
| YoY Revenue Growth (%) | 6.70 | 5.30 | 4.80 | 8.70 | 11.86 |
| Operating Margin (%) | 14.00 | 11.63 | 14.71 | 13.25 | 12.86 |
| EBITDA (₹ crore) | 92.12 | 75.90 | 98.70 | 86.84 | 94.60 |
SSSG Rebounds to 4.3%: Everyday Value Platform Drives Traffic
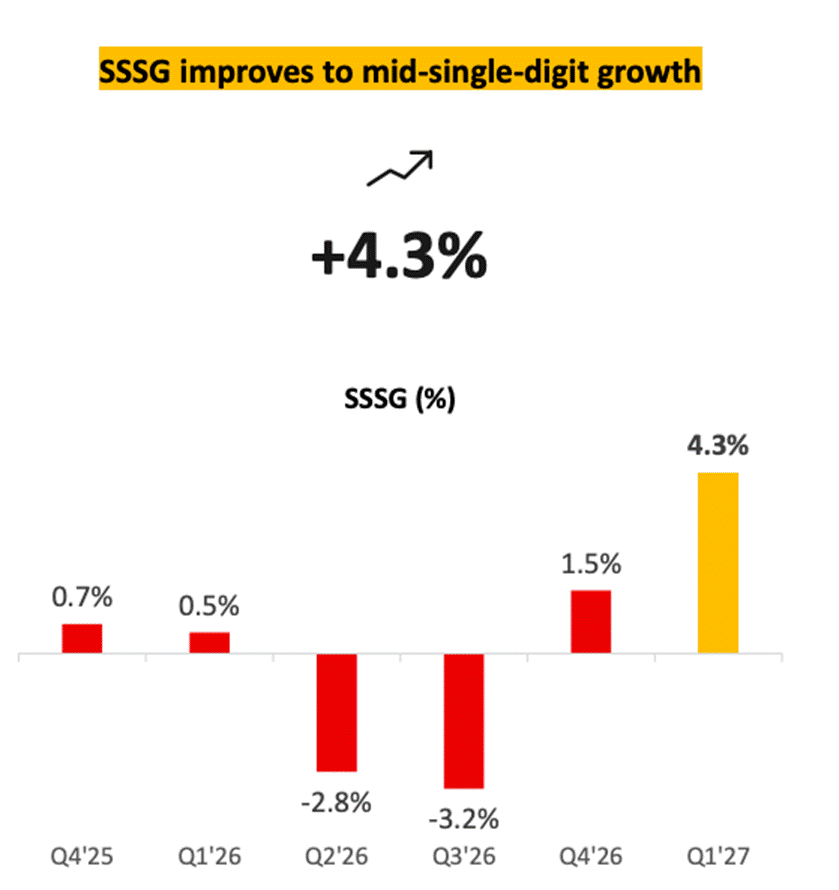
The same store sales growth, or SSSG, has improved in the recent quarter to 4.3% from 1.5% in the previous quarter. It is also significantly higher than year-ago SSSG growth of 0.5%.
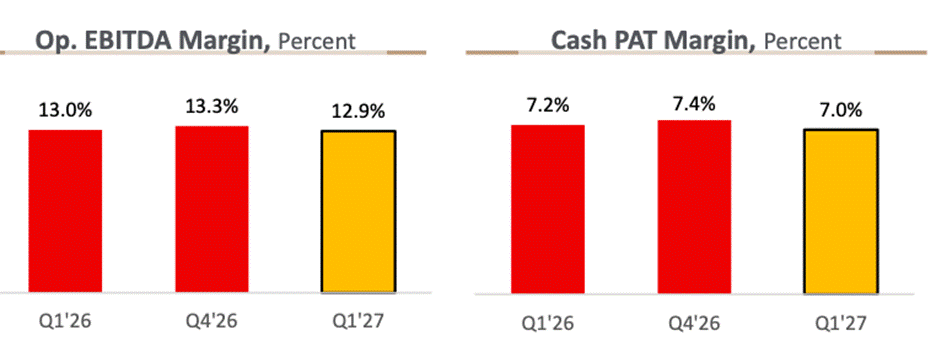
The operating EBITDA margin was 12.9% in the recent quarter compared to 13.0% in the year-ago quarter.
The 630-Store Roadmap: Scaling McDelivery and Value Formats
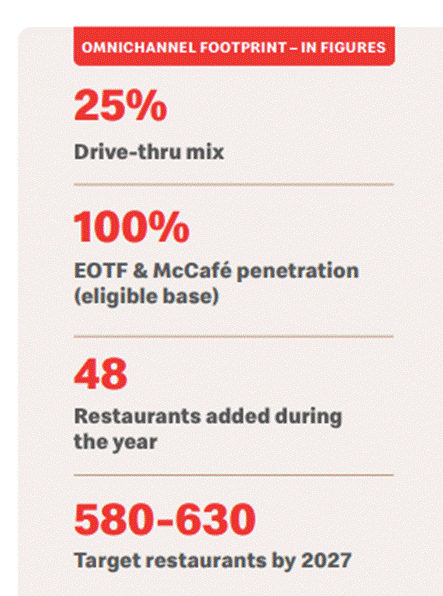
The Rs 99 Everyday Value platform continues to show a promising response from customers as it increases store traffic significantly. The company added 48 new restaurants in the previous fiscal year and plans to have 580-630 restaurants by 2027.
New value meals along with store expansion could help Westlife deliver strong YoY revenue growth in the next few quarters. The McDelivery initiative has also become a key priority for the management as it allows the company to control the entire user experience and reduce dependence on third-party aggregators.
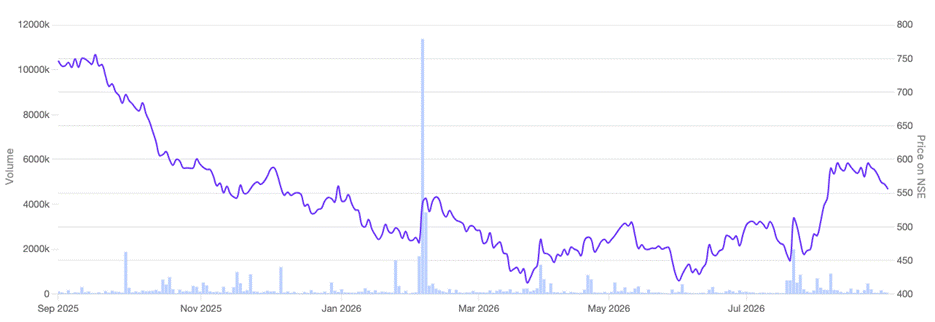
1-year price chart of Westlife Foodworld
Head-to-Head: Delivery Moats vs. Menu Diversification
Jubilant FoodWorks has the highest revenue base of over Rs 2,500 cr. Devyani International reported the highest YoY revenue growth of 16.47%. Jubilant also has the highest EBITDA margin at 19.48%.
The key strength of Jubilant is its exceptional delivery platform and traction of Popeyes. Not having to rely on third-party delivery aggregators gives Jubilant a massive edge over other competitors. It allows the company to control the entire customer experience and improve the loyalty towards its platform.
Devyani is seeing a strong momentum in KFC India along with aggressive digital transformation. Having a wider portfolio of categories also diversifies the risk for the company. Devyani has particularly focused on some of the home-grown brands and scaling them quickly.
Westlife has improved its SSSG through its value meals and is ramping up its store count which is a major tailwind for revenue growth. The value meal proposition for Westlife is still strong and the recent experience has shown the massive impact on store traffic from value meals. Westlife has maintained its operating margin between 12.5%-14.5% in the last few quarters. Despite the launch of value meals and additional headwinds on input costs, the company has continued to deliver a stable margin metric.
| Particulars | Jubilant FoodWorks | Devyani International | Westlife Foodworld |
| Q1 FY27 revenue | Rs 2569.65 cr | Rs 1,580.52 cr | Rs 735.64 cr |
| YoY growth | 13.66% | 16.47% | 11.86% |
| EBITDA | Rs 500.57 cr | Rs 254.80 cr | Rs 94.60 cr |
| EBITDA margin | 19.48% | 16.10% | 12.90% |
Valuation Matrix: Assessing EV/EBITDA Multiples Against Return Ratios
Jubilant FoodWorks trades at an EV to EBITDA ratio of 18.23 compared to 21.71 for Devyani International and 27.83 for Westlife Foodworld. The industry median is 19.22. The Return on Capital Employed (ROCE) of Jubilant is 14.80% compared to 4.75% for Devyani, 6.34% for Westlife, and industry median of 6.17%. The Return on Equity (ROE) of Jubilant FoodWorks is 20.96% compared to -1.56% for Devyani, -3.79% for Westlife, and -0.88% industry median.
| Peer comparison | |||
| Company | EV/EBITDA | Return ratios (%) | |
| ROCE (%) | ROE (%) | ||
| Jubilant FoodWorks | 18.23 | 14.80 | 20.96 |
| Devyani International | 21.71 | 4.75 | -1.56 |
| Westlife Foodworld | 27.83 | 6.34 | -3.79 |
| Industry Median | 19.22 | 6.17 | -0.88 |
Industry Outlook: Navigating Cannibalization as Store Aggression Mounts
We can see from the above analysis that all the major QSR companies are planning aggressive store expansion. This shows that the overall pie is growing rapidly as more customers move to organized food brands. Some of the brands are pursuing customers at entry price points like Westlife’s Rs 99 Everyday Meal program.
This increases the store traffic and also increases the total addressable market. We could see this volume play increase in the next few quarters as companies try to increase footfall, both in the dine-in segment as well as the delivery options.
At the same time, it is important to focus on margins. Aggressive store count growth can sometimes lead to cannibalization of own sales and hurt the margins.
Whether the stocks deliver from here on, only time will tell. It may be a good idea to add Jubilant Foodworks, Devyani International and Westlife Foodworld to the watchlist.
Disclaimer
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation. Only in cases where the data was unavailable have we used an alternative, widely used, and accepted source of information
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
About the Author: Rohit is a seasoned financial writer with over a decade of experience covering Indian and international stocks. He specializes in converting complex financial data into actionable insights that can help readers make better calls. He covers macroeconomic trends globally, which gives a better analysis of the growth runway for companies in key sectors.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article. The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities, or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources, and only after consulting such independent advisors as may be necessary.