



Welcome to the latest edition of Dividend Hunter. In recent weeks, we have analysed companies where strong cash flows could translate into consistent dividends going forward. In our previous edition, we covered an internet platform connecting students and counselling partners with global higher education institutions, offering a 4.7% dividend yield. This week, we turn to a real estate player that owns, manages, and leases out premium commercial real estate assets.
The commercial real estate sector in India, particularly in major hubs like Mumbai, is seeing strong and steady demand. Multinational corporations and institutional investors are actively seeking premium, well-managed Grade A office spaces.
This momentum is driven by specific industries. Information Technology, multinational banks, financial services, and Global Capability Centres are the primary sources of office demand. While cheaper office space is available in further suburbs and satellite cities, premium hubs remain highly competitive because of connectivity.
Nirlon Knowledge Park: Catering to Global Giants
Nirlon Limited (market cap: ₹5,662 crore) meets these industry demands directly through its asset, Nirlon Knowledge Park (NKP) in Goregaon. NKP is a high-grade, 23-acre campus designed specifically for the IT, banking, and financial services sectors. By catering to these top-tier, institutional occupiers, Nirlon secures reliable and steady rental income.
Join now
Nirlon then uses this income to reward shareholders. The company paid ₹30 per share as a dividend for FY26, up 15% from the ₹26 dividend paid in FY24 and FY25. Dividend payments are also supported by a payout policy of one interim dividend (ex-date usually in February) and one final dividend a year (in September).
The company generates free cash and has been paying consistent dividends every year for over a decade. In addition to dividends, the company’s share price has also delivered returns at 16% CAGR over the last five years. But can its financial performance remain strong enough to sustain these dividends in the years ahead? Let’s start with its business model.
The Backbone of Nirlon’s Revenue
Nirlon’s business model relies on two main income-producing assets in Mumbai, India: NKP and Nirlon House in Worli, Central Mumbai. Nirlon operates on a core operating lease model. Key elements of this revenue structure include:
- Consistent License Fee Income: The company licenses its office spaces to multinational and Indian institutional corporate tenants in the IT/ITeS, banking, and financial services sectors. This model accounts for 88.2% (₹590.1 crore) of Nirlon’s FY26 revenue of ₹669 crore and 88.5% (₹149 crore) of Q1FY27 turnover (₹168.3 crore).
- Structured Rental Escalations: These contracts typically include built-in rent-increase clauses. Typically, rent increases 15% every three years, providing organic revenue over the long term. New agreements now transition to annual escalations of approximately 4.75% to smooth rental growth.
- Common Area Maintenance Recovery: Nirlon also recognises separate operational revenue from tenants to recover Common Area Maintenance charges, utility recoveries, and administrative expenses associated with maintaining the properties. The remaining revenue, i.e, 11.8% in FY26 and 11.5% in Q1FY27, came from CAM.
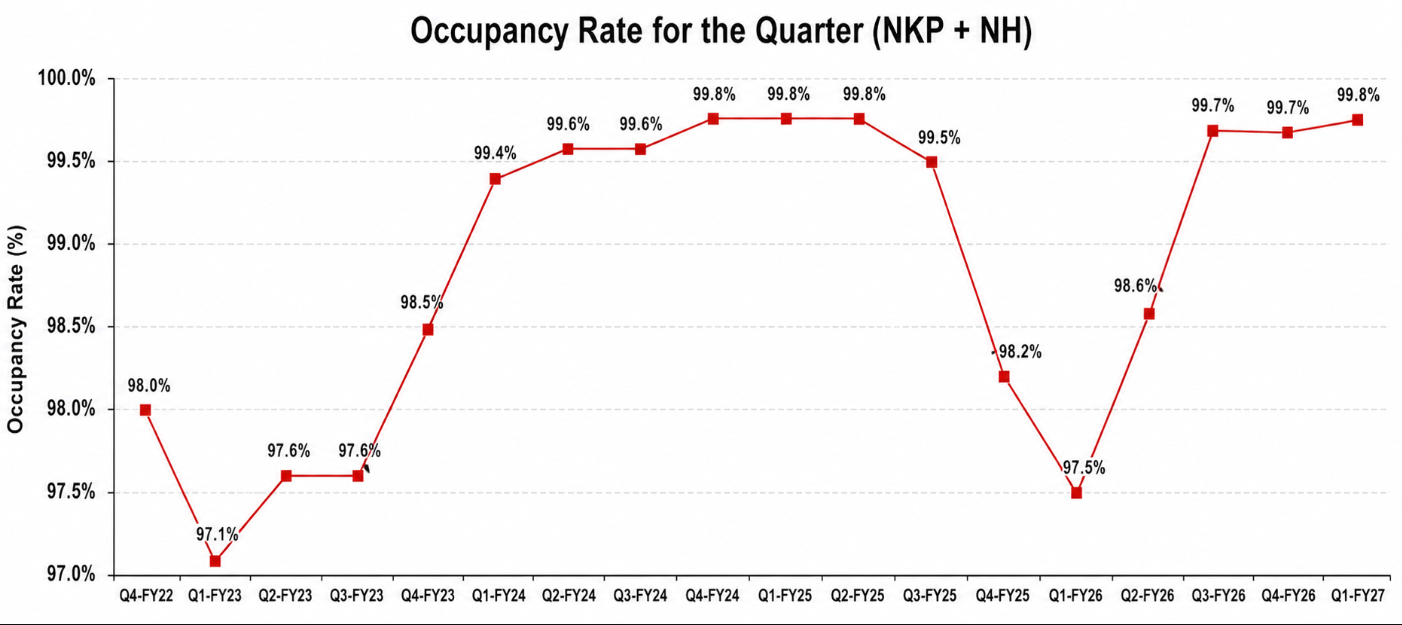
- High Occupancy Strategy: By providing premium, international-standard facilities, Nirlon maintains historically and consistently high occupancy levels above 97%. The occupancy reached 99.8% in Q1FY27.
Related-Party Risks and Management Fees
Additionally, to maintain a lean organisational structure, Nirlon outsources its operational and property management to a specialised partner. In fact, the company only employs three permanent employees for statutory compliance. In consideration, Nirlon pays a monthly lease management fee of 1% and a property management fee of 2% of gross property revenue.
Nirlon Management Services (NMSPL) handles Nirlon’s day-to-day operations. During FY26, Nirlon paid ₹17.7 crore for property management and ₹10.6 crore for marketing fees to NMSPL. However, a major concern is that this is a related party transaction.
Nirlon CEO Rahul V. Sagar is also a promoter, director and member of NMSPL, while his brother Kunal V. Sagar, also a Nirlon promoter, held similar positions in NMSPL when the operational agreements were approved. This overlap raises related-party and governance concerns.
The company claims it mitigates this concern through independent arm’s-length certification, audit committee approval and promoter abstention from voting.
Client Concentration and Relicensing Resilience
Nirlon’s revenue is largely concentrated among its largest partners. In FY26, four key customers alone accounted for more than 10% of total revenue. Together, they contributed ₹454.3 crore, representing approximately 67.9% of Nirlon’s operational revenue of ₹669 crore.
This may not be a major concern. Here’s why – a large tenant vacated 14.6% of Nirlon’s total chargeable area between FY25 and FY26. Despite this major exit, Nirlon successfully relicensed the entire vacated area to a mix of new and existing tenants, quickly restoring occupancy to 99.8% by Q1 FY27. However, any delay in relicensing can impact revenue.
Financially, the company’s revenue has grown at a 16% CAGR over the last five years to ₹669 crore, up 5.2% year on year. Meanwhile, net profit has grown at a much faster 22% CAGR to ₹346 crore, up 58.6% from FY25’s ₹218.2 crore.
Lower tax expense of ₹94.3 crore, driven by the transition to the New Tax Regime, boosted profitability. Nirlon’s operating profitability is robust. EBITDA (Earnings Before Interest, Tax, Depreciation, and Amortisation) rose 4.6% to ₹535.4 crore while margins stood at 78.4%. Total income (₹683.3 crore) is considered for EBITDA calculation.
The company’s Return on Equity (ROE) and Return on Capital Employed (ROCE) stood at 83.8% and 29.1%, respectively. ROE was mainly boosted by the tax transition, rising from 40.2% in FY25. ROCE is supported by the company’s low capital intensity and limited need for large-scale capital expenditure.
The company also reported stable financial performance during Q1FY27. Revenue increased 3% to ₹168 crore, while total income increased 3.4% to ₹172.7 crore. EBITDA increased 1.2% to ₹133.5 crore, while margin stood at 77.3%. Consequently, net profit rose 18.8% to ₹69.4 crore, driven by lower tax expense.
Capital-Light Operations on a Heavy Asset Base
The business model has a high balance sheet asset base, but low operating working capital. This is because its properties are capitalised on the balance sheet. To build and upgrade these office spaces, it carries substantial long-term bank borrowings of ₹1,147 crore.
The company paid ₹107.9 crore as finance cost during FY26, including ₹19.4 crore of non-cash interest discount unwinding on the security deposits. This accounts for the time value of money on the interest-free security deposits that tenants give to Nirlon.
The company’s Net Debt to EBITDA, however, stood at 1.8 times, down from 1.9x in FY25. At the same time, its day-to-day rent-collection business is working-capital-light due to a favourable cash conversion cycle. Nirlon receives interest-free cash security deposits (₹341 crore in FY26) from its tenants.
This upfront liquidity also provides it with operational funding. As Nirlon collects advances, credit risk is negligible, as reflected in ₹3.3 crore in receivables in FY26. With construction phases complete, the business generates cash and routes almost all surplus cash to shareholders.
Converting Strong Revenue to Free Cash Flow
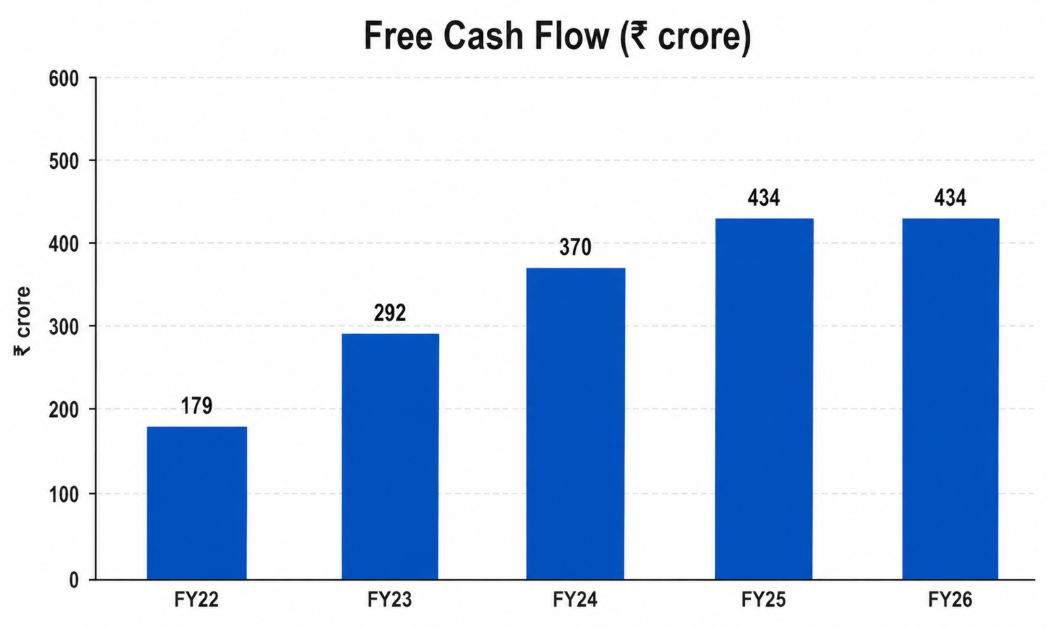
A major portion of its revenue (₹669 crore) was converted into cash flow from operating activities (₹477.5 crore) during FY26. The company spent ₹43.5 crore on routine upgrades and maintenance. Consequently, it generated free cash flow of ₹434 crore in FY26, similar to FY25. Strong free cash flow highlights the company’s ability to sustain dividend payouts.
Historically, from FY15, Nirlon reported negative free cash flow only in FY19 and FY20, reflecting its consistent cash generation over the years. After paying ₹87.9 crore as finance cost, the company was left with ₹346 crore as surplus cash for shareholders.
Of this, the company paid ₹234.3 crore for the FY25 dividend, which has remained consistent since FY23. The rest ₹111.7 crore was added to reserves (total ₹378 crore at the end of FY26). The company may choose to distribute profits from this reserve in exceptional cases.
The company also has strong liquidity on its balance sheet. Nirlon also placed ₹277.8 crore as fixed deposits during FY26, taking total cash and bank balances to ₹297.8 crore. Overall, Nirlon’s free cash generation and liquidity are strong enough to pay a dividend.
Can a ₹30 Total Dividend Be Sustained?
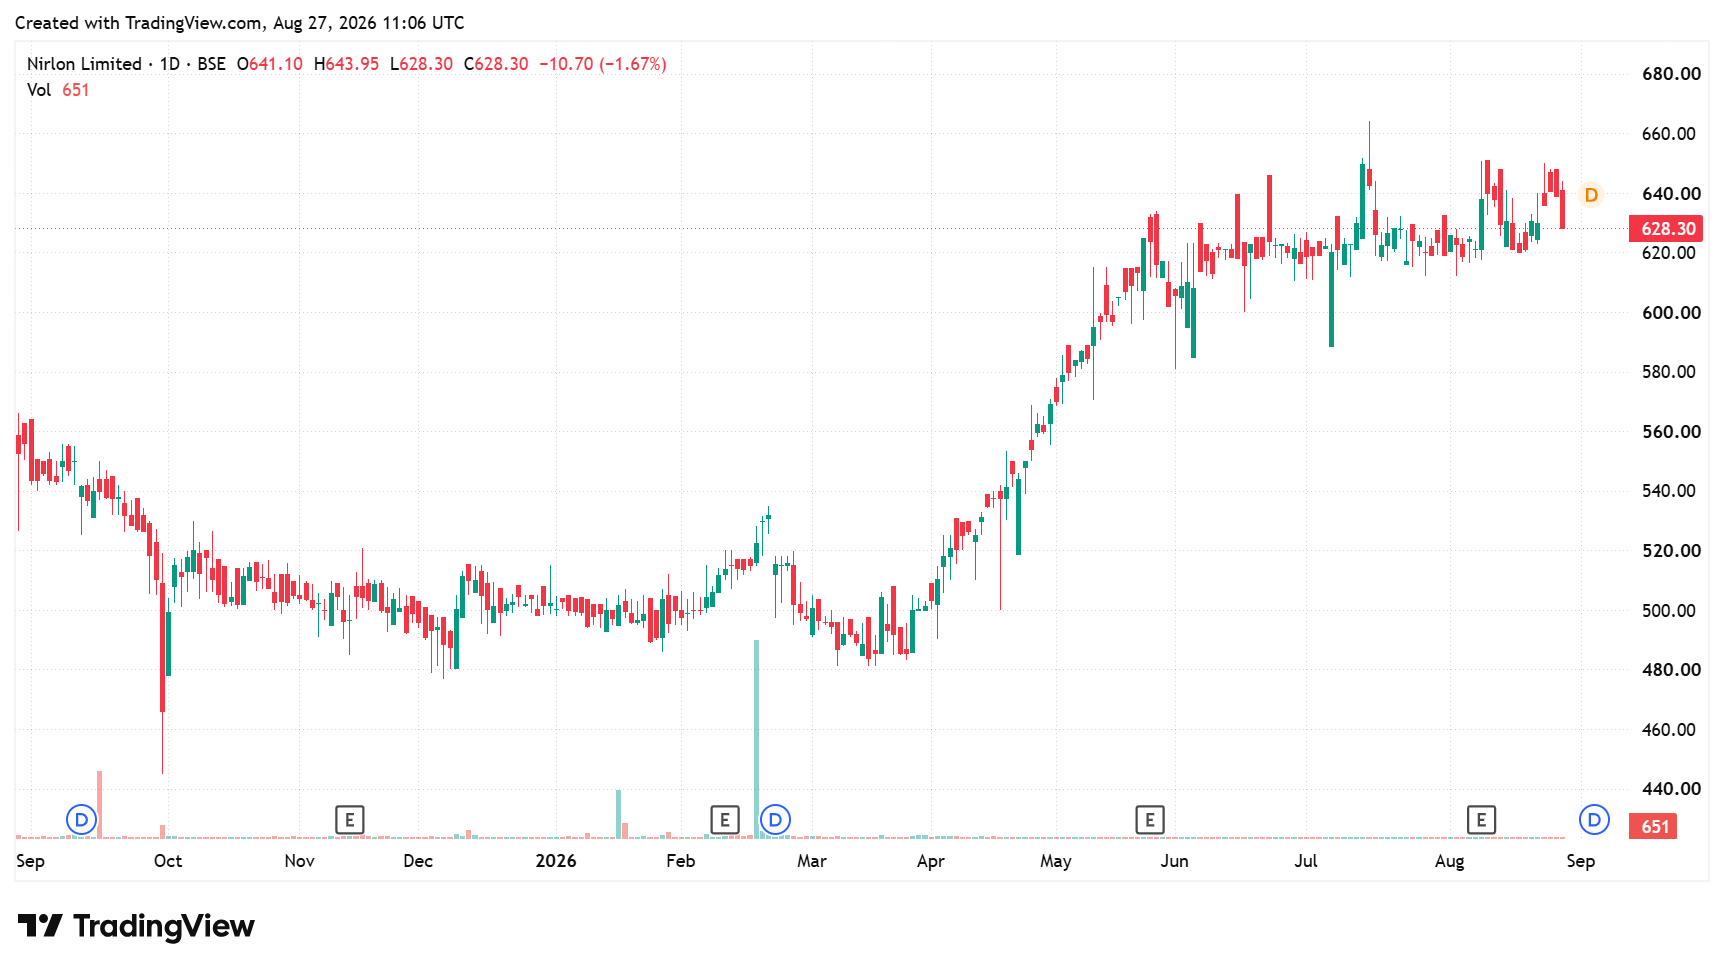
Nirlon declared an interim dividend of ₹15 per equity share and a final dividend of ₹15, taking the total payout for FY26 to ₹30. At the current price of ₹628 (27 August), the dividend yield translates to around 4.8%. The payout is the highest in the last four years, compared with ₹26 per share in FY22, FY23, FY24 and FY25.
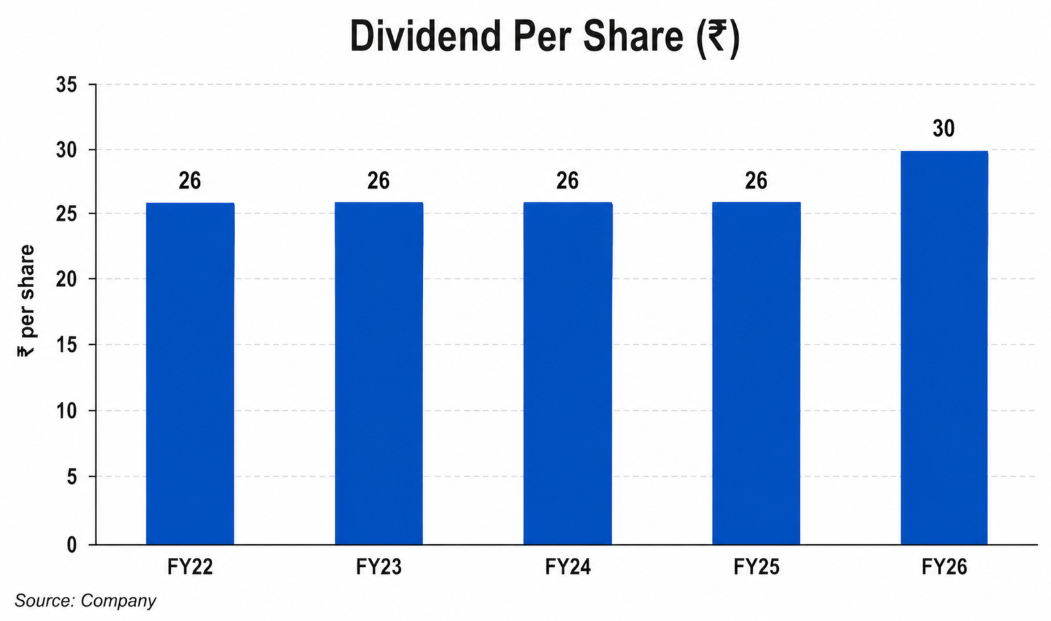
The company paid 78% of its net profit as dividends, while the earlier payout exceeded 100%. This indicates that the company distributes most of its profits to shareholders as dividends. This implies that dividends could increase if net profit growth tracks the historical benchmark. Its payout policy also states that dividends will be paid out of the company’s net profits.
The 2027 Debt Repayment Hurdle
The Board directly weighs the current cash position against its upcoming cash obligations. To this end, a major change to its cash flow allocation is scheduled for May 2027. The HSBC loan (₹1,150 crore) moratorium ends in May 2027. Under the agreement, Nirlon must begin repaying 5% of the principal annually for five years (25% of the total loan).
This scheduled amortisation will require a cash outflow of approximately ₹57.5 crore per year starting in FY28. Because this principal repayment must be serviced from operating cash flow, it will certainly consume some portion of Nirlon’s cash. While strong free cash flow provides a buffer, there could be a trade-off between retaining reserves and sustaining dividends.
As management noted, this repayment obligation will guide capital allocation and could reduce the free cash flow available for future dividends. Additionally, payouts may be reduced or eliminated in case of large expansion, acquisitions, working capital pressures, or declining profits.
The Dividend Hunter Verdict
Nirlon could sustain its progressive dividend payouts in the near term. The company’s highly stable commercial real estate operating lease model generates strong, steady operating cash flows.
This strong cash conversion, characterised by premium Grade A asset occupancy rates reaching 99.8%, helps Nirlon comfortably cover its increased dividend payout of ₹30 per share for FY26. Its strong free cash flows and substantial cash and bank balances provide enough bandwidth to sustain dividends.
While scheduled debt amortisation starting May 2027 will introduce new cash commitments, Nirlon’s predictable asset profile suggests the company can continue to reward shareholders consistently over the long term. Nirlon also trades at a discounted P/E multiple of 15.9x, below the Diversified Commercial Services industry median of 18.0x and NESCO’s 17x.
Dividend hunters should keep this stock on their watchlist.
Disclaimer:
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation and conference call. We used an alternative, widely accepted source of information only when the data were unavailable.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, we strongly advise you to consult your advisor. This article is strictly for educational purposes only.
About the Author: Madhvendra has been deeply immersed in the equity markets for over seven years, combining his passion for investing with his expertise in financial writing. With a knack for simplifying complex concepts, he enjoys sharing his honest perspectives on startups, listed Indian companies, and macroeconomic trends.
A dedicated reader and storyteller, Madhvendra thrives on uncovering insights that inspire his audience to deepen their understanding of the financial world.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, their employees (s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities, or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives and resources, and only after consulting any independent advisors as necessary.