



Welcome to the latest edition of Dividend Hunter. In recent weeks, we have analysed companies where strong cash flows could translate into consistent dividends going forward. In our previous edition, we covered India’s only listed telecom infrastructure company offering a 3.6% dividend yield. This week, we turn to an internet platform connecting students and counselling partners with global higher education institutions.
India’s consumer technology story has quietly entered a new phase. K-12 test prep initially grabbed the headlines for years. SaaS followed, and fintech soon became the market’s favourite theme. Now, another sector is gaining traction without generating the same noise: global student mobility.
Cross-Border Education: Sizing the $420B Study-Abroad Opportunity
Under a structural shift toward tech-enabled cross-border education, emerging-market students are looking for higher education in global colleges to secure careers. Frost & Sullivan estimates the global spending on overseas education to increase to $420 billion by 2030, up from $280 billion in 2024.
This mammoth market size is creating opportunities that extend well beyond companies that simply operate traditional schools. Crizac Limited (market cap: ₹3,050 crore) sits as an AI-native B2B platform. It provides student recruitment solutions to higher education institutions.
Join now
The company paid ₹8 per share as a dividend for FY26, supported by a policy that commits to returning at least 40% of net profit to shareholders. Its consistent cash generation and asset-light business model further support this payout. But can its financial performance remain strong enough to sustain these dividends in the years ahead? Let’s start with its business model.
The Asset-Light Engine: Connecting 5,300+ Agents with 450+ Global Universities
In simple terms, Crizac is an intelligent matchmaking and processing platform for international higher education. Instead of finding and advising students directly, Crizac works through three main pillars:-
- The Students: Aspiring individuals who want to study overseas.
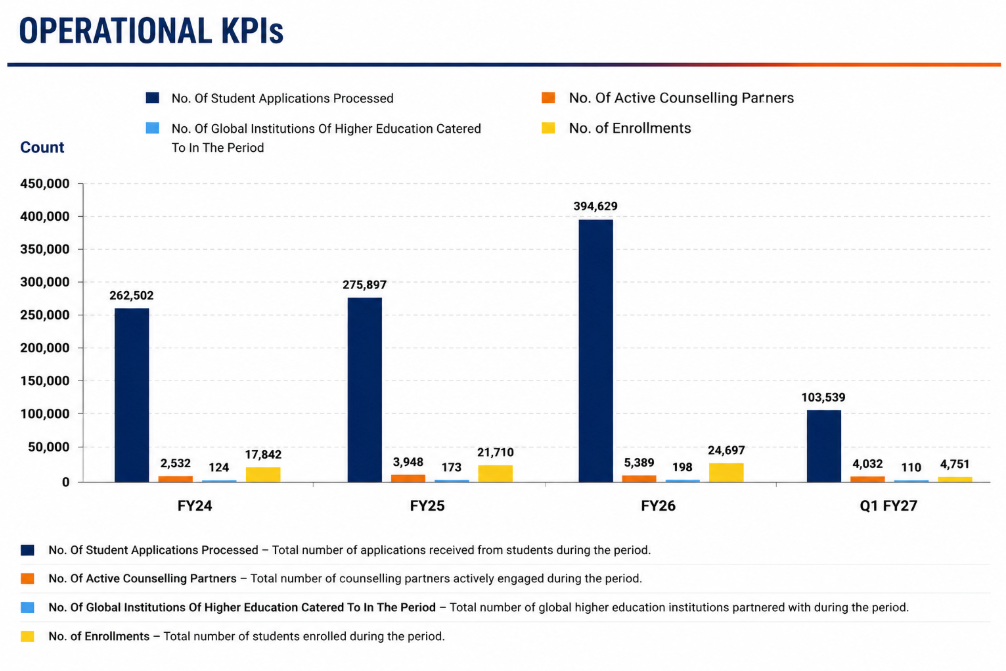
- The Counselling Partners: Independent, local agents (with 5,389 active partners) who counsel students in their home countries.
- The Universities: Over 450 global partner institutions across major destinations like the UK, Ireland, Canada, Australia, and New Zealand.
The B2B Flywheel: Why Realisation Rose to ₹4.2 Lakh per Student
When a counselling partner prepares a student’s application, they submit it through Crizac’s proprietary digital platform, the Central Application Management System. Crizac uses AI-driven automation and screening tools to verify academic records, check for regulatory compliance, and flag any documentation errors.
This filtration ensures that partner universities only receive high-quality, genuine applicants. For the university, it cuts down on processing overhead and avoids costly visa rejections. To date (Q1FY27), Crizac has processed 12+ lakh student applications. The company has processed over 1,036,567 applications during FY24-Q1FY27 and successfully enrolled 69,000 students.
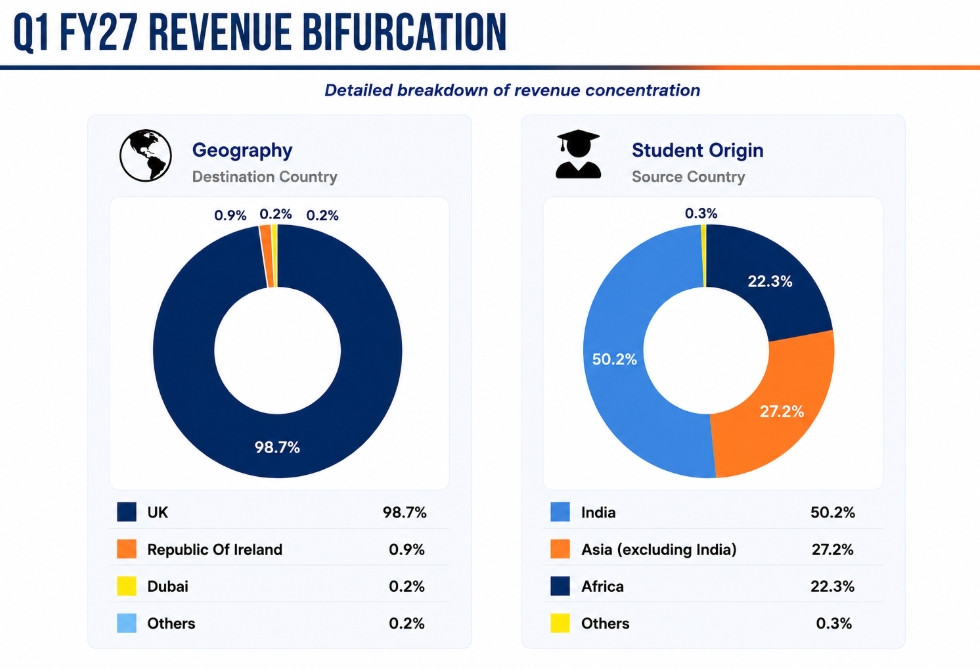
Among destination countries, the UK is the preferred destination country, contributing 98.7% of revenue in Q1FY27. India, on the other hand, accounts for 50.2% of student origin countries, followed by Asia (excluding India) at 27.2%, Africa (22.3%), and others (0.3%).
Once a student successfully registers at the university, the university pays Crizac a commission. The company then shares a portion of that commission with the counselling partner who did the ground-level work. The average commission Crizac receives from universities per successful student enrollment has been steadily increasing.
The number of enrolments has been steadily increasing, rising from 17,842 in FY24 to 24,697 in FY26. In Q1FY27, 4,751 candidates had enrolled. In Q1FY27, the platform enrolled 10% of the 47,488 unique applicants. Of the total applications, the enrollment ratio is 6.8% (FY24), 7.9% (FY25), and 6.3% (FY26).
In Q1, the company converted 4.6% of applications into enrollments. The Q1 conversion rate is seasonally lower, as many processed applications are deferred to convert during the peak H2 cycles. Accordingly, the commission per student has increased from ₹3.5 lakh in FY24 to ₹4.0 lakh (FY26) and ₹4.2 lakh in Q1FY27.
Expanding the Take-Rate: How Commission Retention Scaled to 37.5%
Consequently, revenue grew at 56% CAGR during the last five fiscal years ending FY26 to ₹1,042 crore. Crizac then shares a large portion of this commission with the counselling agents. This expense typically consumes between 62.5% and 70.5% of total revenue. For instance, in FY26, it paid ₹703.2 crore as agent commissions.
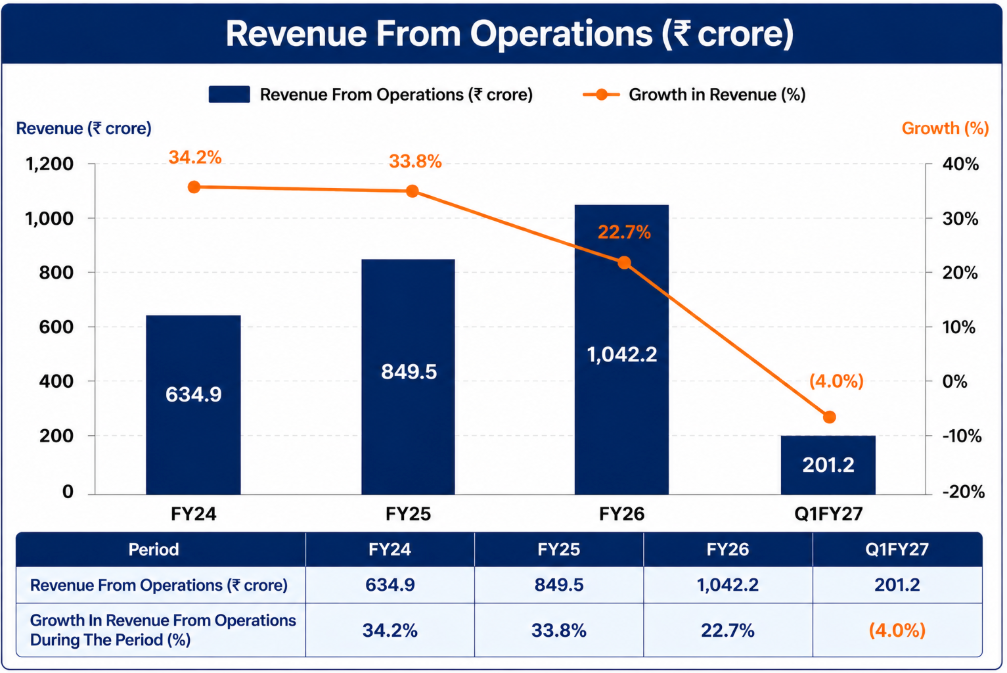
The balance ₹339 crore is retained commission or gross profit. Over time, Crizac has managed to retain a larger slice of the pie as the platform scales. It retained 30% of the commission in FY24, 29.5% in FY25 and 32.5% in FY26. The retention ratio in Q1FY27 stood at 37.5%.
Cash Flow Conversion: How Asset-Light Operations Fund the 40% Payout
This business is scalable and asset-light because Crizac doesn’t need to build physical campuses or employ thousands of local counsellors directly. The company’s EBITDA (Earnings Before Interest, Tax, Depreciation, and Amortisation) margin has expanded sharply from 11.4% in FY24 to 27.1% in FY26 and further to 29.8% in Q1FY27. Meanwhile, its net profit margin improved from 15.6% to 22.6% over the same period.
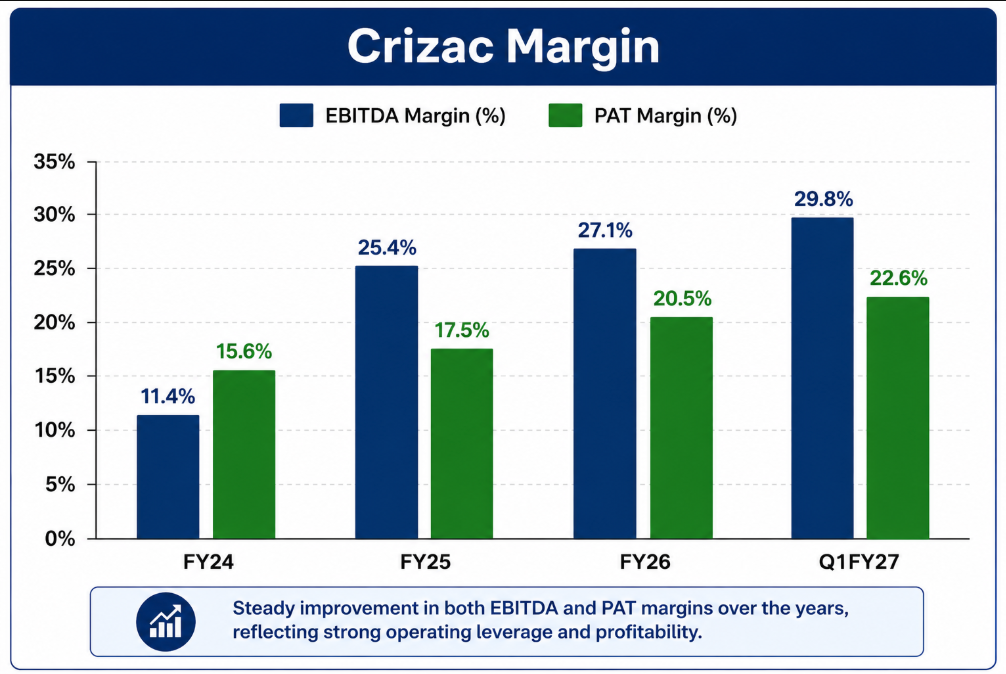
This expansion indicates that the company is retaining more revenue as operating profit, pointing to better operating efficiency and improved profitability. Return on Equity has also improved from 34.8% to 37.2% in FY26, while Return on Capital Employed has moderated to 48.6% from 54.9% in FY24.
Negative Working Capital Dynamics: The Zero-Debt Cash Machine
Additionally, the business working capital requirements are negligible. In fact, during Q1FY27, Crizac working capital days were negative 29 days, which shows that it first takes commission from the institution and later pays its agents.
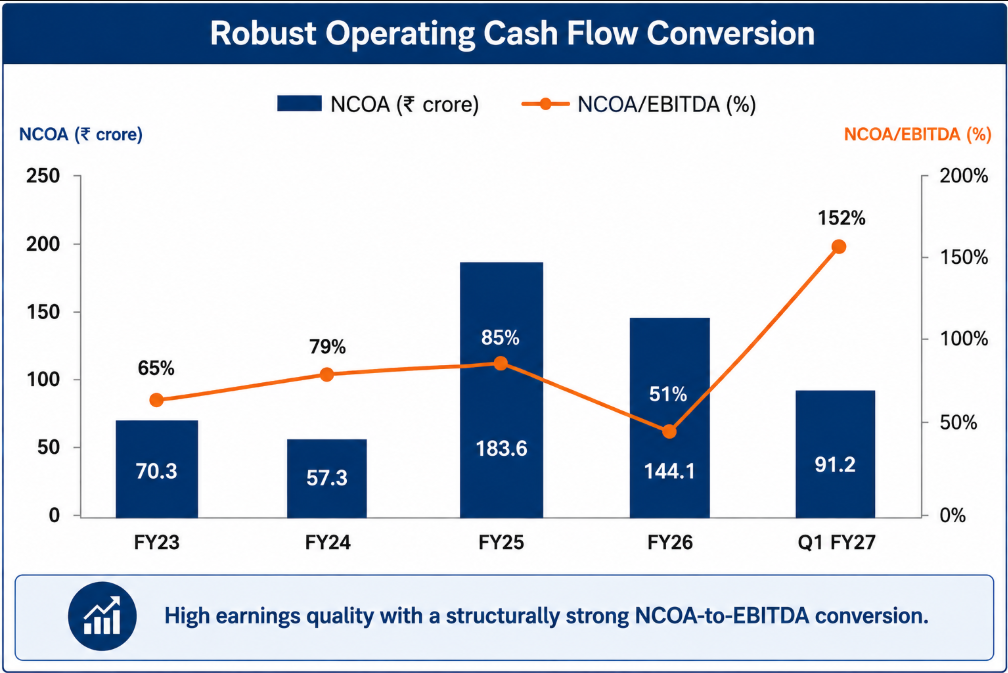
The company has negligible debt, which means almost every rupee generated from operations is retained as net surplus. The historical trend highlights a robust conversion. The company converted 65% of EBITDA into Net Cash Flow from Operating Activities (NCOA) in FY23, which increased to 79% (FY24), 85% (FY25) and fell to 51% (FY26).
Free Cash Flow Conversion: Turning Operating Surplus into ₹571 Cr Liquidity
After accounting for capital expenditure, the company generated no Free Cash Flow (FCF) in FY24 according to Screener. However, FCF turned positive in FY25 at ₹179 crore, after ₹6 crore of capital expenditure, and stood at ₹127 crore in FY26, after ₹17 crore spent on fixed assets.
The company’s total cash, including bank balances and fixed deposits, increased to ₹571.1 crore in Q1FY27 from ₹449.8 crore as of June 30, 2025. The cash flow and liquid cash on the balance sheet trend show that the business is consistently generating cash.
The 40% Payout Policy: Can an ₹8 Interim Dividend Be Sustained?
Management aims to use this cash to reward shareholders in accordance with its dividend distribution policy. This policy aims to strike a balance between investing in high-return opportunities and rewarding shareholders. Its minimum commitment is to distribute at least 40% of net profit as dividends for the next three financial years.
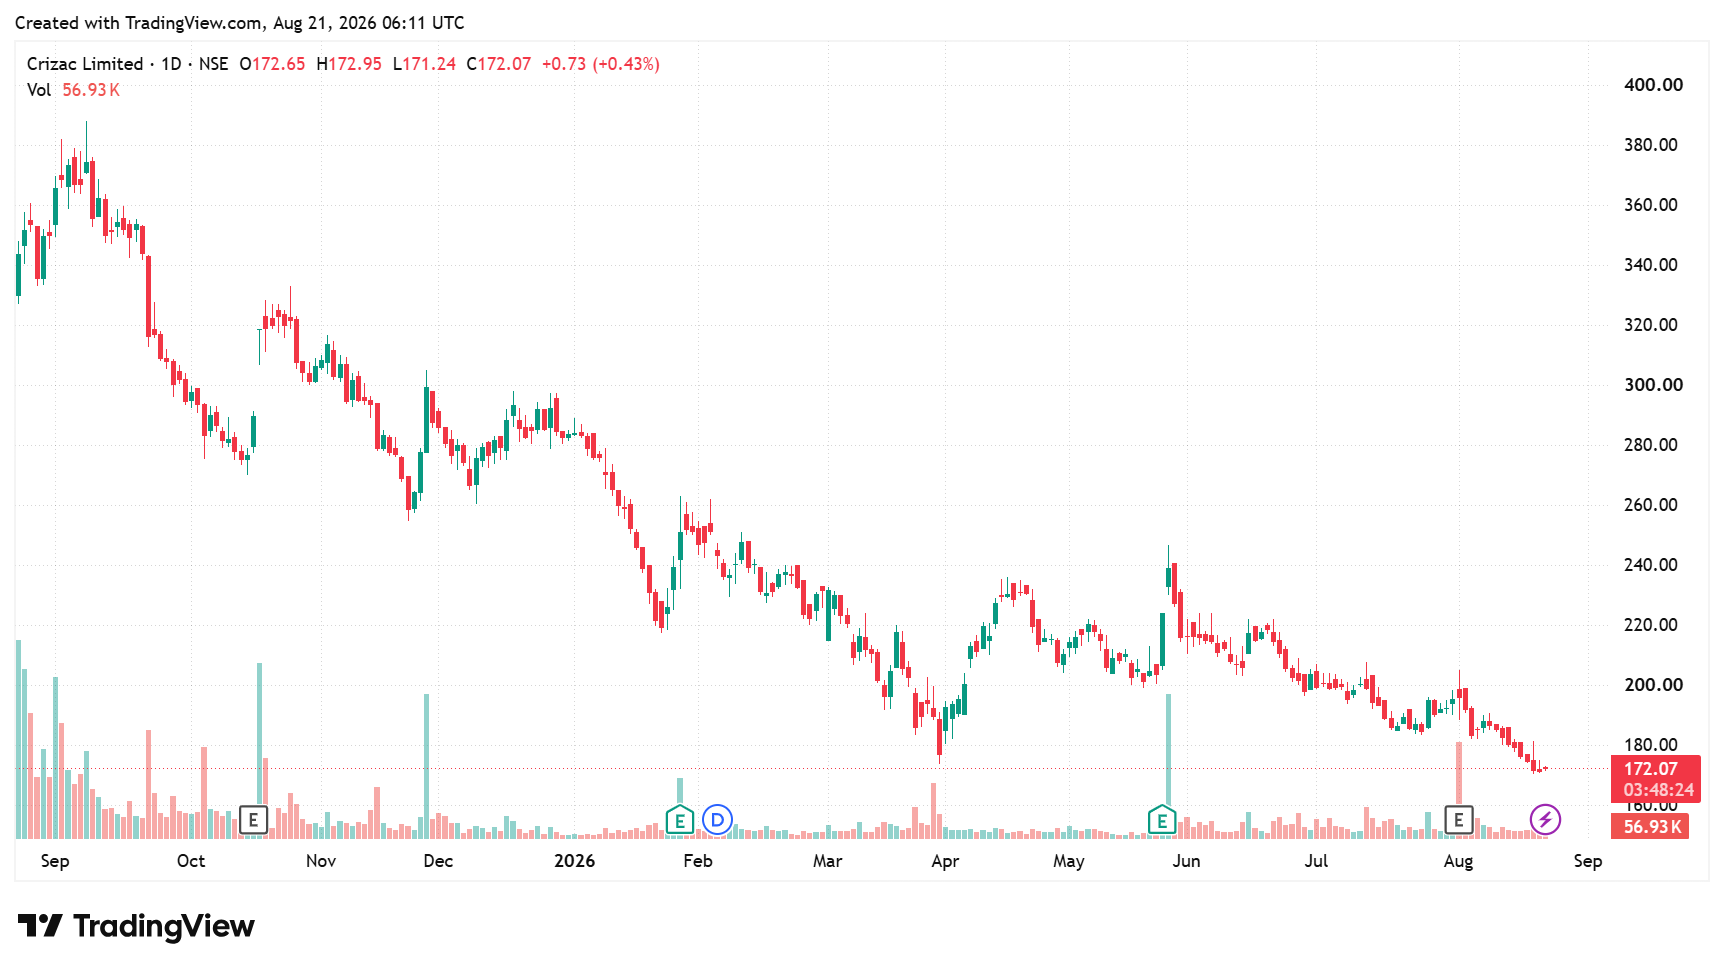
Following its successful public listing in July 2025, Crizac declared an interim dividend of ₹8 per equity share for FY26, amounting to ₹140 crore. Despite this, the company’s net cash flow for the year was ₹47 crore, up from ₹39 crore in FY25 and ₹35 crore in FY24. At the current market price of ₹170, the dividend yield translates to 4.7%.
This ₹8 dividend represented approximately 64% of the company’s consolidated net profit of ₹219 crore. This is well above the company’s 40% minimum commitment. Historically, net profit grew at a CAGR of 60% over the past five fiscal years, ending in FY26.
This suggests that dividends could increase if net profit growth tracks the historical benchmark. However, if profitability weakens, the dividend payout could also come under pressure. In case the company reports a loss, it may not pay a dividend.
Geographic Concentration Risk: Reducing UK Dependence from 98.7%
However, the company reported muted Q1FY27 financials. Operating income declined 4% year-on-year to ₹201.2 crore. This was due to a less favorable mix of university partners during the quarter, even as average realization per student rose to ₹4.2 lakh. For Crizac, H2 is typically their peak revenue and enrollment period.
As a result, EBITDA margin declined 116 bps to 29.8%. However, net profit remained stable at ₹46 crore, while margin expanded by 152 bps to 22.6%. Looking ahead, management aims to reduce the UK revenue share to below 60% within 2-3 years. This will reduce geographic dependence.
Crizac is expanding its presence in other English-speaking countries such as Canada, Australia, Ireland, and the United States. It is expanding its capabilities in New Zealand and entering the fast-growing regions of Continental Europe (such as Germany and France) and Southeast Asia (Singapore).
Origin Diversification: Tapping Latin America and Non-Indian Applicant Pools
Previously, India was the primary source of student applications for Crizac. However, it is now reducing its dependence on this region. For the first time, students from outside India represent more than half (51%+) of total recruitment volume. Crizac is actively pursuing student origin diversification in Asia, Africa, MENA, and Latin America.
The acquisition of StudiesPlanet has opened up the Latin American student pipeline, which has demonstrated higher application-to-enrollment conversion rates than some of Crizac’s existing markets. Moreover, to decrease reliance on commission, Crizac is building out high-margin ancillary services.
The company offers accommodation services and student loans (launched in FY26 with major banks and NBFCs). These services help ensure student attendance, which results in direct payments to universities and increased revenue per student. It is also preparing to launch travel insurance, foreign exchange, and specialised visa services directly through its platform.
Valuation Matrix: Why Crizac Trades at a Discount to Tech Peers
In terms of valuation, Crizac is trading at a price-to-earnings multiple of 13.7x, which is at a discount to the internet and catalogue retail platforms industry P/E of 19.8x and peer companies like Info Edge (59.6x), IndiaMART InterMesh (21.3x), and Matrimony.Com (24.9x).
The Dividend Hunter Verdict
Crizac Limited is well-positioned to sustain its committed dividend payouts. The company’s asset-light B2B platform generates strong, steady operating cash flows. This robust cash conversion allows the company to comfortably cover its targeted dividend payouts of at least 40% of net profit.
Its strong free cash flow, cash and cash equivalents, and debt-free balance sheet ensure that its capital distribution model remains insulated from temporary industry headwinds. This suggests Crizac could potentially continue to reward shareholders consistently over the long term.
However, key risks could disrupt Crizac’s dividend distribution model. Revenue concentrated in the UK, and sudden changes in immigration policies present severe headwinds. Its dependence on a small group of universities adds another layer of risk. The top 10 university partners account for 69% of revenue, making partner concentration an important risk to monitor.
Dividend hunters should keep this stock on their watchlist.
Disclaimer:
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation and conference call. We used an alternative, widely accepted source of information only when the data were unavailable.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, we strongly advise you to consult your advisor. This article is strictly for educational purposes only.
About the Author: Madhvendra has been deeply immersed in the equity markets for over seven years, combining his passion for investing with his expertise in financial writing. With a knack for simplifying complex concepts, he enjoys sharing his honest perspectives on startups, listed Indian companies, and macroeconomic trends.
A dedicated reader and storyteller, Madhvendra thrives on uncovering insights that inspire his audience to deepen their understanding of the financial world.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, their employees (s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities, or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives and resources, and only after consulting any independent advisors as necessary.