



Welcome to the latest edition of Dividend Hunter. Over the past few weeks, we have analysed companies where strong cash flows could translate into consistent dividends going forward. In our previous edition, we covered a Navratna Public Sector Company and one of Indian Oil’s key group companies offering a 5% Dividend Yield.
Today, we discuss the pioneer of India’s mutual fund industry and one of the country’s premier Asset Management Companies (AMCs). The AMC manages Assets Under Management (AUM) of ₹20.6 lakh crore as of June 2026 and services a live folio base of 1.4 crore investors across 699 districts.
The stock we focus on in this edition of Dividend Hunter is UTI Asset Management Company Limited (UTI AMC), an Asset Management Company with no identifiable promoters.
The Asset-Light Advantage: Why Core Profits Convert Directly to Cash
UTI AMC’s business is asset-light. This minimal need for capex allows core profits to convert directly into strong, predictable free cash flow. The company consistently distributes this cash to shareholders, as evidenced by a dividend payout ratio of 64% to 95% during FY22-FY26.
Join now
The company paid a dividend of ₹40 per share in FY26, up from ₹26 in FY25. UTI AMC pays regular dividends and has a dividend distribution policy that aims to balance rewarding shareholders with maintaining reserves for business growth and expansion.
The key question is whether UTI AMC can continue maintaining these payouts and, if yes, how much it can distribute going forward. We have tried to find it out by analysing the company’s profitability, cash flows, balance sheet, and, of course, its dividend payout policy. But first, let’s start with the business.
The Fee Realisation Gap: Why 80% of AUM Contributes Minimal Revenue
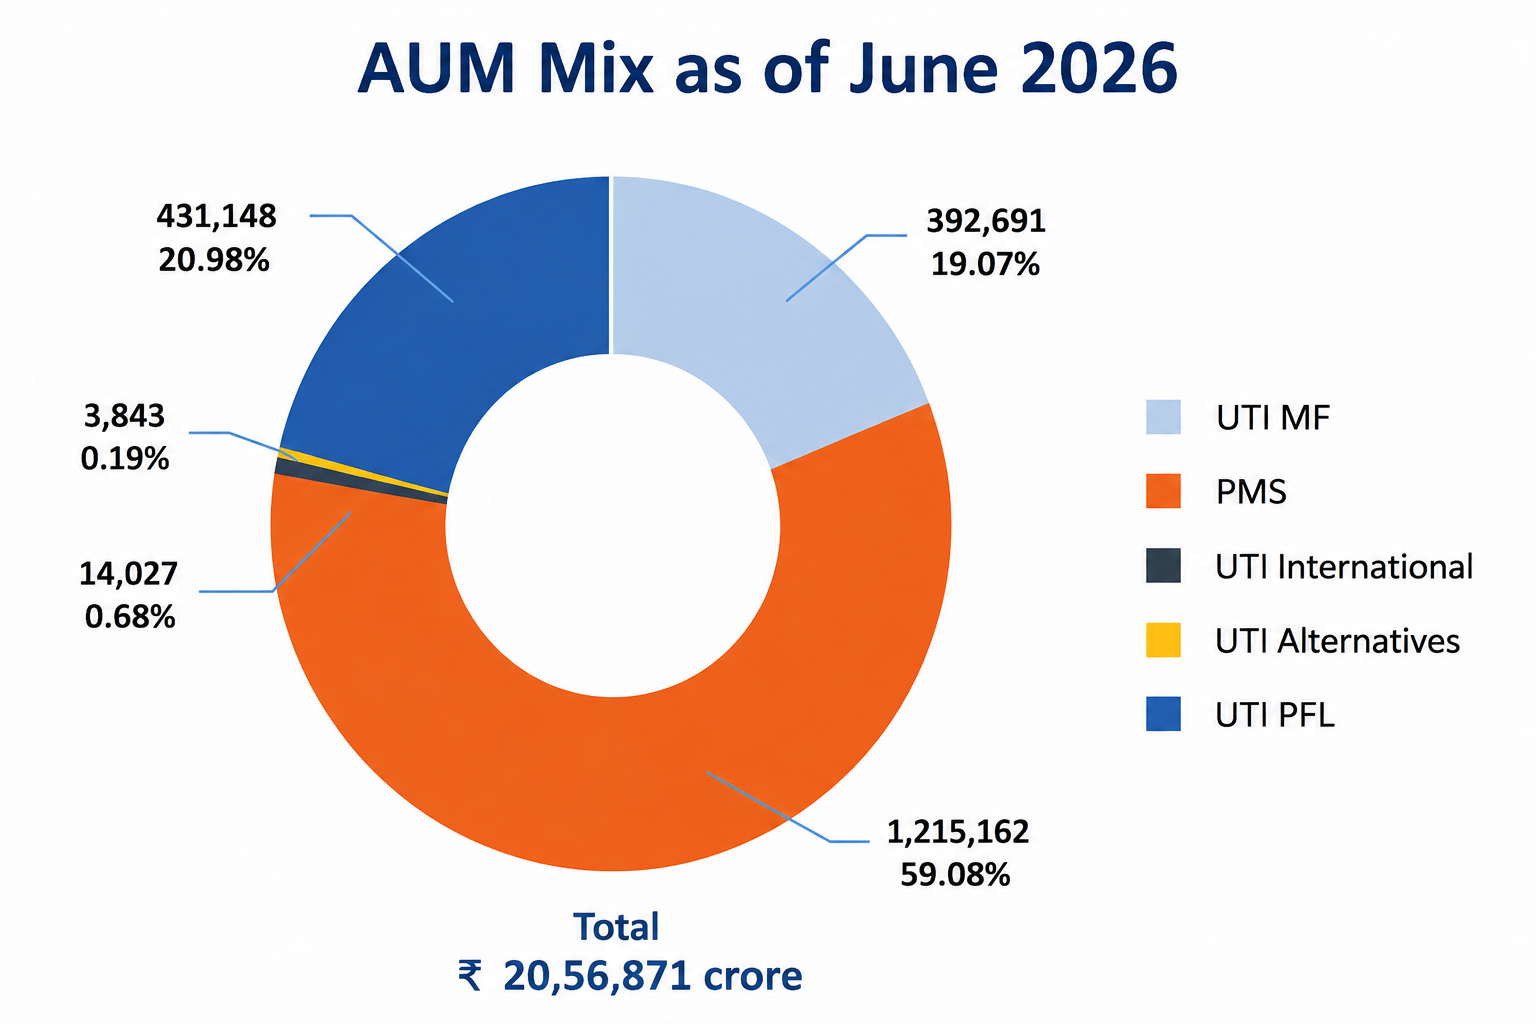
UTI MF’s business spans Mutual Fund and Portfolio Management Services (PMS), Pension Fund Management, Alternative Investment Funds and an international offshore footprint. With ₹12,15,162 crore AUM, the PMS is the largest block, accounting for 59.1% of the group AUM of ₹20.6 lakh crore.
Within PMS, UTI AMC manages retirement funds, including the Employees’ Provident Fund Organisation and the Coal Mines Provident Fund Organisation, and a non-discretionary mandate for the Directorate of Postal Life Insurance. Similarly, the company manages ₹4,31,148 crore of pension funds and is the second largest business.
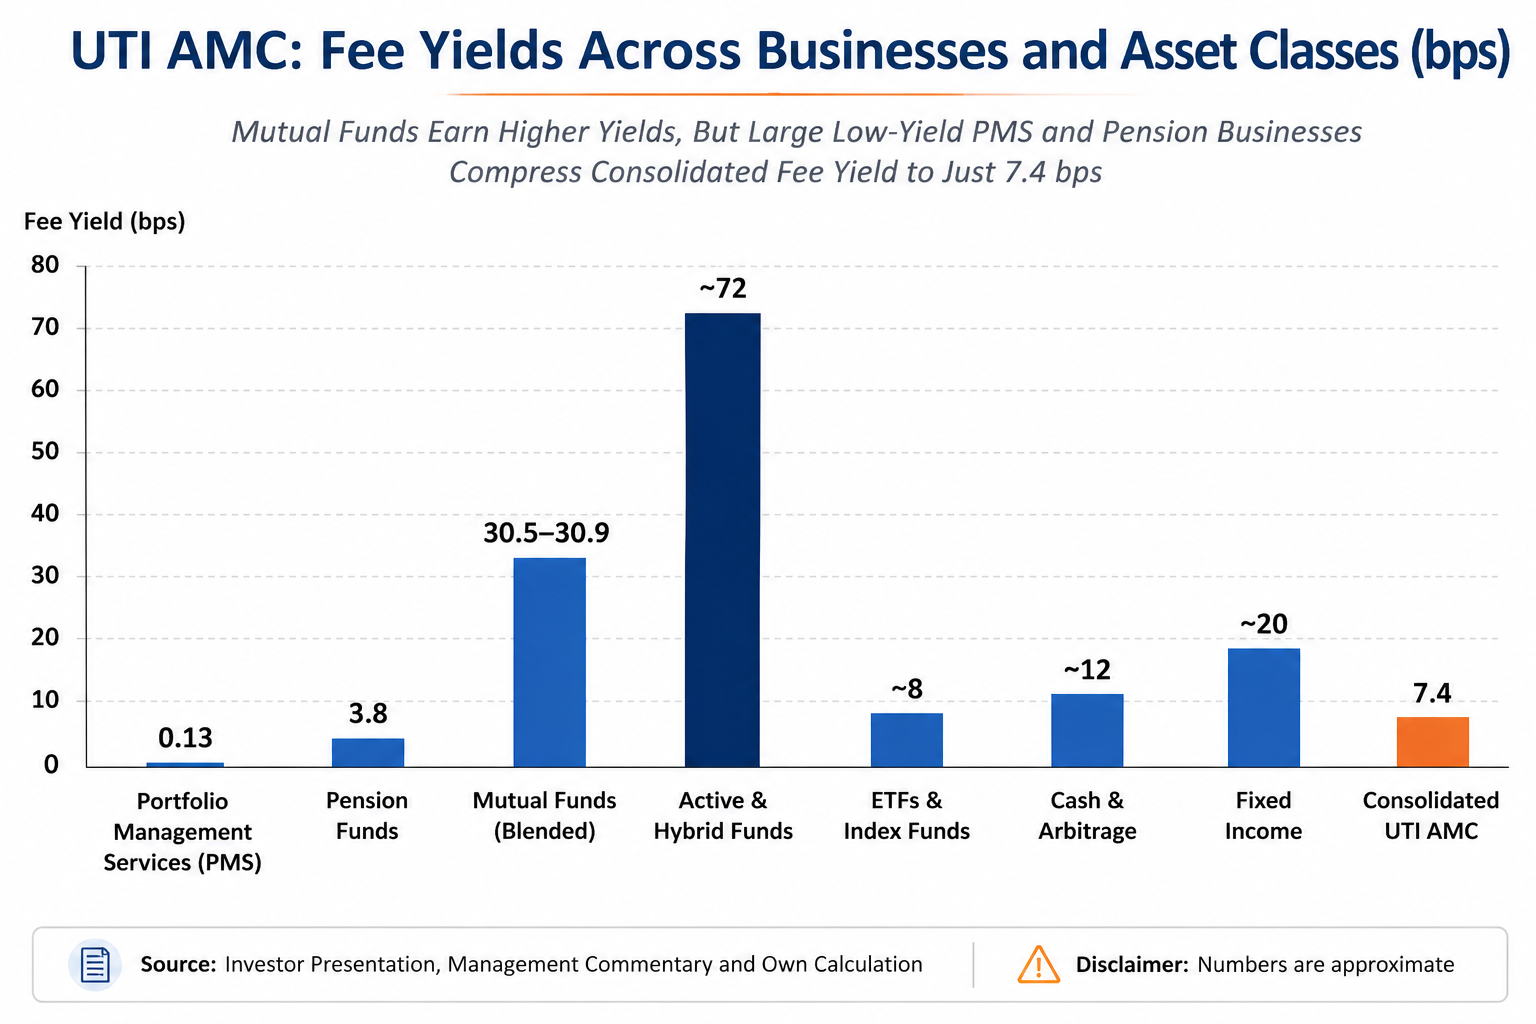
This represents a 24.2% market share of the total National Pension System industry. Although these two segments account for 80% of UTI AMC’s AUM, their low fee realisation (PMS: 0.13 bps and pension funds: 3.8 bps) means they contribute very little to the company’s revenue.
The Yield Squeeze: Why Massive AUM Doesn’t Equal Massive Revenue
Further, mutual funds with a quarterly average AUM (QAAUM) of ₹3,92,691 crore constitute a smaller (19.1%) part of the AUM mix. The company offers 84 mutual fund schemes spanning equity, hybrid, fixed income, and passive strategies. As of Q1FY27, UTI MF holds a 4.7% market share of the Indian mutual fund industry’s QAAUM.
The Passive Asset Drag: How ETFs and Index Funds Dilute Overall Yield
Equity assets contribute 70% of UTI’s total average mutual fund AUM. This is higher than the industry average equity-to-non-equity ratio of 62:38. However, this advantage is reduced because ETFs and index funds (yield: 8 bps) account for 45.8% of AUM. Active and hybrid funds, which offer a higher yield of around 72 bps, account for only 32.7% of AUM.
The SIP Moat: How 10-Year Retail Commitments Stabilise the Book
Systematic Investment Plans (SIPs) continue to be a key driver of UTI AMC’s AUM, helping build sticky retail assets. SIP AUM grew by 8.1% year-on-year as of June 2026 to ₹45,595 crore. Notably, 97% of the book is over 5 years and 93% is over 10 years. This demonstrates investors’ long-term commitment, making it a sticky business for UTI.
The Blended Yield Squeeze: Navigating the 7.4 Bps Consolidated Reality
Cash and arbitrage (12.3% of AUM) and fixed income (9.2%) also have lower yields of 12 bps and 20 bps, respectively. The higher share of lower-yielding assets effectively reduces the mutual fund’s blended yield to around 30.5-30.9 bps. This further compresses the consolidated fee yield to just 7.4 bps, as PMS and pension funds command significantly lower fee realisations.
Earnings Squeeze: Unpacking the 3% Profit CAGR Over Three Years
Historical financials also reflect the trend.Over the last three years, the company’s consolidated net profit grew at just 2.4% CAGR, reaching ₹472 crore in FY26. Revenue has grown at a faster 10.4% CAGR to ₹1,705 crore. Operating profit increased to ₹816 crore in FY26 from ₹612 crore in FY23, while margins stood flat at 48% in FY26.
The slower growth in profitability has resulted in Return on Capital Employed (ROCE) declining to 11% from 12% in FY23, reflecting subdued returns on capital employed.
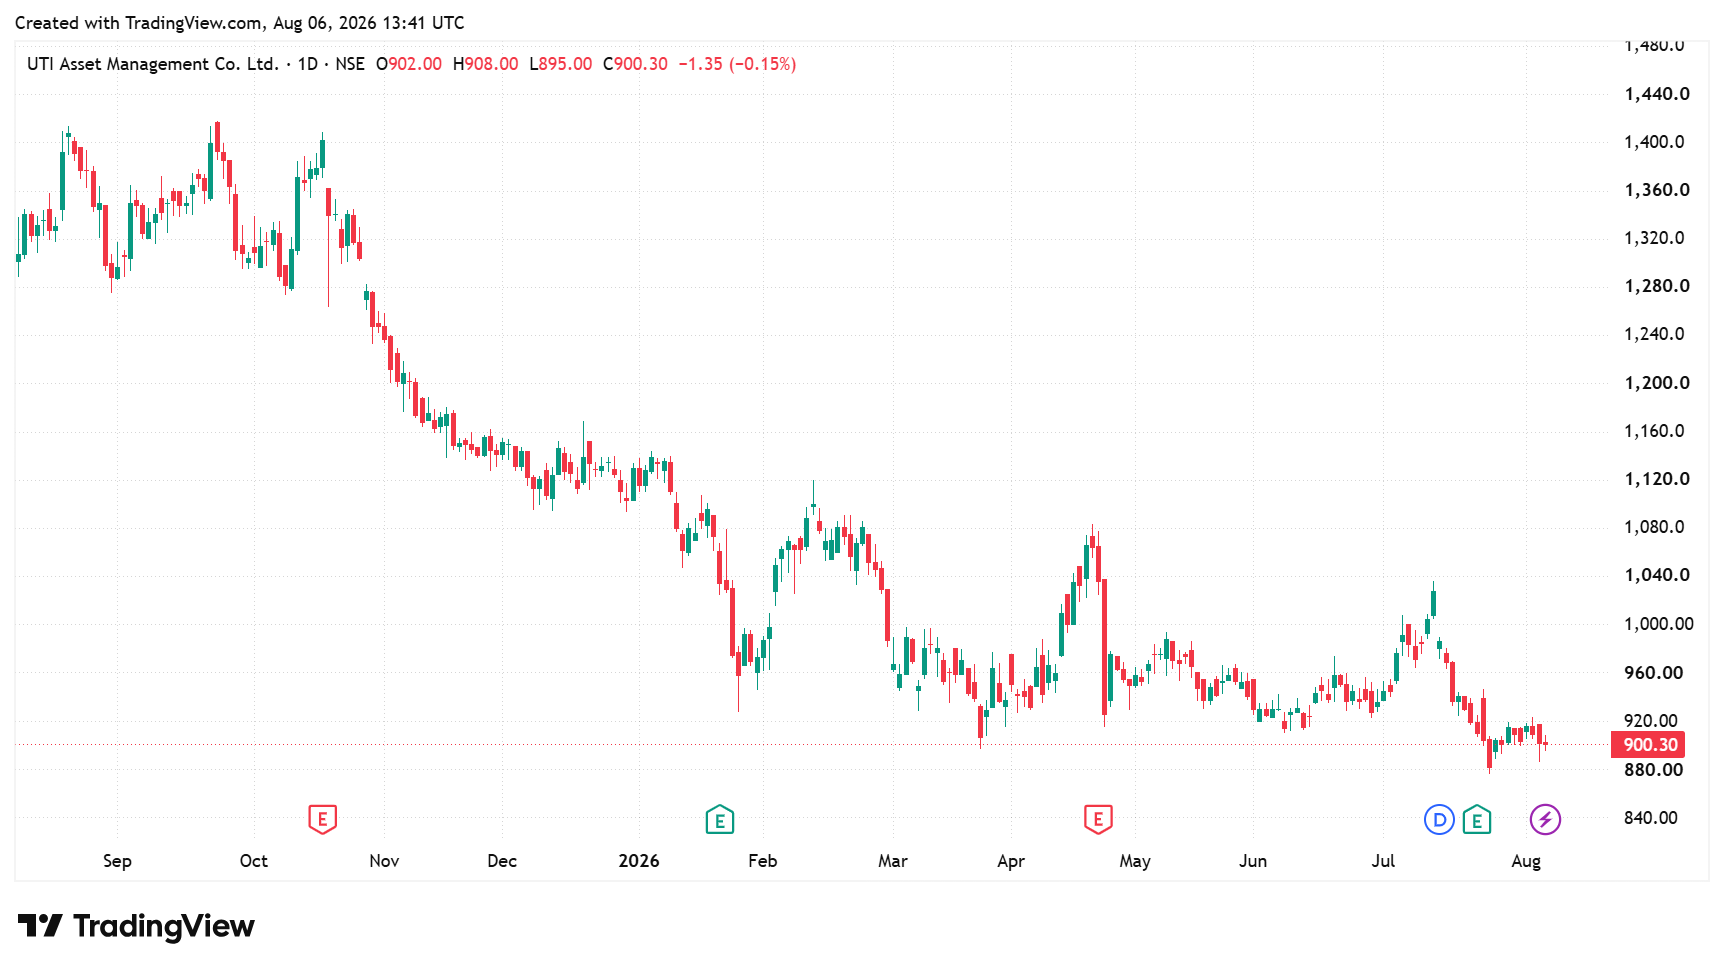
The company’s market cap is ₹11,660 crore, as of 06 August 2026.
Financials Strengthen in Q1FY27 Despite AUM Dip
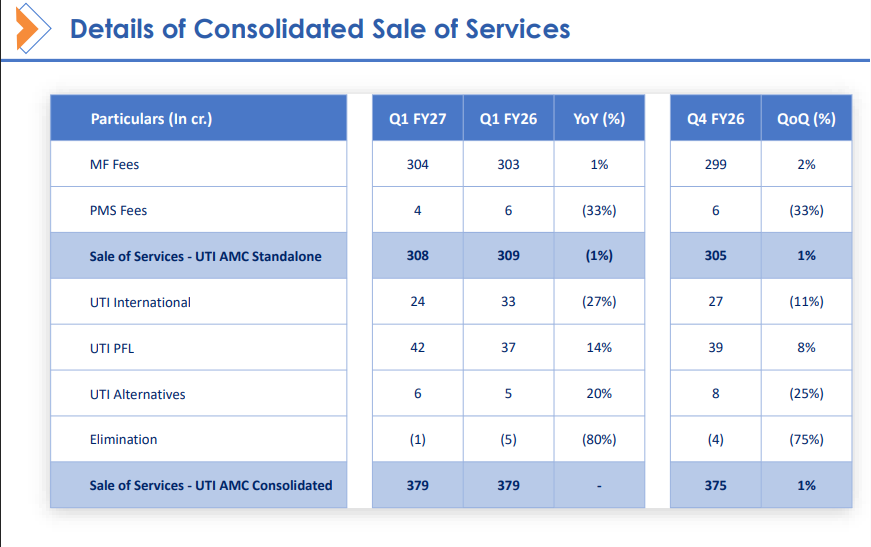
The company’s revenue in Q1FY27 increased by 6.7% year-on-year to ₹584 crore while total group AUM fell by 6.2%. Of this, revenue from sale of services remained flat at ₹379 crore, which includes mutual fund fees (₹304 crore), PMS fees (₹4 crore), UTI International (₹24 crore), UTI PFL (₹42 crore), UTI Alternatives (₹6 crore) and eliminations (₹1 crore).
Revenue growth was mainly driven by 22% mark-to-market gains during the quarter. However, operating profit rose 12.6% to ₹383 crore while margins expanded by 400 bps to 66%. As a result, net profit surged 15.7% to ₹294 crore.
The revenue mix also shows that PMS (₹4 crore) and pension funds (₹42 crore) generate very little revenue, even though they contribute a large share to AUM. On the other hand, mutual funds contribute the most due to their higher yields.
Where the Cash Goes: Analysing UTI AMC’s Capital Allocation
UTI AMC converts a major portion of its profit into cash flows, given its asset-light business. This explains why, despite modest revenue growth, it continues to generate strong absolute profits and convert a big portion of them into cash flows that can be returned to shareholders.
For example, the company converted 86.1% of its FY26 consolidated net profit (₹472 crore) into operating cash flow of ₹406.5 crore. Of the cash generated, the company deployed a net ₹33.8 crore towards investing activities and ₹593.9 crore towards financing activities.
Most of the financing outflow was driven by dividend payments of ₹614.9 crore, along with ₹13.2 crore in interest payments. This was partly offset by ₹35.8 crore received from the sale of shares. However, because the dividend payment exceeded the cash generated by UTI, the company’s net cash flow for the year was negative at ₹221.2 crore, compared with ₹105.9 crore in FY25.
As a result, the company’s cash and cash equivalents declined from ₹256.8 crore in FY25 to ₹35.6 crore in FY26. However, the bank balance (excluding ₹35.6 crore) increased from ₹247.7 crore in FY25 to ₹408.5 crore. This translates to strong liquidity of ₹444 crore as of FY26 end. Strong and consistent free cash flow generation is the core driver behind this.
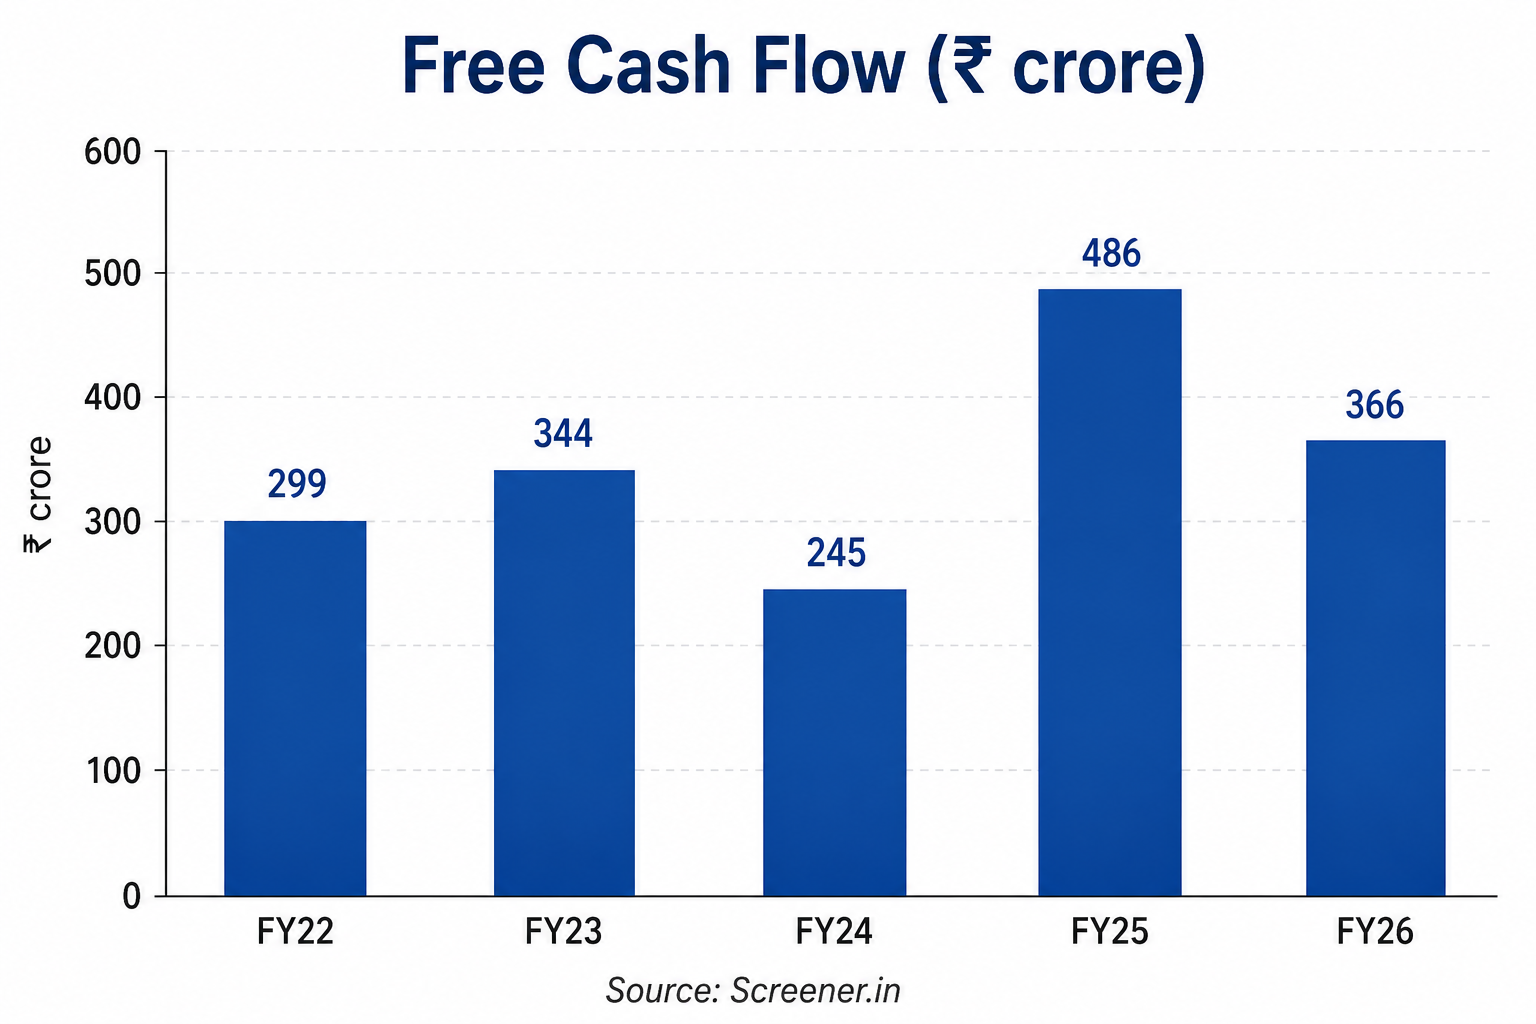
Because the business requires very little capex, it has been generating free cash flow for over a decade. Free cash flow stood at ₹366 crore in FY26, down from ₹486 crore in FY25, but higher than ₹245 crore in FY24. This demonstrates UTI AMC’s ability to consistently generate surplus cash, providing a strong foundation for sustaining its high dividend payouts.
Decoding the ₹40 Record Payout: UTI AMC’s Distribution Strategy
Regarding its dividend per share, the company has paid ₹40 per share (95% dividend payout) for FY26. This implies a dividend yield of 4.4% as per the share price of ₹900 on 6 August 2026. The historical track record is also strong and consistent.
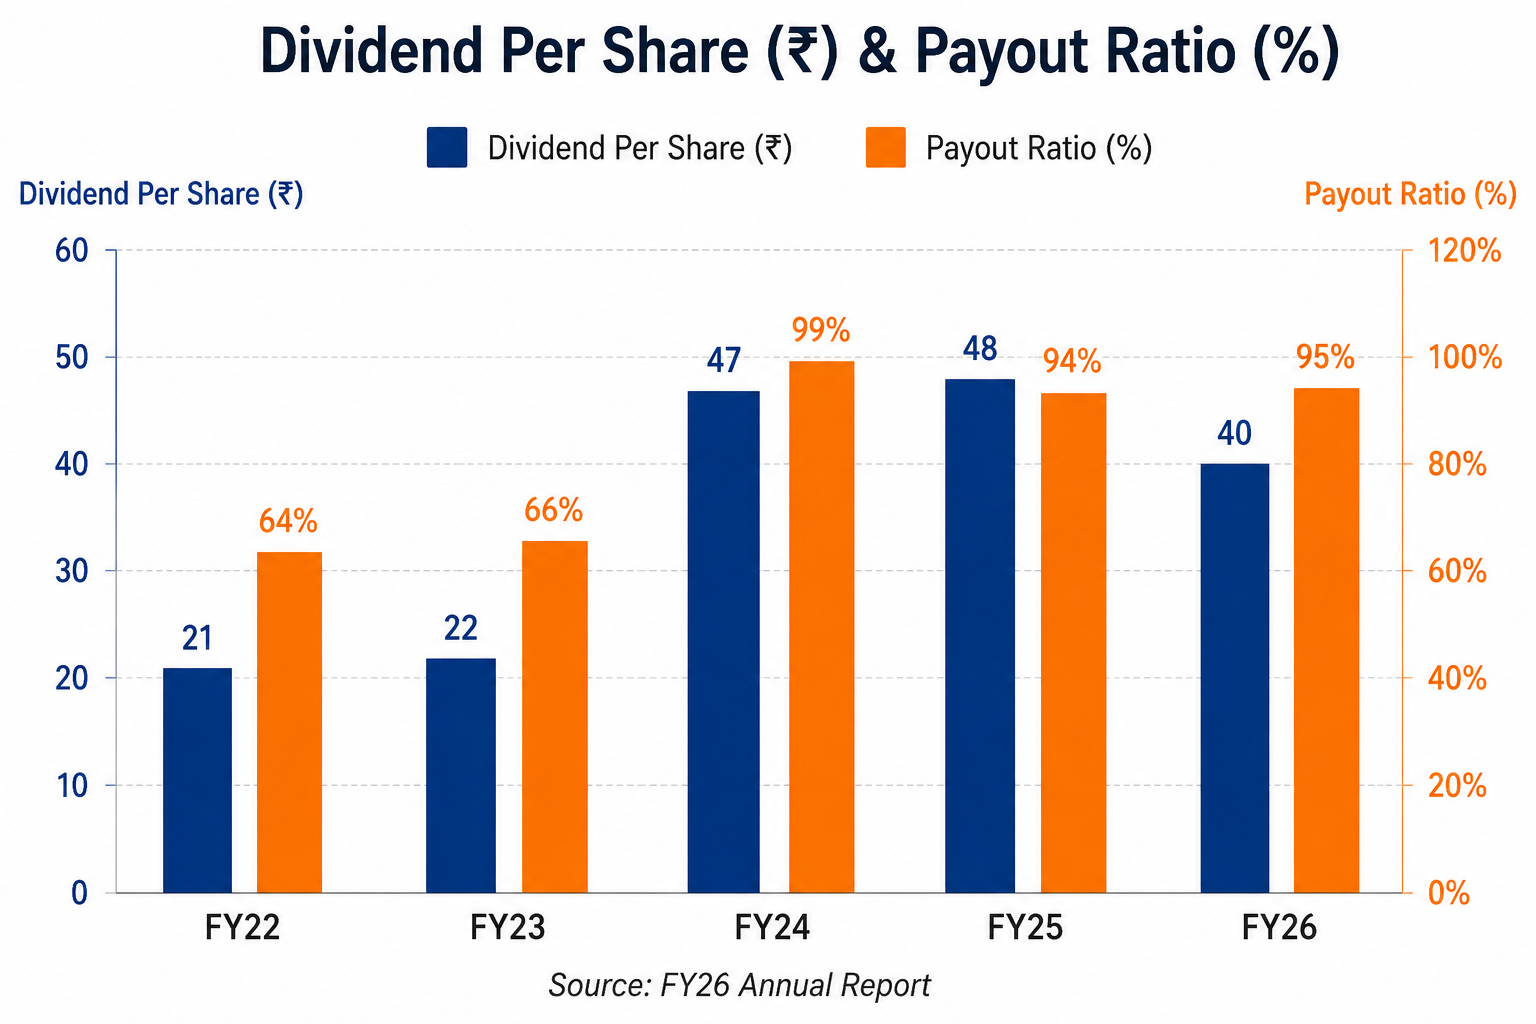
The company paid ₹48 (including special dividend of ₹22) as dividend in FY25, ₹47 in FY24, ₹22 in FY23 and ₹21 in FY22. The company mostly pays a final dividend every year. The dividend payout ratio increased from 64% in FY22 to 99% in FY24 and stood at 95% in FY26.
This indicates that the company is distributing most of its profits to shareholders as dividends. Also, the payout can even increase with the company’s profitability growth. This is because, from FY24, UTI AMC has shifted its distribution to 94-100% of standalone profit. Management has also recently reaffirmed that this run-rate will continue.
The Valuation Disconnect: Why Competitors Command Premium P/E Multiples
Valuation-wise, UTI AMC trades at a Price-to-Earnings multiple of 21.6x, slightly above its 5-year historical median (20x). However, this valuation is at a significant discount to larger players like ICICI AMC (43.4x), SBI Funds Management (37.3x), HDFC AMC (36.9x), Nippon Life (46.4x), Aditya AMC (29x), and even relatively smaller player Canara Robeco (24x).
The valuation discount is structural, driven by both slower earnings growth and UTI AMC’s business mix, where a large share of its AUM is concentrated in low-fee PMS and pension mandates. Even in mutual funds, a higher proportion of passive assets weighs on realisation. In contrast, peers have greater exposure to higher-yielding active equity funds, supporting faster earnings growth and premium valuations.
The Dividend Hunter Verdict
In short, UTI AMC could sustain its dividend payouts. The company’s asset-light AMC business has been generating remarkably strong, steady cash flows. This cash conversion allows it to cover its substantial annual dividend payouts while keeping its core reserves intact.
The company’s strong reserves (₹4,376 crore), investments of ₹3,988 crore, and a net debt-free balance sheet ensure that its capital distribution model remains insulated from market cyclicality. Further, the management’s clear target to maintain a dividend payout ratio in excess of 95% suggests that UTI AMC is likely to continue rewarding its shareholders.
Dividend hunters should add this stock to their watchlist.
Disclaimer:
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation and conference call. Only in cases where the data were unavailable have we used an alternative, widely accepted source of information.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
About the Author: Madhvendra has been deeply immersed in the equity markets for over seven years, combining his passion for investing with his expertise in financial writing. With a knack for simplifying complex concepts, he enjoys sharing his honest perspectives on startups, listed Indian companies, and macroeconomic trends.
A dedicated reader and storyteller, Madhvendra thrives on uncovering insights that inspire his audience to deepen their understanding of the financial world.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, their employees (s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities, or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources, and only after consulting such independent advisors as may be necessary.