



Welcome to the latest edition of Dividend Hunter. Over the past few weeks, we have analysed companies where strong cash flows could translate into consistent dividends going forward. In our previous edition, we covered one of India’s premier Asset Management Companiesoffering a 4.4% yield.
Today, we discuss India’s largest telecom infrastructure provider. The company designs, builds, owns, and maintains the physical mobile phone towers you see across the country. In simple terms, the company is a landlord for mobile network operators such as Airtel, Reliance Jio, and Vodafone Idea.
The company we focus on is Indus Towers Limited, a Bharti Airtel-promoted entity and India’s premier telecom infrastructure company.
As of 30 June, 2026, Indus Towers operates a network of 2.67 lakh towers and 4.32 lakh macro co-locations. It serves all major telecom service providers across all 22 circles spanning 36 states and Union Territories.
The company builds a single shared tower and rents space on it to multiple telecom companies at the same time. These telecom players bring in and install their own electronic equipment, such as transmitters, antennas, and microwave links, which send wireless signals directly to your smartphone.
Join now
This sharing arrangement is also known as a co-location model. This saves telecom companies substantial capital in setup costs and helps them expand their network coverage much faster. It is also much better for the environment because it prevents communities from being cluttered with duplicate towers.
Notably, Indus Towers secures its business through long-term Master Service Agreements with telecom operators. These contracts typically run for many years and include price escalation clauses, giving the company stable and predictable cash flows.
Operating Leverage: Maximising Margins Through the Tenancy Model
This business model offers significant economies of scale. Once a tower is built, the cost of adding a second or third tenant (co-location) is extremely low. As a result, almost all rent from additional tenants goes straight to profit.
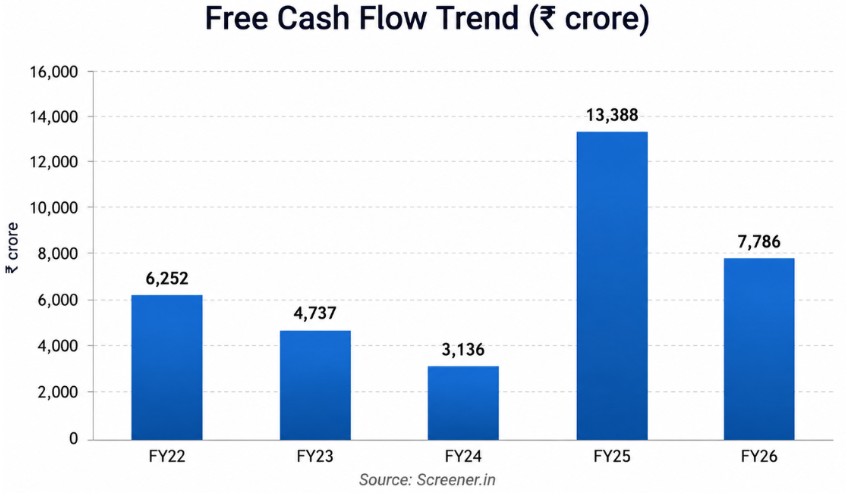
This results in a higher return on initial investment and supports the bottom line and free cash flow. Free cash flow of ₹7,786 crore in FY26 highlights the business’s cash-generating ability. Even before FY26, Indus Towers had a history of generating free cash. Despite this, it paused declaring dividends for three years due to high receivables from a major telecom company.
However, that customer cleared all those historical dues during FY25, improving Indus’s cash position. This enabled Indus Towers to resume dividend payments, with the company declaring a dividend of ₹14 per share in FY26.
This marks a return to shareholder distributions under a formal Dividend Distribution Policy that aims to balance rewarding shareholders with maintaining cash and reserves for business growth, capital allocation, and expansion.
The key question is whether this resumption of payouts can be sustained. We have tried to find out by analysing the company’s profitability, cash flows, balance sheet, and, of course, its dividend distribution policy. But first, let’s start with the numbers.
Indus Towers Q1FY27 Results: Balancing 53.6% Margins with Modest Profit Growth
Over the last five years, the company’s consolidated revenue has grown at a 18% CAGR to ₹32,493 crore, while net profit has grown at a 13% CAGR to ₹7,145 crore in FY26.
Revenue in Q1FY27 increased 4.6% year-on-year to ₹8,431 crore, led by a 5.2% increase in rental revenue. EBITDA (earnings before interest, tax, depreciation, and amortisation) grew 3% to ₹4,520 crore, while margins fell 150 bps to 53.6%.
However, net profit increased only 0.5% to ₹1,746 crore. The Return on Capital Employed stands at 19.5% and Return on Equity at 18.6%, highlighting the business’s efficient operations.
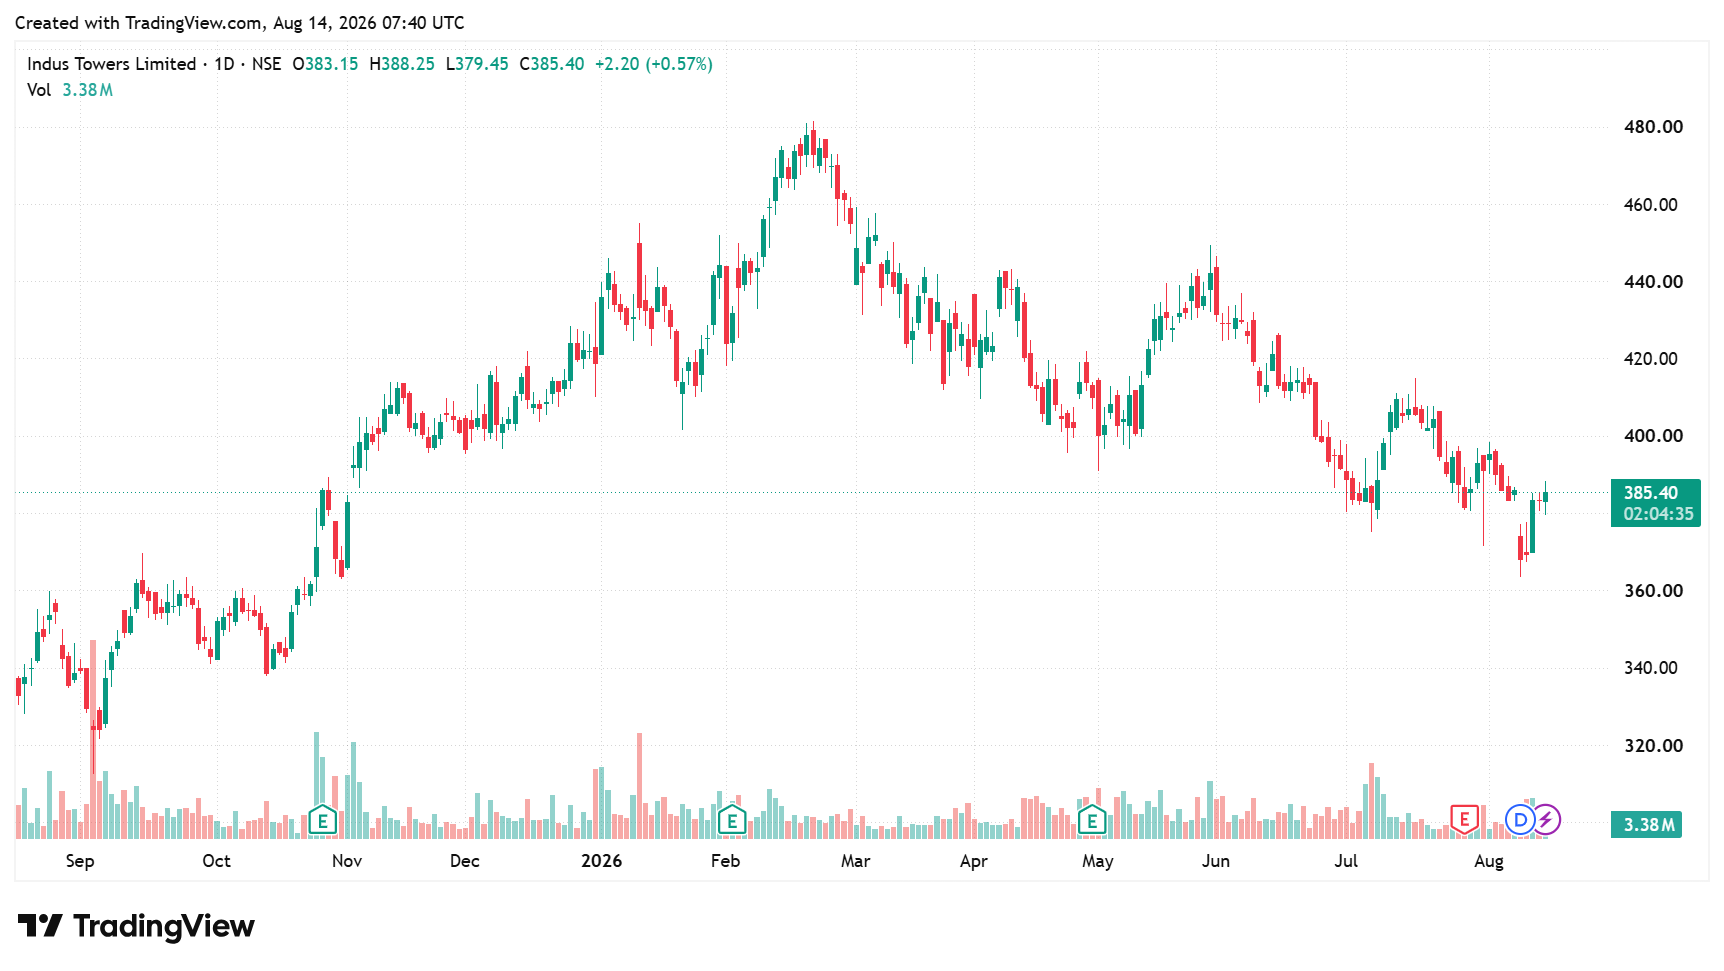
The company’s market cap is ₹1,01,767 crore, as of 14 August 2026.
₹15,684 Crore Operating Cash: Balancing 5G Network Capex with Indus Towers Dividends
Indus Towers converts a substantial portion of its profits into cash flows.
For example, the company converted its FY26 consolidated net profit of ₹7,145 crore into a cash flow from operating activities of ₹15,684 crore. This high conversion is primarily supported by large non-cash charges, notably depreciation and amortisation of ₹7,140.8 crore.
Capital Allocation Strategy
Of the operating cash generated, the company deployed a net ₹10,198 crore towards investing activities and ₹5,588.1 crore towards financing activities. Most of the investing outflow was driven by heavy capital expenditure on network expansion and capacity upgrades. As a result, the business saw a net cash outflow of ₹102 crore.
Still, the company generated ₹7,786 crore in free cash flow, down from ₹13,388 crore in FY25. Despite long-term capital needs for tower setups, the business has consistently generated cash for over a decade. Under the dividend distribution policy, distributions are closely linked to cash generation, as the company aims to return surplus Free Cash Flow.
Decoding the 3.6% Indus Towers Dividend Yield and Payout Strategy
Regarding its dividend per share, the company has paid ₹14 per share (52% dividend payout) for FY26. This implies a dividend yield of 3.6% based on a share price of ₹385 on 14 August 2026. The company had a consistent track record of paying dividends before suspending them due to elevated receivables from Vodafone Idea.
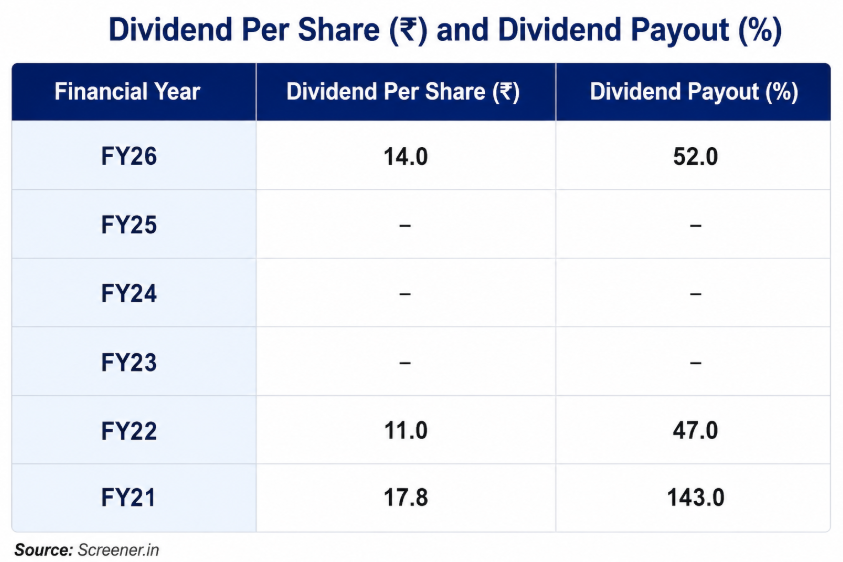
During FY15-22, the company paid an average 87.7% of its net profit as dividends, with more than 100% payout in five years. This indicates that the company usually distributed most of its profits to shareholders as dividends. The company’s dividend in FY22 stood at ₹11 per share and ₹17.8 in FY21 (142% payout).
Now that it has resumed dividend payments, its dividend distribution policy commits to rewarding shareholders with consistent, increasing dividends over time. This implies that increased profits could lead to higher dividends.
The ₹6,770Cr Catalyst: Clearing Receivables to Unlock Cash
The turning point came in FY25, when a large customer cleared past-due receivables of ₹5,100 crore. This helped the company’s net cash flow from operating activities rise 70% year-on-year to ₹19,645 crore at the end of FY25.
This improvement was primarily driven by the release of cash tied up in trade receivables. In FY25, trade receivables decreased by ₹6,770 crore in total, compared to an increase of ₹1,505.2 crore in FY24. This substantial recovery reflects higher cash collections from debtors, including a large portion from that major customer.
This collection improved the company’s financial position, driving FY25 Free Cash Flow to ₹13,388 crore and clearing the way for future payouts. Further, dividend payouts are kept independent from major capital investments. For instance, the company’s expansion in Africa is anticipated to be debt-funded to avoid impacting or reducing the Free Cash Flow available for domestic dividends.
The customer that delayed the payment in the past continues to account for a high portion of Indus’s outstanding trade receivables and unbilled revenue as of March 31, 2026. This is standard receivables generated in the normal course of business.
For instance, the company’s unbilled revenue stood at ₹3,973.3 crore. Of this, ₹2,367.5 crore belongs mainly to Bharti Airtel. The remaining ₹1,605.8 crore largely reflects exposure to other operators, primarily the one that had defaulted in the past. Management stated that this customer has been paying its monthly billing regularly and believes it will fully recover the dues in the normal course of business.
Riding the 5G Data Surge: Indus Towers Expands Indoor Coverage Networks
Looking ahead, management has confirmed a robust order book over the next four quarters. This demand comes from a combination of direct network expansion by major customers and the strategic shift of customers’ expired tenancy portfolios to Indus.
Further, with 5G traffic surging to 43% of total data consumption in Q4 FY26 (up from 30% in Q4 FY25), telecom players are expected to invest heavily in network capacity. This could continue to generate a sustained stream of loading revenues for Indus.
To expand its addressable market, the company is aggressively scaling up in high-growth indoor coverage spaces. It has achieved leadership in In-building Solutions and is deploying Distributed Antenna Systems across metro networks, railways, highways, and commercial places.
The African Expansion Gameplan: Securing Global Telecom Infrastructure Revenue
Indus Towers is expanding into Africa’s growing digital infrastructure market. It has obtained regulatory approvals and operating licenses in Nigeria, Uganda, and Zambia. Post-rollout in Q2FY27, management expects to scale up progressively across these markets.
Indus is leveraging its core operational expertise, with Bharti Airtel as an anchor tenant from day one. The company is currently finalising Master Service Agreements and commercial rate cards. Management expects to recover its cost of capital even with a single tenant. As second and third tenants are added over time, operating leverage can help profitability.
Valuation Analysis: Evaluating the Indus Towers Share Price and P/E Multiple
Valuation-wise, Indus Towers trades at a Price-to-Earnings multiple of 14.2x, at a premium to its 5-year historical median (12.8x) but almost in line with Telecom Infrastructure’s industry P/E of 14.5x. Indus Towers has no direct listed peer.
The Dividend Hunter Verdict
Indus Towers is well-positioned to sustain its recommended dividend payouts. The company’s infrastructure generates strong, steady operating cash flows. This robust cash conversion allows the company to comfortably cover its reinstated annual dividend payout.
Its strong reserves of ₹37,008 crore, cash and cash equivalents (₹473 crore), other bank balances (₹1,505 crore), and debt-funded overseas expansion ensure that its capital distribution model remains insulated from temporary industry headwinds. This suggests Indus Towers could potentially continue to reward shareholders consistently over the long term.
Dividend hunters should keep this stock on their watchlist.
Disclaimer:
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation and conference call. We used an alternative, widely accepted source of information only when the data were unavailable.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, we strongly advise you to consult your advisor. This article is strictly for educational purposes only.
About the Author: Madhvendra has been deeply immersed in the equity markets for over seven years, combining his passion for investing with his expertise in financial writing. With a knack for simplifying complex concepts, he enjoys sharing his honest perspectives on startups, listed Indian companies, and macroeconomic trends.
A dedicated reader and storyteller, Madhvendra thrives on uncovering insights that inspire his audience to deepen their understanding of the financial world.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, their employees (s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities, or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives and resources, and only after consulting any independent advisors as necessary.