



Artificial Intelligence (AI) is no longer just driving demand for chips and computing power. It is triggering a massive buildout of the physical infrastructure needed to support it.
US hyperscalers are expected to spend around US$700 billion (bn) in capex in CY26. The scale of this spending is changing the data centre landscape.
Global data center capacity is projected to nearly double from 103 gigawatts (GW) to 200 GW by 2030, with JLL estimating that the AI investment super cycle could exceed US$ 3 trillion.
AI models are becoming larger, requiring computing clusters with tens of thousands of GPUs. That, in turn, is creating a parallel need for reliable power generation and high-speed connectivity.
The opportunity is extending well beyond data center operators. As this buildout accelerates, companies supplying the power and connectivity infrastructure could become important players.
We examine two data center stocks with a significant presence in the US market. Both companies are positioned at different layers of the data-center infrastructure buildout. TD Power Systems (TDPS) addresses power, while Sterlite Technologies (STL) addresses connectivity.
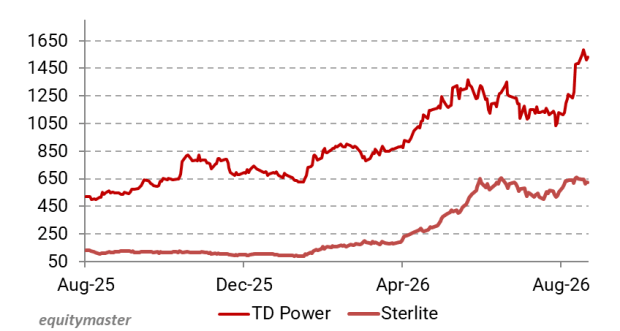
Share Price Performance – 1 Year
About the Company
TD Power Systems (TDPS) Is a heavy engineering manufacturer specialising in AC generators and motors.
The company designs and manufactures power-generation equipment. The company caters to both conventional energy (steam, gas, and diesel) and renewable energy applications (hydro, wind, and geothermal).
Its product portfolio includes steam turbine generators (up to 250 MW), gas turbine generators (up to 250 MVA), hydro generators (up to 45 MW), and diesel/gas engine generators (up to 25 MVA).
TDPS also supplies specialised industrial and traction motors for sectors like oil & gas, steel, and railways.
Unlike TDPS, STL manufactures optical fibre. It is a global market leader in digital connectivity infrastructure and advanced optical connectivity solutions.
As India’s #1 end-to-end optical manufacturer, STL holds a 9% global market share in optical fibre cables (excluding China).
Two Ways to Play the Data Center Power Boom
Data centers require an uninterrupted flow of electricity. Local power grids often struggle to supply enough energy, so data centers are increasingly building their own mini power plants on-site. This is called ‘behind-the-meter’ power generation.
TDPS caters exactly to this market. The company manufactures heavy-duty AC generators. These generators connect directly to gas engines and gas turbines to provide continuous, reliable on-site power. This ensures the servers never shut down.
TDPS doesn’t deal directly with tech players. Instead, it sells to manufacturers of heavy engines and turbines (known as OEMs). These OEMs buy its generators, assemble them into full power plants, and deliver them to US data centres.
Management says the gas turbine and gas engine business is its strongest-performing segment. This growth is driven by AI and data center applications in the United States.
Notably, a complete on-site power plant represents less than 5% of a data center’s total building cost. As having electricity is an absolute necessity, data center builders are willing to pay whatever it takes to get these generators quickly, making them highly price-inelastic.
It has also signed a 10-year Build-to-Print manufacturing agreement with Siemens Energy to manufacture 2-pole generators.
TDPS has won orders from a major US-based gas turbine OEM. It has a strong expected pipeline with a second major global OEM for 12-19 MW generators specifically for US data center programs. The company doesn’t disclose data-center revenue separately.
On the other hand, STL designs, manufactures, and installs the dense fibre cables and connectors. These products link the chips inside the server racks and connect different data centres to one another.
The company serves hyperscalers, neo-cloud providers and regional data center operators. For example, a leading developer chose STL to link an upcoming 25 MW data center in Kolkata, and another major hyperscaler is using STL’s cabling in Mumbai.
STL’s product portfolio includes Neuralis, NMC Pre-Terminated Solutions and Celesta IBR Cables.
Strong Data Center Exposure Starts Showing Up in Earnings
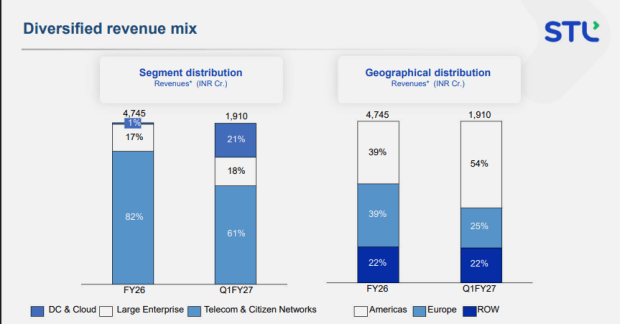
In Q1FY27, STL’s Data Center & Cloud segment contribution reached 21% of total revenue, up from just 1% in FY26. This was driven by a rapid buildout of the global AI infrastructure.
Notably, the tailored fibre and connectivity solutions engineered for the data center segment yield significantly higher margins than traditional telecom cabling.
This high-margin business mix was a primary driver of STL’s financial turnaround in Q1FY27. The company’s revenue rose 87% year-on-year to Rs 19.1 bn. EBITDA grew 184% to approximately Rs 4 bn, yielding a margin of 20.8%.
The margin is the highest the company has achieved in nearly 20 quarters. Consequently, net profit expanded 19.7 to Rs 1,970 m.
In Q1FY27, STL increased its attach rate to 16% from 15% in FY26. Attach rate measures the ratio of higher-margin optical connectivity (such as pre-terminated modular cabinets, connectors, and patch cords) revenue to basic optical fiber cable revenue.
Source: STL Investor Presentation
A high attach rate means a greater proportion of revenue comes from higher-value optical connectivity products relative to basic fibre cable products.
STL has pivoted toward the US hyperscale and AI data center buildout. Revenue contribution from the Americas region surged to 54% in Q1FY27, up from 39% in FY26.
The company’s FY26 financials were also strong. Consolidated revenue grew 19% YoY to Rs 47.5 bn in FY26. EBITDA increased 39% to Rs 6.3 bn, while margins stood at 13.2%. Net Profit surged 178% to Rs 560 m.
| Q1FY27 Financial Metric (Consolidated) | STL | TD Power Systems |
| Revenue (Rs bn) | 19.1 | 6.4 |
| YoY Revenue Growth | 87% | 71% |
| EBITDA (Rs bn) | ~4.0 | 1.2 |
| YoY EBITDA Growth | 184% | 72% |
| EBITDA Margin | 20.8% | 19.0% |
| Net Profit (Rs million) | 1,970.0 | 860.0 |
| YoY Net Profit Growth | 19.7X | 72% |
| Order Backlog (Rs bn) | 186.2 | ~22.1 |
Source: Q1FY27 Investor Presentation
TD Power’s consolidated revenue, on the other hand, grew 71% YOY to Rs 6.4 bn in Q1FY27. EBITDA increased 72% to Rs 1.2 bn, while margins stood at 19%. Net profit increased 72% to Rs 860 m.
The strong Q1FY27 earnings followed a similar financial growth in FY26. Revenue grew 45% YOY to Rs 18.6 bn in FY26. EBITDA increased 41% to Rs 3.4 n, while margins were at 18.3%. Net profit increased 37% to Rs 2,388 m.
This growth is currently being driven by high demand for gas turbines, gas engines, and generators, which are in short supply worldwide. TDPS is capturing this bottleneck.
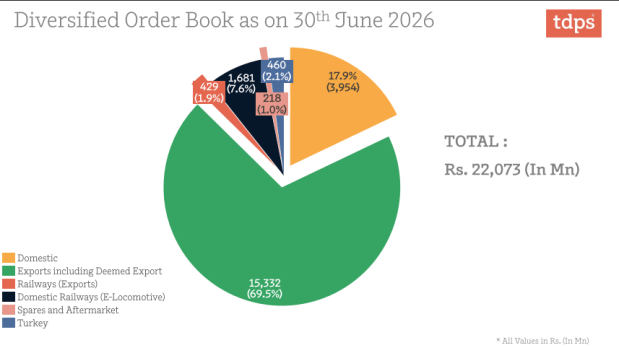
This is reflected in the standalone order book, where exports and deemed exports made up 93% (Rs 6.8 bn) of the Q1FY27 order inflows (Rs 7.3 bn). The American market (North, Central, and South America) is expanding at a very strong rate.
TDPS generators are enjoying partner acceptance due to competitive pricing and short lead times.
Capacity Expansion to Support the Next Growth Phase
The company’s current active capacity can execute about Rs 22 bn of revenue. To capture more growth, TDPS is investing Rs 0.5 bn in debottlenecking. This low-capex, high-efficiency move is expected to scale its peak revenue potential to Rs 32 bn by FY28.
Beyond that, TDPS is planning capacity additions to target Rs 40+ bn for FY29 and FY30.
Looking further ahead, TDPS is evaluating a factory expansion to push peak output capacity to Rs 40 bn and above by FY29-30. This will primarily involve expanding facilities for generators under the 100 MW design range.
Unlike TDPS’s need to build heavy-machinery floor space, STL’s immediate strategy focuses on fixed-asset sweating. The company is pushing its existing, globally distributed factories to cross 70% to 80% capacity utilisation.
However, STL has also planned to invest Rs 5 bn per year over the next three years to upgrade its manufacturing plants across glass, fibre, cabling, and connectivity.
The company is specifically aiming for 70%+ by the end of Q4FY27 to unlock operating leverage and volume expansion. STL is also leveraging its advanced optical fibre connectivity plant in South Carolina to serve the North American market.
This localised manufacturing gives STL a lead-time advantage over foreign competitors, as it can co-create custom solutions directly with US-based hyperscalers and neocloud providers.
Both companies are expanding not only their capacity but also their product portfolio.
Historically focused on mid-sized generators, TDPS is moving up the value chain. Through its dedicated R&D branch in the United Kingdom, the company is developing larger, utility-scale generators ranging from 40 MW to 200 MW.
Management has indicated TDPS is close to signing formal agreements with global parties to commercialise this large generator segment. This could open up new global utility and grid-scale opportunities.
To prioritise these high-margin, high-demand industrial generators and motors, it is deliberately phasing out its domestic railway traction motor business (refusing new orders) to free up physical factory capacity.
Meanwhile, STL expects its core business mix to shift permanently. Over the next few years, the high-margin Data Centre and Enterprise segment is projected to grow to 50% of total revenues.
The telecom operators and rural connectivity initiatives (like India’s BharatNet program) are expected to make up the other half. Management expects its optical connectivity attach rate to climb from 16% in Q1 FY27 to above 20% in Q2, and target 25%+ by the end of FY27.
STL is expanding its portfolio of high-density interconnect products. STL is net debt-free and aims to keep its Net Debt-to-EBITDA ratio below 1.2 for FY27.
Large Backlogs Strengthen the Growth Outlook
At the end of Q1FY27, TDPS’s cumulative manufacturing segment order book stood at Rs 22.1 bn. Of this, generator and motor manufacturing contributed Rs 19.3 bn.
Source: TDPS Investor Presentation
Management expects order inflows to sustain at a healthy rate of Rs 7 bn per quarter, translating to a full-year inflow target of over Rs 28 bn.
On the back of robust order inflows and strong Q1FY27 performance, TDPS has upgraded its FY27 revenue guidance to Rs 26 bn, up from earlier guidance of Rs 24 bn. EBITDA margin is expected to be between 18% and 19%.
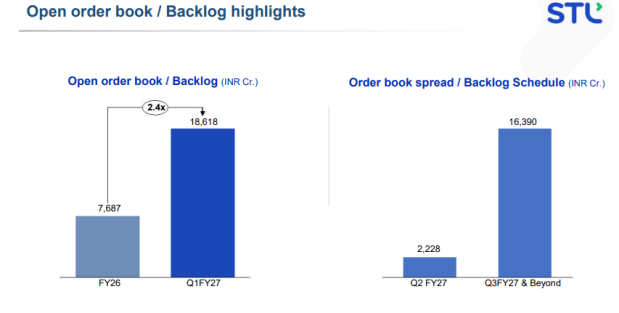
Like TDPS, STL also announced its highest-ever open order backlog of Rs 186.2 bn, up 2.4 times from Rs 76.9 bn in FY26. STL pulled in Rs 131 bn in new orders during Q1 alone.
Source: STL Investor Presentation
This backlog is heavily anchored by a US$ 1.11 bn order from a major global hyperscaler to supply optical connectivity products for AI data centres through FY29.
The company also received over US$ 100 m in direct orders for its specialised Neuralis data center portfolio. The company expects to execute Rs 22.3 bn worth of orders in Q2FY27, with the remainder in Q3FY27 and beyond. TDPS is also net debt-free.
Strong Growth Comes at a Premium Valuation
Both companies are trading at premium valuations, reflecting strong growth expectations and their exposure to structural data center and power infrastructure opportunities. However, the rerating has already priced in much of the expected growth.
STL trades at 38.2x EV/EBITDA, well above its three-year median of 14.9x, following a sharp improvement in profitability and a significant increase in its data center exposure.
TDPS trades at an even higher 59.1x EV/EBITDA, nearly twice its three-year median of 30.3x.
The premium valuations leave limited room for execution disappointments. The key question is therefore not whether the data center opportunity is attractive, but whether earnings growth can sustain the multiples.
STL offers stronger near-term earnings momentum and a substantial order backlog, while TDPS provides greater exposure to the power generation bottleneck.
At current valuations, both stocks warrant a focus on execution, order conversion and the pace at which capacity expansion translates into earnings.
Conclusion
The AI data center buildout is creating opportunities well beyond chips and computing infrastructure.
TD Power Systems and Sterlite Technologies are positioned at two different layers of this ecosystem. TDPS is addressing the growing need for reliable power, and STL rising demand for high-speed optical connectivity.
Both companies enter the next phase with strong earnings momentum and sizeable order backlogs.
However, the opportunity now comes with elevated valuations.
The key question going forward is whether sustained order growth, capacity expansion and improving profitability can support these premium multiples.
Instead of relying solely on hype, investors need to carefully analyse the company’s fundamentals, including financial performance, corporate governance practices, and growth strategies.
Happy investing.
Disclaimer: This article is for information purposes only. It is not a stock recommendation and should not be treated as such. Learn more about our recommendation services here…
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.