



India’s energy storage story is no longer limited to lithium-ion batteries. As the country builds domestic battery manufacturing, demand is also emerging for the chemicals and materials that sit behind these technologies.
Macro Catalyst: The 193,000-Tonne Cathode Opportunity
Niti Aayog estimates that India could need around 193,000 tonnes of Cathode Active Material every year by 2030 to support 100 gigawatt-hour (GWh) of annual battery manufacturing. It assumes that Lithium Iron Phosphate (LFP) could account for 60% of the demand for active cathode material. Currently, more than 98% of global LFP cathode material and LFP battery cells are produced in China, as per the International Energy Agency.
This monopoly creates major opportunities for companies to meet domestic demand and supports the China+1 shift. In battery manufacturing, Cathode Active Material is the key chemical mixture used to build the positive electrode (the cathode) of a battery cell.
Simultaneously, the Council of Scientific and Industrial Research and the Central Electrochemical Research Institute projected in May 2022 that demand for supercapacitors is growing at around 30% CAGR. Supercapacitors (also known as ultra-capacitors) are advanced energy storage devices that store electrical energy via electrochemical and electrostatic processes.
Join now
They have an unusually high power density, making them essential for Electric Vehicles, Solar and Renewable Energy, Smart Grids, and Consumer Electronics. Especially in electric vehicles, supercapacitors are used alongside Lithium batteries.
These trends point to a larger opportunity for companies supplying specialised materials to the energy storage ecosystem. This is where specialty chemical companies are finding a new growth avenue. Their existing chemical expertise can be adapted to emerging battery and energy storage technologies.
This would allow them to move into a market that could become increasingly important over the next decade. In this article, we look at two specialty chemical companies that are making this transition. Their technologies differ, but their strategy is similar. Both are using their existing chemistry capabilities to build a presence in India’s evolving energy storage value chain.
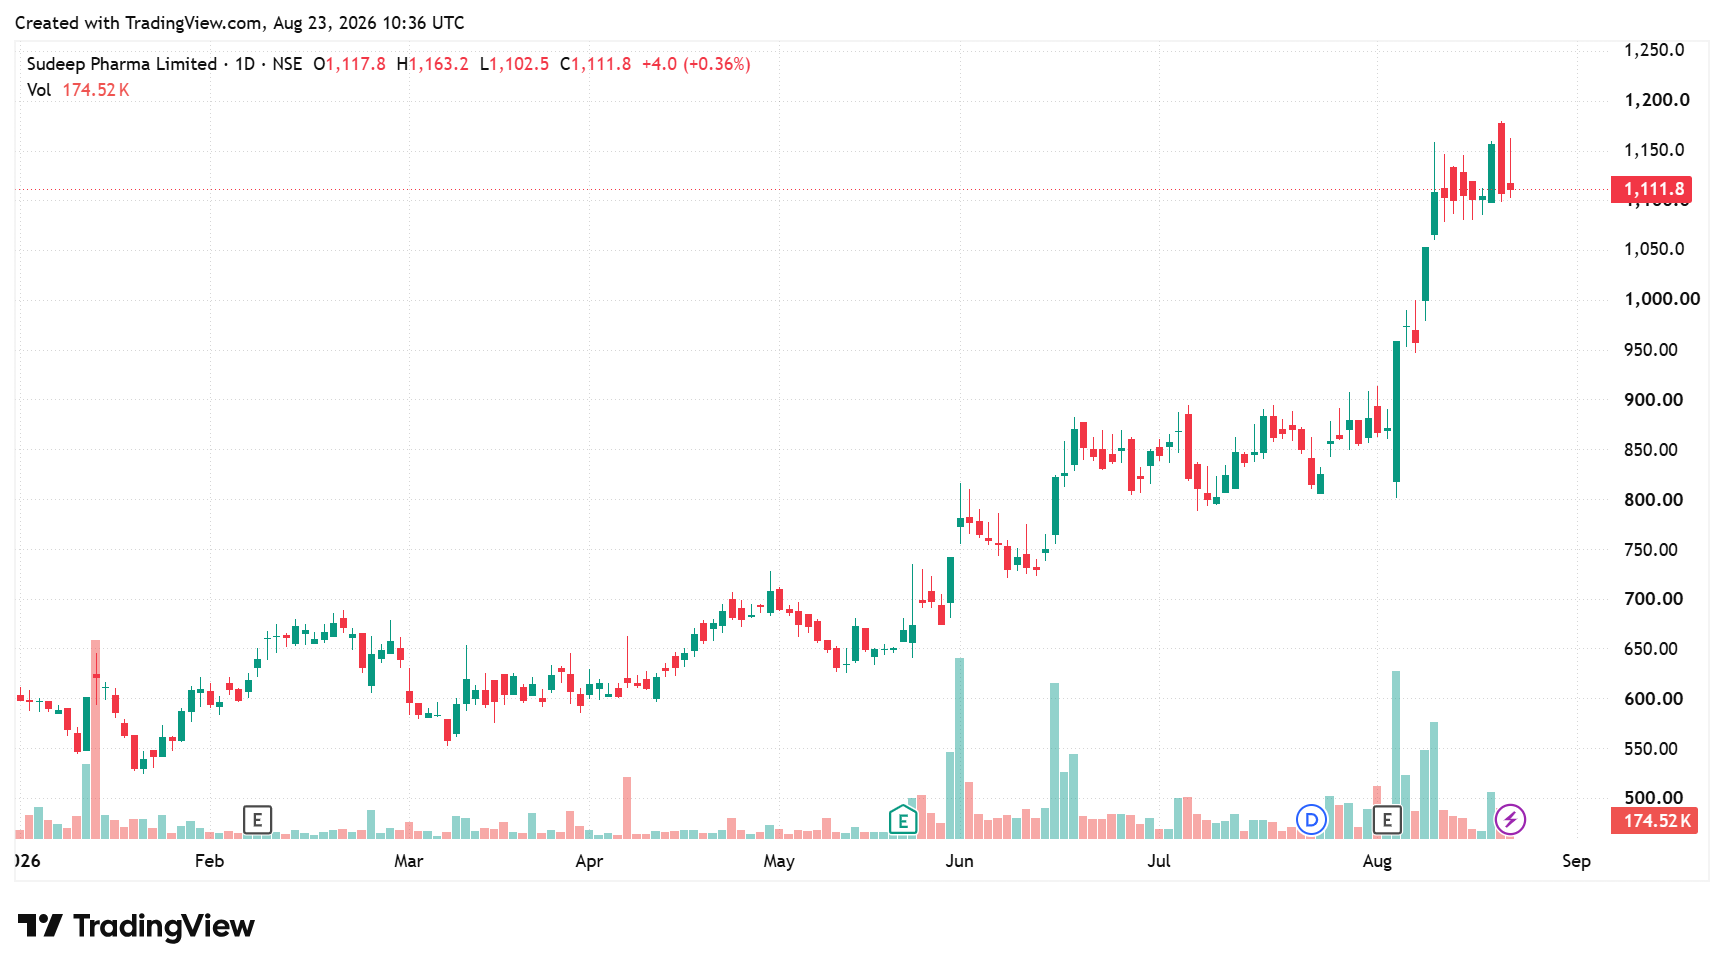
#1 Sudeep Pharma: Building a ₹300-Crore Play in Non-China LFP Precursors
Sudeep Pharma manufactures specialty ingredients for the pharmaceutical, food, and nutrition industries. Its annual manufacturing capacity is 123,000+ metric tonnes (MT). The company offers 100+ products and serves a diverse base of 1,120+ customers across 100 countries.
It is the first and only company in India to hold US-FDA approval for mineral-based ingredients. It is one of only 9 companies globally to obtain the European CEP Certification for Calcium Carbonate. Sudeep Pharma is one of the world’s largest producers of food-grade Iron Phosphate and a top exporter of mineral ingredients from India.
Breaking China’s Monopoly: The Non-FEOC Battery Strategy
Sudeep Pharma is expanding into the advanced battery materials sector to capture growth in the global electric vehicle and energy storage system market. The company focuses on battery-grade iron phosphate pCAM (precursor cathode active material).
This material supports LFP (lithium iron phosphate) and LMFP (lithium manganese iron phosphate) battery chemistries. Sudeep Pharma is using its existing expertise in Iron Phosphate to diversify into the battery chemical business. Sudeep Pharma is positioning itself to become one of the first and largest scalable producers of LFP precursors outside China.
Currently, China dominates the global market, producing nearly 100% of LFP precursors and cathode materials. It is fully aligned with FEOC (Foreign Entity of Concern) compliance norms. This compliance makes the company eligible for subsidies under the US Inflation Reduction Act and the EU Critical Raw Materials Act.
Scaling to 105,000 MT: Execution Timelines and Customer Pipeline
To maintain strict FEOC compliance, Sudeep Pharma will not source any phosphoric acid (its largest raw material by value) from China. Instead, it will secure the supply domestically from India and through imports from three other non-Chinese countries. The plant is currently under construction after groundbreaking on 23 January, 2026.
It is on track to be commissioned by April 2027. The battery division has a robust commercial pipeline with 44 active customers. Sudeep has achieved 28 product approvals with zero sample rejections. It is currently fully qualified with 8 major customers, including large battery/cathode companies in South Korea and the US.
The company currently has eight total Memorandum of Understanding (MoUs). Sudeep is actively targeting cell makers and OEMs across South Korea, Japan, Indonesia, Europe, the US, and Australia. With strong customer demand, Sudeep has already begun planning for Phase 2.
The company’s near-term capacity would reach 65,000 MT (including Phase 2 of 45,000 MT) and ultimately 105,000 MT by Phase 3. The existing Dahej site can be scaled up to 200,000 MT by 2031. Meanwhile, it has upgraded its existing pharmaceutical iron phosphate facility to produce 5,000 MT of battery-grade material.
Financial Profile: ₹300-Crore Capex and Q1FY27 Outperformance
The capital outlay for the battery materials project is approximately ₹300 crore, funded through a combination of internal accruals and debt. Sudeep expects asset turns for the battery segment to settle between 2.7x and 3.0x once operating at scale.
Management expects the segment’s return on capital employed and asset turnover to align with the core specialty ingredients business. On the financial front, the company delivered a strong quarterly performance in Q1FY27. Revenue grew 27% year-on-year to ₹158.3 crore, driven by 31% growth in Pharma, Food & Nutrition Business.
Domestic revenue accounted for 45% in Q1 FY27 compared to 49% in Q1FY26. EBITDA (earnings before interest, tax, depreciation, and amortisation) grew 25% to ₹54.9 crore, while margins declined 40 bps to 34.7%. Net profit grew 30% to ₹40.6 crore.
#2 Tatva Chintan Pharma Chemical: Eyes ₹60-Crore Electrolyte Revenue
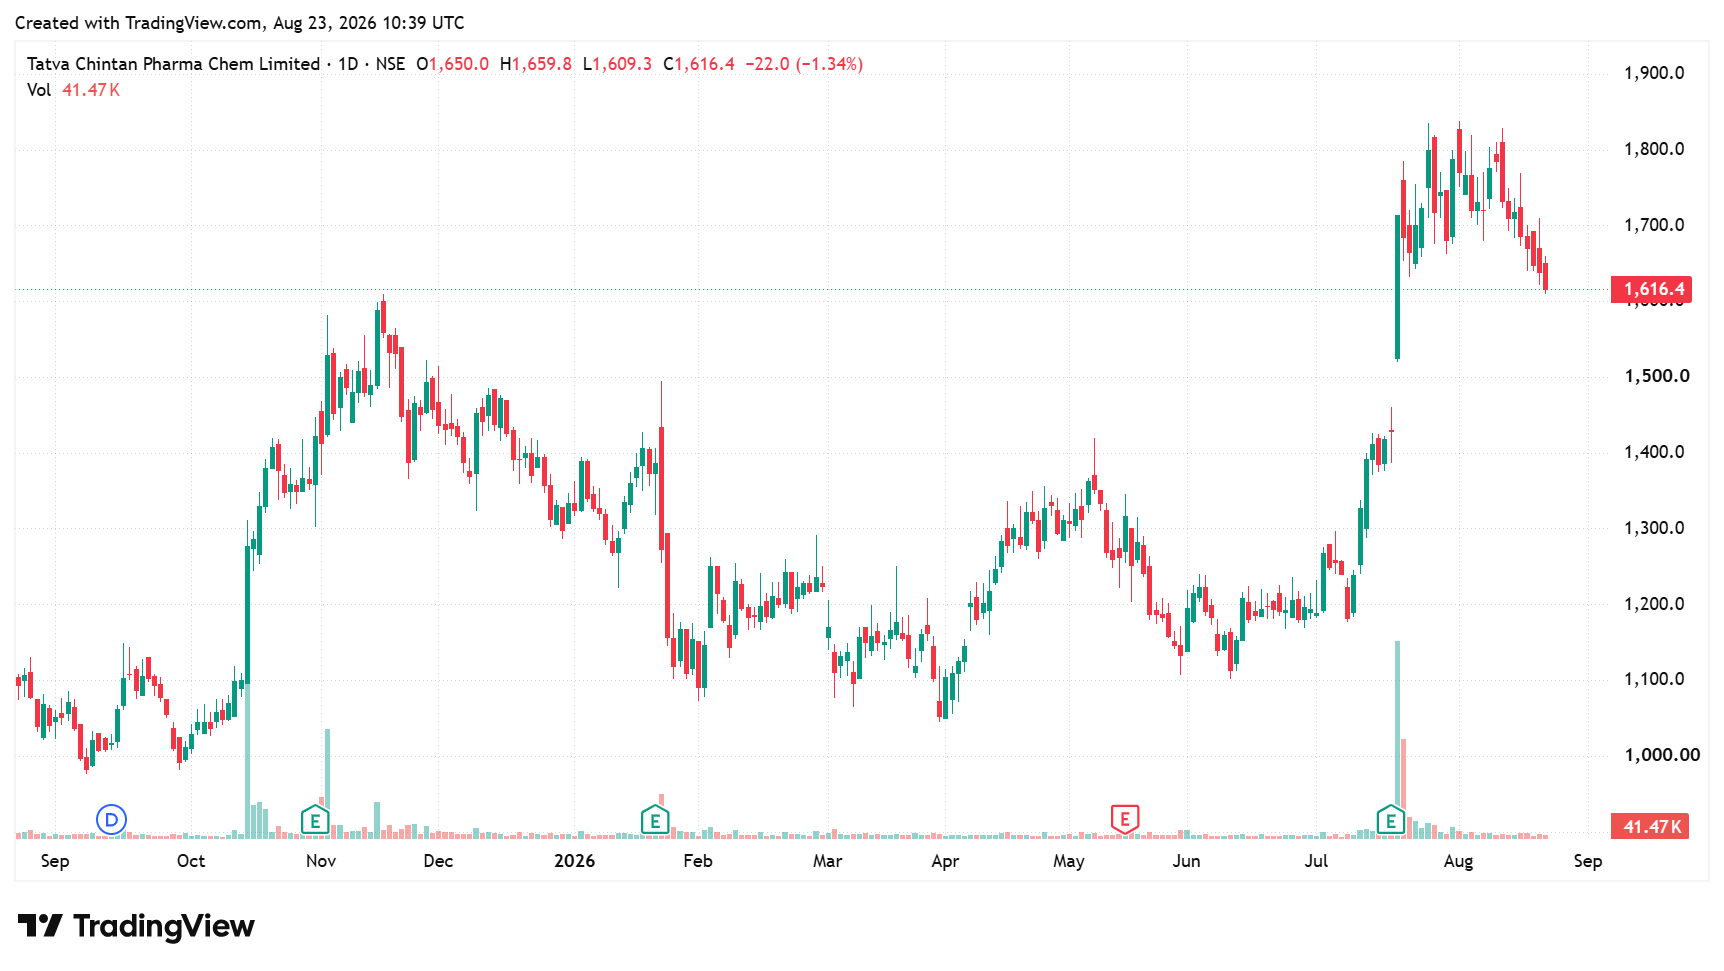
Tatva Chintan Pharma Chemical is a niche Indian specialty chemical manufacturer. The company operates in four distinct product segments: Structure Directing Agents (41% of FY26 revenue), Pharma & Agrochemical Intermediaries (32%), (PTC) Phase Transfer Catalysts (23%) and (ESS) Electrolyte Salts & Solutions (3%).
Supercapacitor Pivot: Forward-Integrating PTCs into Battery Electrolytes
Tatva Chintan is India’s largest producer of electrolyte salts for supercapacitor batteries. These supercapacitors are high-power-density storage devices used in electric vehicles to provide a sudden burst of energy during starting and accelerating. The product is also used in consumer electronics, renewable solar energy storage, and smart grids.
A key differentiator for Tatva Chintan is the forward-integration of PTC chemistry into ESS. As market demand for ESS rises, Tatva Chintan uses its in-house manufactured PTCs as raw materials to synthesise electrolyte salts. PTCs enable a reactant to migrate from one phase into another.
Navigating Supply Shocks: ESS Segment Performance and FY27 Guidance
In Q1FY27, the ESS segment generated revenue of ₹6.3 crore (up 76% YoY), representing 4% of total operating revenue. In FY26, the ESS segment generated ₹16.5 crore, also accounting for 3% of total revenue. However, Q1FY27 revenue declined sequentially due to a severe raw material supply shortage caused by the Middle East crisis.
This forced the company’s production in this segment to sit idle for a few weeks, delaying production and revenue recognition. Management noted that raw material availability is now gradually improving. Despite this, the company maintains its FY27 revenue guidance of ₹40 crore to ₹60 crore for the ESS segment.
Currently, the highest demand is coming from a few customers who use electrolytes for stationary energy storage systems. Meanwhile, work with a hybrid vehicle battery customer is progressing steadily. Tatva Chintan will begin supplies to this customer by November 2026, with full commercialisation expected by the end of 2027.
Financial Health: 140% PAT Surge and Long-Term CAGR Road Map
Coming to its financial performance, revenue from operations grew 43% year-on-year to ₹167.1 crore. This growth was driven by 35% growth in pharma and agro intermediates and specialty chemicals and 47% growth in structure directing agents. EBITDA increased 86% to ₹32.3 crore, while margins expanded 400 bps to 19%. Net profit increased 140% to ₹16.0 crore.
Looking ahead, management expects full-year operating revenue growth of 25% to 30% in FY27, with margins at 20% to 22%. Over the next three to four years, the company aims to grow at a CAGR of 20% to 25%.
Valuation Check: Premium Multiples Meet Execution Risk
Sudeep Pharma boasts a strong Return on Capital Employed (ROCE) and Return on Equity (ROE). Tatva Chintan return ratios are moderate due to volatile profitability. Valuation-wise, both companies trade at more than double the industry median. Tatva Chintan trades at a discount to its historical five-year median. Sudeep has a limited trading history.
| Peer Comparison (X) | |||||
Company | Price-to-Earnings Multiple | Return Ratios | |||
| Company | 5Y Median | Industry | ROCE (%) | ROE (%) | |
| Tatva Chintan | 72.2 | 80.1 | 28.2 | 7.1 | 5.5 |
| Sudeep Pharma | 68.8 | NA | 32.6 | 28.2 | 25.2 |
| Source: Screener.in (Data as of 21 August 2026) | |||||
India’s energy storage opportunity is creating a new growth avenue for specialty chemical companies. Sudeep Pharma is taking a larger bet on the LFP supply chain, backed by a ₹300 crore investment and plans to scale battery material capacity to 105,000 MT.
On the other hand, Tatva Chintan is taking a more gradual route through electrolyte salts and supercapacitor applications, with FY27 ESS revenue targeted at ₹40-60 crore. Both businesses are still in the early stages, making execution and customer conversion key to the investment case. You could keep these names on your watchlist to track their execution.
Disclaimer:
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation. We used an alternative, widely used, and accepted source of information only when the data was unavailable.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
About the Author: Madhvendra has been deeply immersed in the equity markets for over seven years, combining his passion for investing with his expertise in financial writing. With a knack for simplifying complex concepts, he enjoys sharing his honest perspectives on startups, listed Indian companies, and macroeconomic trends.
A dedicated reader and storyteller, Madhvendra thrives on uncovering insights that inspire his audience to deepen their understanding of the financial world.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources, and only after consulting such independent advisors as may be necessary.