



India’s shipbuilding sector is commonly associated with warships and other vessels built for the Indian Navy. Defence orders remain central to the industry, supported by the government’s focus on domestic manufacturing and the modernisation of the naval fleet. However, a broader commercial story is now beginning to emerge across some of the country’s major shipyards.
Indian shipyards are securing orders from overseas customers, expanding into commercial vessels and strengthening their ship repair businesses. These activities can diversify revenue, bring in foreign currency and improve the utilisation of existing yards, docks and technical capabilities. They may also reduce the dependence of shipyards on the timing of large defence orders.
This article looks at three listed shipyard stocks that are pursuing different opportunities beyond warships. Their progress indicates that commercial shipbuilding, exports and ship repair could gradually become more meaningful parts of India’s maritime growth story.
The discussion is limited to three companies because they already have visible developments in these areas. Other listed shipbuilders are either not meaningfully present in these segments yet or are too small for a comparable analysis. Mazagon Dock Shipbuilders, for instance, remains largely focused on naval vessels and has yet to establish a similar commercial diversification story.
Join now
#1 Swan Defence & Heavy Industry: A bankrupt shipyard returns with global orders
Incorporated in 1997, Swan Defence and Heavy Industries is engaged in the construction of vessels, repairs, and refits of ships and rigs and heavy engineering.
Swan Defence & Heavy Industry Information
| Metric | Details |
| Q1 FY27 revenue | Rs 30.61 crore, up 7,188% YoY |
| Q1 FY27 net result | Loss of Rs 41.68 crore, widened 35.4% YoY |
| Commercial orders | Chemical tankers, dual-fuel ammonia bulk carriers and tugs |
| Diversification path | Export-led revival of the Pipavav shipyard |
Swan Defence and Heavy Industries is attempting a turnaround at the former Reliance Naval and Engineering shipyard. The Swan Group took control of the facility through the insolvency process in January 2024. It has since restarted operations, cleared legacy obligations and rebuilt the order book.
The recovery is visible in revenue, though profitability remains weak. Consolidated revenue from operations rose to Rs 30.61 crore in Q1 FY27 from Rs 0.42 crore a year earlier. This was an increase of about 7,188% on a low base. The net loss widened 35.4% to Rs 41.68 crore from Rs 30.79 crore.
The company closed its resolution plan in FY26. It prepaid obligations to its committee of creditors that were originally due in December 2026 and 2027. This removed an important financial overhang from the earlier business.
Commercial Exports: Swan Defence’s High-Risk Turnaround
Swan Defence also began building a commercial export order book during FY26. It secured a $227 million contract from Norway’s Rederiet Stenersen for six 18,000-deadweight-tonne chemical tankers. The agreement includes an option for six more vessels.
Another FY26 order covers four 92,500-deadweight-tonne dual-fuel ammonia bulk carriers for Energy ONE. The two contracts take the shipyard beyond warships and into commercial vessels linked to the global shift towards cleaner shipping. The annual report does not disclose the individual dates on which these orders were secured.
The export pipeline expanded further on August 6, 2026. Swan Defence announced an order from Denmark-based Svitzer to build four TRAnsverse 3200 tugs. Deliveries are scheduled to begin in early 2028. The vessels are designed for harbour towage and escort operations and are expected to be up to 15% more fuel-efficient than conventional tug designs. The company described this as its fourth consecutive export contract.
Defence work remains part of the mix. The company is building a training vessel for the Royal Navy of Oman and has also undertaken repair and refit assignments.
The export wins mark progress from the shipyard’s insolvency years. However, timely delivery, cost control and a return to profitability will determine whether the early revival becomes a sustainable turnaround.
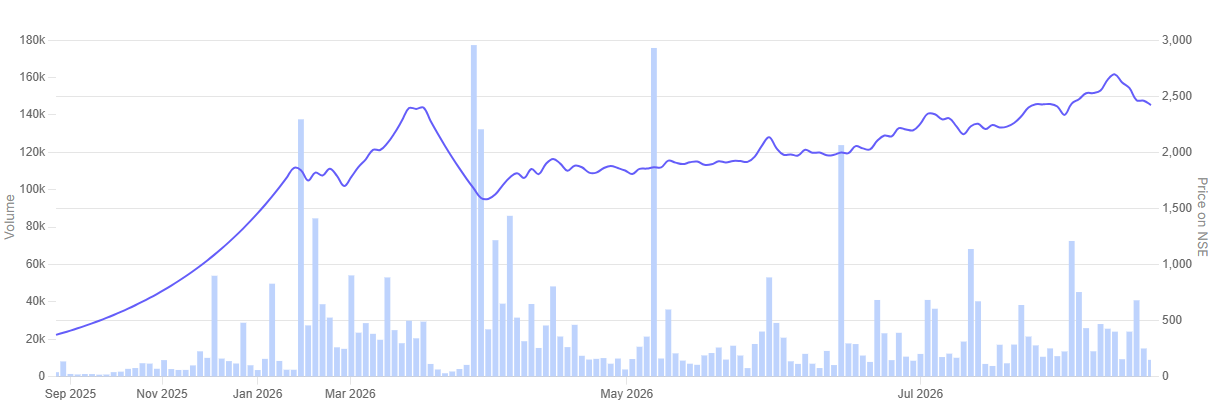
In the past year, the share price of Swan Defence and Heavy Industries surged 556.6%.
Swan Defence & Heavy Industries 1 Year Share Price Chart
#2 Garden Reach Shipbuilders and Engineers: Commercial orders gain ground alongside warships
Garden Reach Shipbuilders & Engineers is a premier shipbuilding company in India under the administrative control of the Ministry of Defence, primarily catering to the shipbuilding requirements of the Indian Navy and the Indian Coast Guard.
Garden Reach Shipbuilders and Engineers Information
| Metric | Details |
| Q1 FY27 revenue | Rs 1,815 crore, up 39% YoY |
| Q1 FY27 net profit | Rs 173 crore, up 44% YoY |
| Non-defence share | 25% of the shipbuilding order book |
| Diversification path | Commercial exports, research vessels, ferries and dredgers |
Garden Reach Shipbuilders & Engineers is widening its order mix beyond naval vessels. Warships remain its main business, but commercial ships, research vessels and export orders now form a larger part of its pipeline.
Revenue from operations rose 39% YoY to Rs 1,815 crore in Q1 FY27 from Rs 1,310 crore. Profit after tax increased 44% to Rs 173 crore from Rs 120 crore. The company said this was its 17th consecutive quarter of improving financial performance.
Scaling Non-Defence Volume: GRSE’s Commercial Order Book Gains Ground
GRSE’s order book stood at Rs 13,596 crore. Shipbuilding accounted for about 95% of this amount. Within the shipbuilding portfolio, naval projects contributed 74%, while non-defence orders formed the remaining 25%. Defence once accounted for 98% of its shipbuilding order book.
The clearest sign of diversification is its multipurpose vessel contract for a German customer. The project initially covered four ships but has since expanded to 12. Construction has started on five vessels. GRSE has described it as its largest commercial export order, though the transcript does not disclose its standalone value or delivery dates.
The non-defence pipeline also includes research vessels, 13 electric ferries for West Bengal and a dredger for Bangladesh. The dredger had reached about 70% physical completion. Two ferries are due for delivery in September and October 2026, with the rest expected by April 2027. GRSE has also received orders for four platform support vessels and a green tug.
Capacity expansion is being planned around this broader opportunity. GRSE expects to raise concurrent construction capacity from 28 to 32 platforms by the end of 2026. Longer-term projects could lift this to 43. A proposed western facility will focus mainly on large commercial ships, green ship recycling and repairs. Environmental clearance has been obtained, with investment estimated at about Rs 2,000 crore.
Warships will remain the revenue anchor in the near term. The test will be whether GRSE can execute its German export order and convert its planned capacity into a durable commercial business.
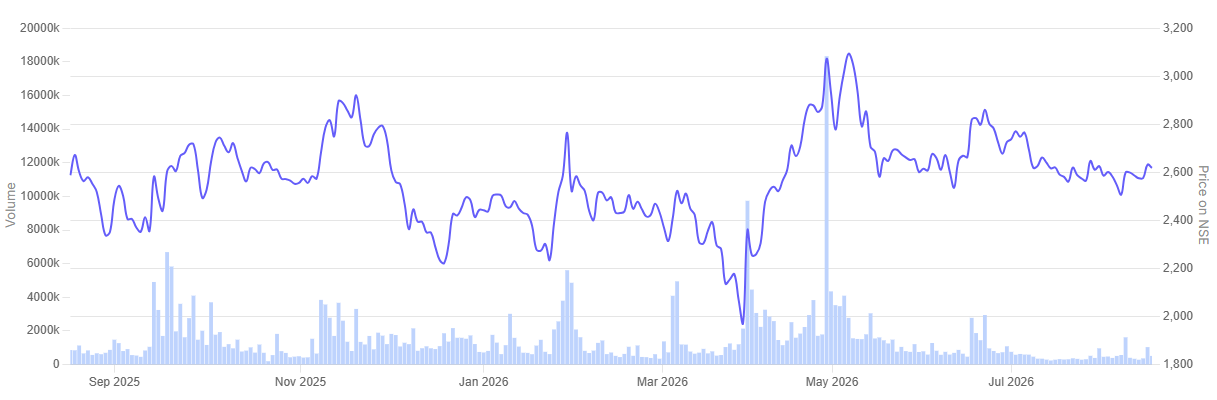
In the past year, the share price of Garden Reach Shipbuilders and Engineers is up 1%.
Garden Reach Shipbuilders and Engineers 1 Year Share Price Chart
#3 Cochin Shipyard: Ship repair adds a second engine beyond naval orders
Cochin Shipyard is building a broader maritime business alongside its naval projects. Shipbuilding remains the larger segment, but ship repair, commercial vessels and green technologies are widening its revenue base.
Cochin Shipyard Information
| Metric | Details |
| Q1 FY27 revenue | Rs 1,094 crore, up 2.4% YoY |
| Q1 FY27 net profit | Rs 151 crore, down 19.7% YoY |
| Ship repair revenue | Rs 394 crore, down 37.4% YoY |
| Diversification path | Ship repair, commercial tugs and green maritime technology |
Consolidated revenue from operations rose 2.4% YoY to Rs 1,094 crore in Q1 FY27 from Rs 1,069 crore. Net profit fell 19.7% to Rs 151 crore from Rs 188 crore. The decline came despite stronger shipbuilding activity.
Shipbuilding revenue increased 59.5% to Rs 700 crore from Rs 439 crore. This includes naval and commercial work. Ship repair revenue fell 37.4% to Rs 394 crore from Rs 630 crore. Even after the decline, repairs contributed about 36% of operating revenue during the quarter.
The repair business gives Cochin Shipyard a recurring stream beyond new warship construction. Its International Ship Repair Facility at Willingdon Island began operations in August 2024. The facility has a ship-lift system and six workstations, allowing several vessels to be handled at the same time. The company also operates repair units in Mumbai, Kolkata and Port Blair.
Recurring Cash Flow: Cochin Shipyard’s Ship Repair Engine
Commercial shipbuilding is expanding through tugs and specialised vessels. In December 2025, Cochin Shipyard signed an agreement with Denmark’s Svitzer for at least four battery-electric tugs, with an option for four more. Construction is expected to begin in the third quarter of 2026. The first delivery is targeted for late 2027 or early 2028, subject to design work, yard availability and regulatory approvals.
The group’s order book also includes 17 standard tugs and six green tugs. Meanwhile, a joint venture with HBL Engineering will develop marine batteries, electric motors and energy-storage systems for domestic and overseas markets.
Naval orders will remain important. However, repairs and green commercial vessels give the company additional sources of work. The near-term concern is the sharp fall in repair revenue, making recovery in this segment important for balanced growth.
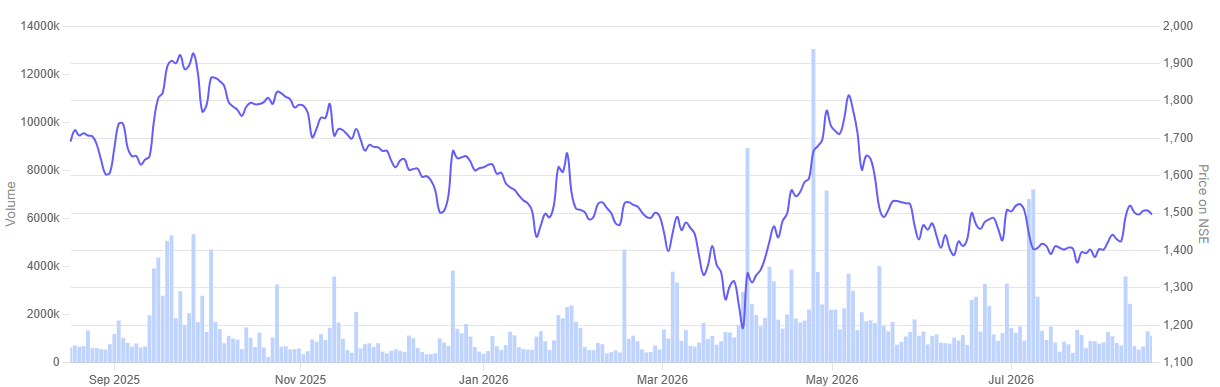
In the past year, the share price of Cochin Shipyard is down 11.7%.
Cochin Shipyard 1 Year Share Price Chart
Conclusion
India’s shipyard stocks are no longer moving along the same path. Swan Defence is rebuilding a previously stressed shipyard through export orders. GRSE is adding commercial vessels to a defence-heavy order book, while Cochin Shipyard is developing ship repair and green vessels alongside naval work.
Warships will remain important to all three businesses. However, commercial orders, exports and repairs can widen their revenue base and improve the use of existing facilities. The opportunity is visible, but execution will matter. Delivery schedules, project costs and the ability to earn sustainable profits from these new businesses will decide whether diversification creates lasting value.
India’s Shipyard Stocks Moving Beyond Warships
| Metric | Swan Defence | GRSE | Cochin Shipyard |
| Q1 FY27 revenue growth | 7,188% | 39% | 2.4% |
| Q1 FY27 net profit growth | Net loss widened 35.4% | 44% | −19.7% |
| Main diversification path | Commercial exports | Commercial and research vessels | Ship repair and green vessels |
| Key non-warship development | Chemical tankers, ammonia-fuelled bulk carriers and tugs | 12 German multipurpose vessels | Ship repair network and electric tugs |
You can track how these are progressing by adding stocks to your watchlist.
Note: We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
Disclaimer:
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Ekta Sonecha Desai has a passion for writing and a deep interest in the equity markets. Combined with an analytical approach, she likes to deep dive into the world of companies, studying their performance, and uncovering insights that bring value to her readers.
Disclosure: The writer and her dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.