



Every investment philosophy has one name that defines it. For value investing, that name is Benjamin Graham. Known as the father of value investing, Graham turned stock-picking from a contest of predictions into a discipline built on numbers. His basic principle was simple: examine the business, question the price and never mistake market excitement for value.
We previously applied Graham’s seven-rule checklist for defensive investors to the Indian market. That test searched for established companies with long records of profits, dividends and financial strength. This time, we move to Graham’s other category: The Enterprising Investor.
Graham set out this approach in The Intelligent Investor. The Enterprising Investor was not simply willing to take more risk. This investor was prepared to conduct more research to find financially sound companies overlooked by the market. Graham began with stocks trading at less than 10 times earnings. An Edelweiss Mutual Fund summary of the book lists the five additional tests:
- Financial condition: Current assets should be at least 1.5 times current liabilities. Debt should not exceed 110% of net current assets.
- Earnings stability: The company should not have reported a loss in the previous five years.
- Dividend record: The company should be paying a current dividend.
- Earnings growth: The latest annual earnings should be higher than they were five years earlier.
- Asset valuation: The share price should be less than 1.2 times net tangible asset value after excluding goodwill and other intangible assets.
We considered only companies that had announced their Q1FY27 results. We then applied a market-capitalisation threshold of more than Rs 2,500 crore to avoid very small and potentially illiquid stocks.
The remaining companies needed a current ratio above 1.5 and debt below 110% of net current assets. They also required positive profits in each of the latest two years, a P/E ratio of 9 or less, a price-to-book ratio of 1.2 or less, a dividend in the latest year and positive five-year EPS growth. Four companies passed this initial screen.
Get instant alerts on high-conviction investment themes and fundamental deep dives—direct from Financial Express.
Join now
We then manually confirmed that each company had remained profitable throughout the last five completed financial years and that its latest annual EPS was higher than five years earlier. Finally, we applied Graham’s stricter net tangible asset test. One out of the four companies – Route Mobile was removed because it traded at around 1.62 times its tangible book value after goodwill and other intangible assets were excluded.
For earnings stability, we checked the five completed financial years from FY22 to FY26. None of the selected companies reported a loss during this period. Graham’s separate earnings-growth condition compares the latest annual EPS with EPS five years earlier. We therefore compared FY26 with FY21. Since FY21 was affected by the pandemic, this comparison was treated only as an eligibility check and not as proof of consistent earnings growth.
#1 Great Eastern Shipping Company: Capitalizing on Tanker Freight Rates
Great Eastern Shipping Company along with its subsidiaries is a major player in the Indian shipping and oil drilling services industry.
GE Shipping cleared the screen with a current ratio of 7.08 times. Its borrowings were equal to about 13% of net current assets. The company reported a profit in every year from FY22 to FY26. Its FY26 EPS of Rs 206.11 was also higher than the Rs 62.50 reported five years earlier. No separate intangible asset was disclosed. At the screening cut-off, the stock traded at 5.05 times earnings and 1.12 times tangible book value. It offered a dividend yield of 2.65%.
Fleet Modernization & Tanker Rate Tailwinds
GE Shipping is using strong tanker cash flows to modernise its fleet. However, it is not pursuing aggressive expansion at current vessel prices. Management said in the company’s Q1FY27 earnings-call transcript that its strategy is to replace ageing ships rather than expand capacity. It will wait for asset prices that can generate acceptable long-term returns.
According to GE Shipping’s Q1FY27 investor presentation, the company operates 40 ships with an average age of around 14 years. Its offshore fleet includes 19 vessels and four rigs. The presentation shows that it sold two older medium-range tankers and acquired a newer tanker and a Kamsarmax dry-bulk carrier during Q1FY27. It replaced an LR2 tanker with an eco-efficient vessel that is six years younger in July. Management said that it invested around Rs 300 crore during Q1 and another Rs 250-300 crore in July.
The investor presentation showed that consolidated revenue, including other income, rose 71% year-on-year (YoY) to Rs 2,286 crore in Q1FY27. Net profit increased 159% to a record Rs 1,309 crore. Management attributed the strong quarter partly to disruptions around the Strait of Hormuz. Asian countries sourced more oil from the US and Brazil. The longer voyages increased demand for ships.
Earnings Surge vs. Cyclical Risks: Valuation Under Graham’s Lens
The presentation also showed that average daily earnings from crude carriers rose 175% YoY. Product-carrier earnings increased 84%, while dry-bulk earnings grew 52%. LPG carrier earnings declined 5% because most vessels remained on fixed-rate charters.
In the offshore business, management said that the company had received a three-year contract for one jack-up rig. Two rigs remain due for repricing. Another rig could return to work after the monsoon if ongoing discussions result in a contract.
According to Screener, the stock trades at a P/E of 5.0, against the peer median of 10.2. ROCE stands at 15.8%, while ROE is 15.9%. However, shipping remains cyclical. Rising vessel order books and a reversal in geopolitical disruptions could soften freight rates and earnings.
Great Eastern Shipping Financial Performance
| Metric | Value |
| P/E | 5.0x |
| ROCE | 15.8% |
| Q1FY27 revenue growth | Up 71% |
| Q1FY27 profit growth | Up 159% |
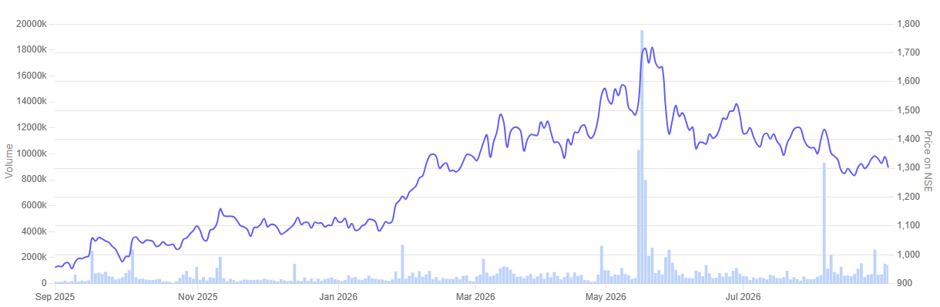
In the past year the share price of Great Eastern Shipping surged 39.3%.
Great Eastern Shipping 1-Year Share Price Chart
#2 Gujarat Narmada Valley Fertilizers and Chemicals: Strategic Cost-Reduction and Capacity Expansion
Gujarat Narmada Valley Fertilizers & Chemicals (GNFC) is a joint sector enterprise promoted by the Gujarat State Investments (GSIL), a Government of Gujarat undertaking, and the Gujarat State Fertilizers & Chemicals (GSFC). The company operates businesses mainly in the industrial chemicals, fertilizers apart from the small presence of IT services.
GNFC qualified with a current ratio of 5.91 times. Borrowings were less than 0.1% of net current assets, reflecting its near debt-free balance sheet. The company remained profitable in every year from FY22 to FY26. Its FY26 EPS of Rs 55.03 was above the Rs 44.84 recorded five years earlier.
After conservatively deducting the entire Rs 34 crore disclosed under intangible assets, tangible book value worked out to about Rs 617.70 per share. At the screening cut-off, the stock traded at 8.18 times earnings and 0.93 times tangible book value. Its dividend yield was 3.65%.
Capital Expenditure Pipeline & Efficiency Gains
GNFC’s place on the Benjamin Graham Enterprising Investor shortlist rests on more than a low earnings multiple. The fertiliser and chemicals producer is pursuing a capacity and cost-reduction programme. Earnings remain sensitive to fuel costs and chemical prices.
According to GNFC’s Q1FY27 earnings-call transcript, projects worth Rs 2,800 crore are under way. The company spent Rs 300 crore in the June quarter. It expects full-year capital expenditure of Rs 1,500-1,800 crore. Most projects, apart from the Rs 613-crore Dahej captive power plant, are due to start commercial operations around mid-2027.
Steam production has begun at Dahej. This replaces expensive gas at the TDI-II unit. Power generation was expected within 30-45 days of the August 6 call. Management estimated savings of Rs 30,000-40,000 per tonne of TDI at prevailing fuel prices.
GNFC’s FY26 annual report schedules the ammonia revamp for Q2FY28. It sets June 2027 for the weak nitric acid plant and August 2027 for the second ammonium nitrate unit. Management has since disclosed a three-month delay in the nitric acid project. Studies are also continuing under a proposed tie-up with GMDC for underground coal gasification.
Revenue Catalysts vs. Feedstock Volatility: Valuation Insights
The earnings-call transcript says management expects the completed projects to add Rs 1,200-1,500 crore to revenue and Rs 500-600 crore to contribution. It cautioned that volatile product prices make these estimates difficult.
GNFC’s June-quarter consolidated revenue rose 39.8% YoY to Rs 2,238 crore. Net profit climbed 275.9% to Rs 312 crore. Better chemical realisations supported the improvement, although sales volumes were lower. Fertiliser segment profit increased to about Rs 85 crore from Rs 24 crore.
Some chemical plants were shut because production was uneconomic. Acetic acid, ethyl acetate and TDI operations resumed by early August. Management said global TDI supply still exceeds demand, though India faces a shortage.
According to Screener, GNFC traded at 8.2 times earnings against a peer multiple of 19.9. ROCE stood at 12%, while ROE was 9.1%. However, modest returns, volatile feedstock prices and execution delays remain important risks.
GNFC Financial Performance
| Metric | Value |
| P/E | 8.2x |
| ROCE | 12.0% |
| Q1FY27 revenue growth | Up 39.8% |
| Q1FY27 profit growth | Up 275.9% |
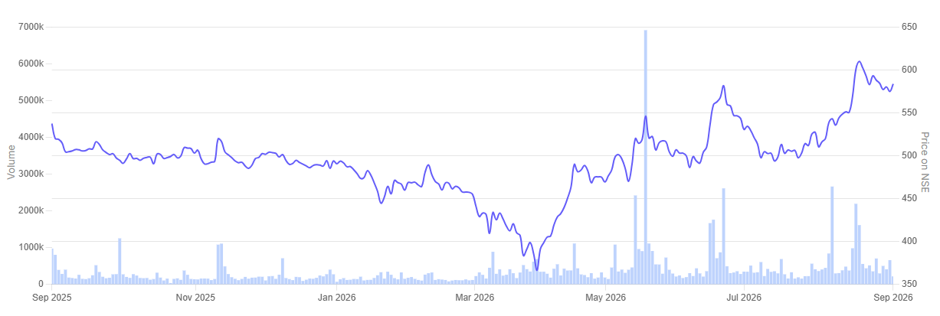
In the past year the share price of Gujarat Narmada Valley Fertilizers & Chemicals is up 7.5%.
Gujarat Narmada Valley Fertilizers & Chemicals 1-Year Share Price Chart
#3 PTC India: High Payout Yield Meets Power Trading Transition
PTC India was established in 1999 by the Government of India as a Public-Private Initiative and is in the power trading business. It is promoted by Power Grid Corporation of India (PGCIL), NTPC (NTPC), Power Finance Corporation (PFC) and NHPC.
PTC India entered the shortlist with a current ratio of approximately 2.24 times. Its borrowings were equal to around 31.5% of net current assets. The company reported positive profits in every year from FY22 to FY26. Its FY26 EPS of Rs 20.46 was higher than the Rs 15.16 recorded five years earlier. After conservatively deducting Rs 1.39 crore of disclosed intangible assets, tangible book value stood at approximately Rs 201.95 per share. The stock traded at 8.96 times earnings and 0.77 times tangible book value. Its trailing dividend yield was 14.8%, although this was boosted by a one-off Rs 23-per-share dividend.
Strategic Pivot Toward Renewable & Storage Energy
PTC India is repositioning its power-trading franchise for a market shaped by exchanges, renewable energy and time-of-day demand gaps. Its place on the Benjamin Graham Enterprising Investor shortlist comes from its valuation and balance-sheet strength. The business case, however, depends on converting higher trading volumes into income.
According to PTC India’s Q1FY27 earnings-call transcript, trading volume rose 12% to 25.78 billion units. Exchange-based products contributed 60% of the total. These trades generally carry lower margins. PTC therefore plans to balance them with medium-term contracts and storage-linked transactions. It is evaluating owning battery capacity and hiring it from service providers.
The company has signed a long-term agreement to procure 1,200 MW of solar power from NTPC Green. Supply is expected to begin in FY29. PTC also said none of its existing long-term contracts is likely to expire over the next three years.
Its cross-border operations cover Bhutan, Nepal and Bangladesh. PTC has started importing and exporting electricity with Nepal. Supplies and payments from Bangladesh remain regular. The earnings-call transcript also said the Department of Public Enterprises has cleared a proposed joint venture with NLC India. PTC’s board has approved investment of up to Rs 500 crore. Actual deployment will depend on the projects selected.
PTC India’s Q1FY27 investor presentation showed consolidated revenue from operations rising about 19% YoY to Rs 4,731 crore. Consolidated profit after tax fell 54% to Rs 112 crore. The decline reflected lower rebate and surcharge income as distribution companies paid more promptly. The previous-year quarter had also benefited from an Rs 82-crore reversal of an impairment provision at PTC Financial Services.
PTC has appointed a transaction adviser for the proposed divestment of that subsidiary. The process requires RBI and SEBI approvals. Management expects greater clarity closer to the end of FY27 but has not set a completion date.
One-Off Dividend Yield vs. Margin Compression Exposure
At the screening cut-off, PTC India traded at 9.1 times earnings. ROCE stood at 13.4% and ROE at 10.3%. However, lower-margin exchange volumes, regulatory dependence and uncertain subsidiary monetisation remain key risks.
PTC India Financial Performance
| Metric | Value |
| P/E | 9.1x |
| ROCE | 13.4% |
| Q1FY27 revenue growth | Up 19% |
| Q1FY27 profit growth | Down 54% |
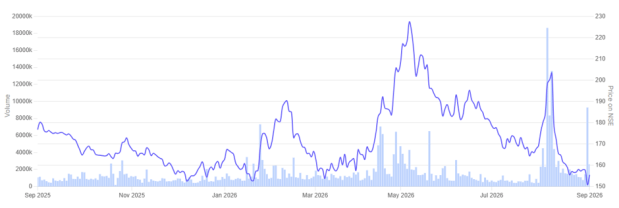
In the past year the share price of PTC India is down 12%.
PTC India 1-Year Share Price Chart
The Final Take
Graham’s Enterprising Investor test was designed to narrow the market to financially sound stocks available at modest valuations. It was not meant to replace detailed research. GE Shipping, GNFC and PTC India cleared the quantitative conditions used in this screen.
Each company still carries distinct risks. Shipping earnings are cyclical. GNFC faces volatile chemical prices and execution challenges. PTC India depends on regulation and trading margins. The three stocks therefore represent a shortlist for further study, not ready-made investment recommendations.
You can track how these are progressing by adding stocks to your watchlist.
Note: We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Ekta Sonecha Desai has a passion for writing and a deep interest in the equity markets. Combined with an analytical approach, she likes to deep dive into the world of companies, studying their performance, and uncovering insights that bring value to her readers.
Disclosure: The writer and her dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.