



FMCG stocks, often categorised as ‘defensive stocks’, were once the darling of the stock markets. Of late, however, they have been relegated to the fringes of investment discussions. Investors are en masse focused on AI and related stocks. And why not? Growth has been spectacular. And prospects look bright too.
However, not all growth translates into profits. And definitely, all spectacular growth phases do come to an end. It’s in that context, that one needs to be always looking for ignored opportunities i.e. fundamentally strong companies available for cheap.
Today, we take a look at three FMCG companies with strong moats, and potential for solid growth in the years to come.
Our focus today is on – Britannia Industries Limited, Nestle India Limited, and Varun Beverages Limited. All three are key FMCG stocks with long track records, and strong moats.
Supply Chain Resilience Amid Geopolitical Tensions
These three FMCG stocks are showing good growth despite geopolitical issues, which have hurt the supply chain. The input prices could see a bit of a jump if the current US-Iran war is not resolved quickly. However, all three players have shown good YoY revenue and PAT growth, which shows their ability to absorb any external shocks.
Let’s take a look at what’s driving growth at these companies, and how it could pan out in the years to come.
Join now
#1 The Rapid Acceleration of Quick-Commerce Channels
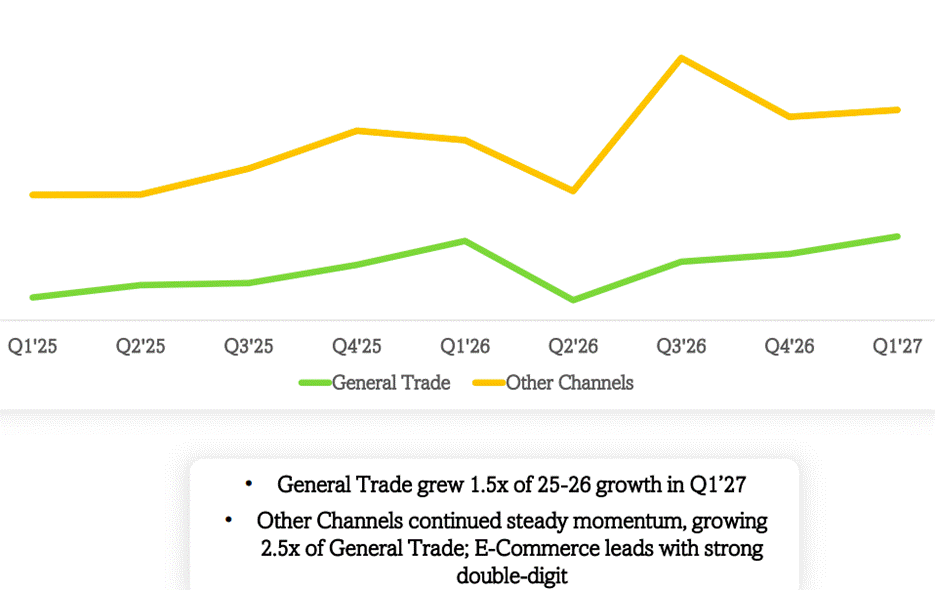
A key growth tailwind for these FMCG companies is the rapid increase in e-commerce, especially quick commerce. The quick commerce growth has increased impulse purchases where customers are willing to order snacks online. Britannia mentioned this trend in its latest earnings results, where its sales from Other Channels, especially e-commerce, grew 2.5x the General Trade.
Britannia’s Other channels growth compared to general trade
In the recent quarter, Eternal’s quick commerce segment reported Rs 17,132 cr in Net Order Value or NOV which was 86% YoY growth. The quick-commerce segment contributes a very small fraction of the total retail trade. Future growth in the quick-commerce market share could further improve the growth momentum of these FMCG stocks.
Nestle India’s FY26 annual report mentioned that the online channels showed a growth of 97%, which is significantly higher than the overall growth rate. At the current rate, the revenue share of online channels is likely to increase rapidly over the next few quarters making it a key growth engine for the company.
For Varun Beverages, its management has earlier mentioned that quick commerce is still a small part of their total volume, and we need to wait a few quarters to see the growth potential of the online channel for Varun Beverages.
#2 Opening of new categories
All these three FMCG companies are trying to enter new categories and launch products that can gain greater traction with customers. Britannia has launched health-focused products like protein beverages and millet brand, while Varun Beverages has launched Sting Gold and dairy beverages. Nestle India has also brought new Maggi options like Maggi Tandoori Masala and Maggi Curry Masala. It has completed the national rollout of Maggi Spicy Green Chilli.
A higher disposable income and demand for new products can be a major driver that can help all these three FMCG stocks deliver a good growth runway for the next few quarters.
#3 Scale efficiency and brand moat
All these three FMCG stocks have shown significant scale efficiency as they continue to expand their operations. It is not easy to replicate their operations as they have built massive distribution channels. At the same time, they are showing a strong brand moat, which allows them to pass any inflationary pressures on raw materials to customers.
Recent Cocoa price volatility
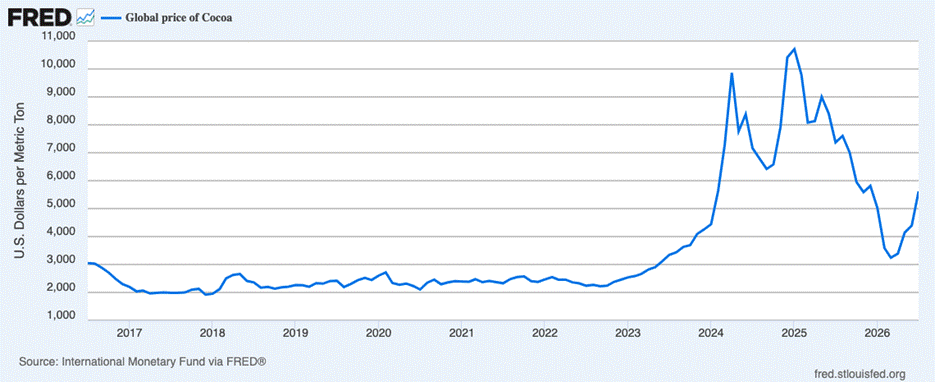
We can see this in how Nestle India has navigated the volatility in cocoa prices. The U.S. Federal Reserve data shows that cocoa prices trade between $2,000 and $3,000 per metric ton. However, by the end of 2024, cocoa price reached close to $12,000 per metric ton. Recently, they have dropped to $5,327 per metric ton, a 34% YoY drop. Cocoa is a key ingredient for Nestle India, but the company is able to deliver good revenue and margin growth despite these headwinds.
Similarly, Britannia and Varun Beverages have also weathered challenges of input costs, which shows their pricing power and brand moat. Britannia has mentioned 11% YoY increase in input milk prices and 69% YoY increase in industrial fuel due to recent oil price spike. The company has used shrinkflation strategy by reducing the weight of a few products in order to absorb a higher input cost.
Varun Beverages mentioned that they have been able to absorb the input price increase by averaging the cost across multiple quarters and the impact on margins would not be significant.
Now let’s look at the performance of each of the three FMCG stocks
#1 Britannia
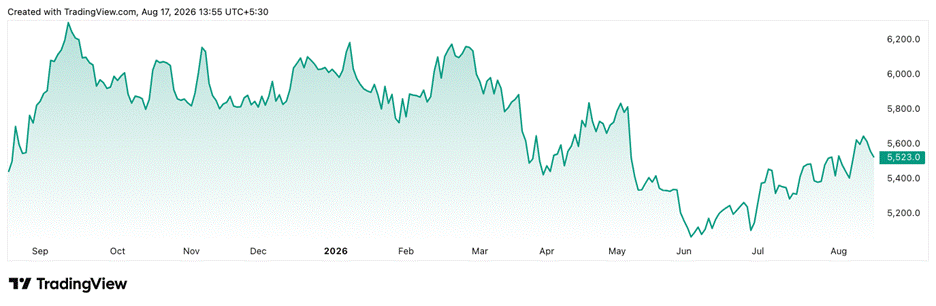
Britannia’s stock has seen sideways momentum for the last few quarters after hitting a peak in the last quarter of 2024. The YoY growth in key metrics is still quite good. In the recent quarter, Britannia reported 9.5% YoY revenue growth and 13.6% PAT YoY growth. These are good numbers when we look at the headwinds due to geopolitical issues which could have impacted demand.
Evaluating Key Input Costs and Margin Pressures
A key issue to look at is the input cost for Britannia. A key item that stands out is the massive increase in industrial fuel cost compared to the year-ago period. The industrial fuel cost increased 69% YoY in the recent quarter, which reflects higher fuel prices. Most of the other input items showed a mixed picture, with -7% YoY growth in flour price, 11% YoY growth in milk price, and 3% YoY growth in sugar price. If the geopolitical issues linger on for the next few quarters, we could see a steady increase in these input prices, which can put a damper on margins.
Britannia 1-year price chart
#2 Varun Beverages
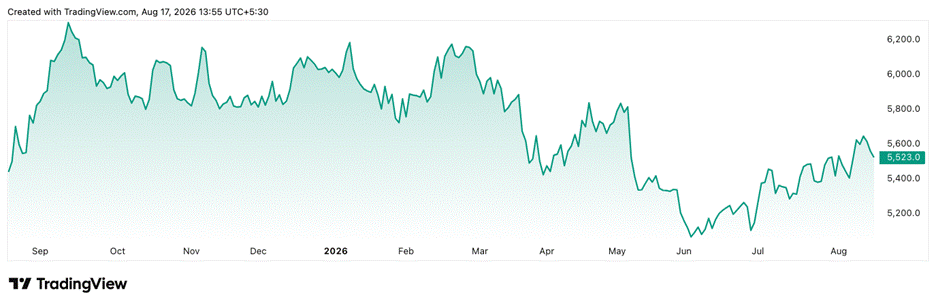
Varun Beverages stock has declined by 15% YoY. On the other hand, the company reported a 15.1% YoY growth in PAT in the recent quarter. This has made the stock multiple more reasonable at a PE multiple of 44.
International volumes were up 38.4% YoY which should improve the diversification benefit for the company. On the other hand, higher input costs for PET resin can hurt margins.
The recent quarterly revenue was Rs 8,451 cr which was a 20.4% YoY growth. This is a good growth trajectory when we look at some of the macro headwinds faced by the company in the recent quarter. The PAT margin was 18% in the recent quarter with a Rs 1,525 cr PAT.
Varun Beverages 1-year price chart
#3 Nestle India
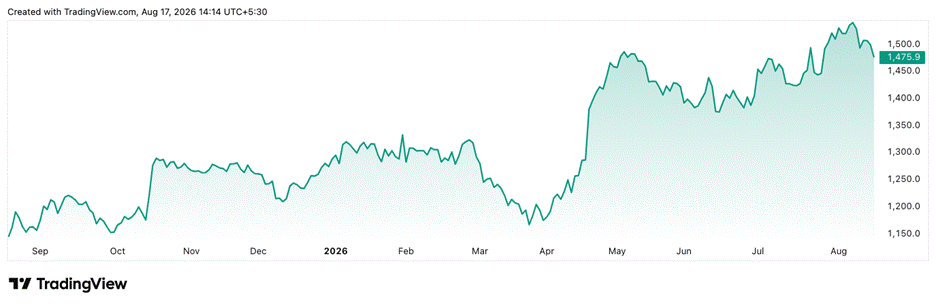
Nestle India’s stock has risen by 34% over the last year. This has been supported by a 25.2% YoY revenue growth and a massive 48% YoY growth in PAT. The margin expansion has been supported by the premiumization trend, where the company is able to show good growth in high-priced products like Nespresso.
On the other hand, Nestle India faces headwinds due to higher costs of milk solids, coffee beans, and edible oil. While these headwinds are temporary due to recent climate impact, investors should closely watch if the company is able to maintain its margins despite the higher input costs.
Nestle India 1-year price chart
Britannia, Varun Beverages, and Nestle India comparison
The Q1 FY27 revenue of Britannia was Rs 4,964 cr, which was a 9.5% YoY growth. The PAT was Rs 591 cr and PAT margin was 11.9%. The biggest strength for Britannia is the massive direct distribution capacity to 50 lakh+ retail outlets.
Varun Beverages is expanding rapidly in international regions which gives the company an additional growth lever. The recent quarter showed 20.4% YoY revenue growth with revenue of Rs 8,451 cr. The PAT margin was 18% with PAT of 1,525 cr.
Nestle India reported revenue of Rs 6,378 cr in the recent quarter with YoY growth of 25.2%. The PAT margin was 15.3% and PAT was Rs 975 cr. Aggressive rural growth is helping Nestle India improve its addressable market base.
| Particulars | Britannia | Varun Beverages | Nestle India |
| Q1 FY27 revenue | Rs 4,964 crore | Rs 8,451 cr | Rs 6,378 cr |
| YoY growth | 9.5% | 20.4% | 25.2% |
| EBITDA Margin | 16.80% | 27.72% | 24.12% |
| PAT | Rs 591 cr | Rs 1,525 cr | Rs 975 cr |
| PAT margin | 11.9% | 18.0% | 15.3% |
| Strengths | Direct distribution to 50 lakh+ retail outlets | International expansion through acquisition | Aggressive rural expansion |
Peer analysis
The EV to EBITDA ratio of Britannia is 33.69, Varun Beverages is 24.55, and Nestle India is 48.50 compared to industry median of 28.41. The Return on Capital Employed (ROCE) of Britannia is 56.00%, Varun Beverages is 19.58%, and Nestle India is 84.10% compared to industry median of 14.03%. The Return on Equity (ROE) of Britannia is 53.52%, Varun Beverages is 16.2%, and Nestle India is 73.17% compared to industry median of 10.48%.
We can see from these metrics that while the valuation multiple of these FMCG stocks might be high, they also deliver a very good ROCE and ROE.
| Peer comparison | |||
| Company | EV/EBITDA | Return ratios (%) | |
| ROCE (%) | ROE (%) | ||
| Britannia | 33.69 | 56.00 | 53.52 |
| Varun Beverages | 24.55 | 19.58 | 16.2 |
| Nestle India | 48.50 | 84.10 | 73.17 |
| Industry Median | 28.41 | 14.03 | 10.48 |
Whether the stocks deliver from here on, only time will tell. It may be a good idea to add Britannia, Nestle India and Varun Beverages to the watchlist.
Disclaimer
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation. Only in cases where the data was unavailable have we used an alternative, widely used, and accepted source of information
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
About the Author: Rohit is a seasoned financial writer with over a decade of experience covering Indian and international stocks. He specializes in converting complex financial data into actionable insights that can help readers make better calls. He covers macroeconomic trends globally, which gives a better analysis of the growth runway for companies in key sectors.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article. The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities, or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources, and only after consulting such independent advisors as may be necessary.