



Not every auto-component company is built the same. Some compete on manufacturing scale, while others compete on lower costs. But not this company. Incubated at the IIT Bombay campus in 2007 by its faculty and alumni, it built its business around something far more difficult to replicate: control algorithms embedded inside vehicle Electronic Control Units (ECUs).
Every time you press the self-starter switch of your motorcycle or scooty, there’s a good chance this company’s technology is at work. It controls one of the most critical electronic systems inside modern two-wheelers, making stop-start technology smoother, quieter, and more reliable.
More importantly, it dominates the market. The company is SEDEMAC Mechatronics, and it controls over 80% of the incremental Integrated Starter Generator (ISG) ECU market in India’s two- and three-wheelers. Instead of selling a commodity auto part, it has built a technology moat around the electronic brain that powers silent-start systems.
Now, the bigger question is whether this IIT Bombay spin-off can maintain its dominant position and continue growing.
Join now
SEDEMAC Mechatronics: Solving a Small Problem That Had Big Consequences
Every time a motorcycle starts with the push of the self-starter button, the vehicle’s electronics need to know the exact position of the engine piston before restarting it. Traditionally, this is done using physical sensors placed inside the engine. These sensors tell the ECU about the engine’s position, allowing it to restart smoothly.
The process worked well, but there was a problem. The sensor is constantly exposed to high temperatures, vibrations, dust, and engine oil, which leads to failures and higher maintenance costs.
SEDEMAC solved the problem differently. Instead of using a physical sensor, it developed and patented Sensorless Control (SLC) algorithms that are embedded in its ECUs. The controller estimates the piston position by analysing the engine’s electrical signals in real time, eliminating the need for additional sensors. This small innovation led to lower system costs, better reliability, and easy integration on existing engines without requiring engine redesign.
This combination of hardware and proprietary embedded software has helped SEDEMAC capture over 80% of the incremental ISG market in India’s two- and three-wheelers.
Its timing is also favourable. Rising emission norms, tighter fuel-efficiency requirements and the increasing electronic content in two- and three-wheelers are pushing OEMs to adopt more sophisticated engine-control systems. As vehicles become more software-driven, the value of the electronic controller continues to increase.
Switching Cost and OEM Stickiness
An ECU is deeply integrated into a vehicle platform. During the design phase of an engine, it undergoes years of testing, calibration, and validation before commercial production begins. Once SEDEMAC’s ECU is tuned for a particular engine architecture, replacing it means repeating the entire cycle of development. This makes switching both expensive and time-consuming for OEMs.
SEDEMAC has strengthened this advantage further by increasing the functionality of its ECUs. Today, the company offers combined ISG + Electronic Fuel Injection (EFI) ECUs, allowing a single controller to manage multiple engine functions. As more functions are consolidated into one unit, the supplier becomes even more deeply integrated into the vehicle platform, raising switching costs further and creating a distinct competitive advantage.
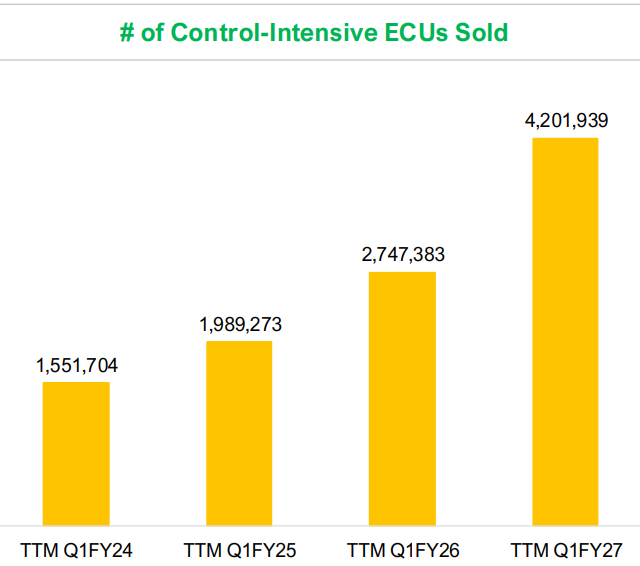
The sales number itself validates the story. At the end of Q1FY27, the TTM (Trailing Twelve Months) sales were over 42 lakh units of control-intensive ECUs, compared to 27.5 lakh units in the same period the previous year.
Growing Sales of ECU Units
Financial Profile: Software Economics in Manufacturing
SEDEMAC’s IP-led business model generates financial metrics more akin to a software company than a traditional auto-component manufacturer. Because its competitive edge lies in embedded firmware rather than heavy tooling, the company scales revenue with high capital efficiency.
SEDEMAC Mechatronics: Financial Performance
| Metrics | FY24 | FY25 | FY26 |
| Revenue from Operations(₹ crore) | 530 | 658 | 1,058 |
| EBITDA Margin (%) | 15.7 | 19.0 | 21.0 |
| Net Profit (₹ crore) | 5.9 | 47.1 | 103.6 |
| ROCE (%) | 29.0 | 34.0 | 40.0 |
Quarterly Performance Snapshot
| Metrics | Q1FY26 | Q1FY27 | YoY Growth |
| Revenue from Operations(₹ crore) | 217.4 | 309.8 | 42.5% |
| Net Profit (₹ crore) | 17.1 | 33.3 | 94.7% |
In FY26, revenue crossed ₹1,000 crore for the first time, growing 61% YoY, and in the last three years, it has grown at a CAGR of 36%. The momentum continued into Q1FY27 as well, with revenue growing by 42.5% YoY to ₹309.8 crore. Net profit nearly doubled during the period to ₹33.3 crore. Return on capital employed (ROCE) expanded to over 40% in FY26, from 29% in FY24.
The Growth Vectors Beyond Silent-Start
SEDEMAC is now working on replicating the success of ISG + EFI ECU to other segments of the automotive industry.
#1 EV Motor Control Units (MCUs)
SEDEMAC is already ramping up Motor Control Units (MCUs) for electric two- and three-wheelers. Similar to its ISG ECUs, these MCUs replace physical sensors with proprietary control algorithms, increasing EV reliability. The revenue contribution of EV products has already increased to 7.4% in FY26, from 1.7% in FY25.
#2 Industrial Generator Controllers
SEDEMAC already commands a 75% market share in domestic generator control units, and is also expanding into North American home-standby generator markets.
#3 Commercial Vehicle Electronics
Preparations are underway for the launch of After-Treatment Control Units (ACUs) in the second half of FY27. At the same time, the development of engine management ECUs and motor controllers for commercial vehicles continues to progress.
#4 Cord and Cordless Power Tools
SEDEMAC has secured its first design win in the power-tools market for a sensorless motor controller. Management believes the addressable market in this segment is significantly larger than the company’s current automotive opportunity. Annually, more than 300 million power tools are sold globally every year, giving a strong runway of growth. Production of controller units is expected to start over the next four to five quarters.
If these initiatives succeed, SEDEMAC’s growth story gradually shifts from increasing ISG penetration to becoming a broader automotive electronics company.
Management Outlook on Growth
The management is optimistic about maintaining the growth momentum and is currently focusing on four key growth levers:
- Wider adoption of ISG technology in high-volume motorcycle models,
- Continued ramp-up of Motor Control Units (MCUs) for electric two- and three-wheelers,
- Increasing exports of ISG ECUs for three-wheelers, and
- Commercial vehicle electronics programs
However, the management has flagged a few near-term headwinds, including higher semiconductor prices and commodity costs, which could put mild pressure on margins. But if execution remains strong, FY27 could be another year of strong volume-led growth.
Valuation: Great Business, High Expectations
SEDEMAC has delivered almost everything investors look for: a differentiated product, strong execution, high capital efficiency, and a long runway for growth. The market has rewarded the company with a premium valuation.
Since its IPO in March 2026, SEDEMAC share price has rallied over 100%, making a new high of ₹2,978.
SEDEMAC Mechatronics Share Price
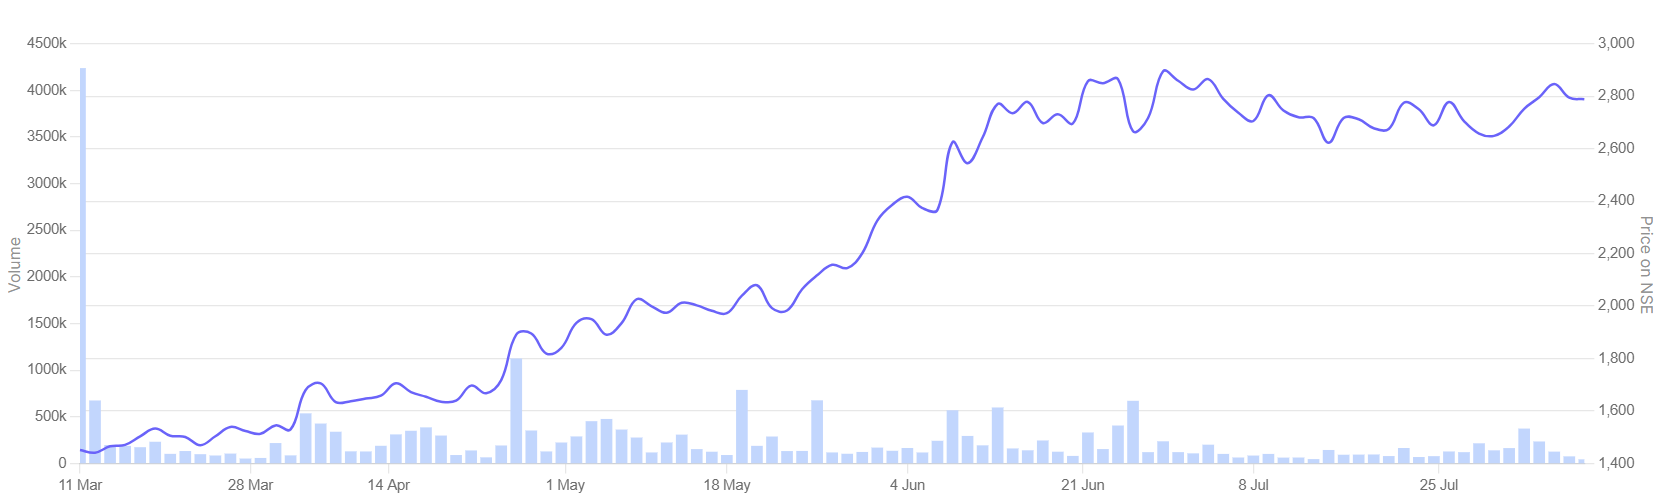
The rally pushed the stock’s trailing price-to-earnings (PE) multiple to over 100X. With a limited listed history, there isn’t enough data to compare its valuation against its own historical averages. But compared with most listed auto-component companies, SEDEMAC is trading at a significant premium. This leaves little margin for error.
Any slowdown in production or delay in new launches, or weaker-than-expected customer wins could weigh the stock down. There are other risks to watch as well. While SEDEMAC enjoys a dominant position in sensorless ISG ECUs, its newer businesses, particularly EV motor controllers and commercial vehicle electronics will compete against well-established global Tier-1 suppliers with significantly larger scale and R&D capabilities.
For now, SEDEMAC has shown that an Indian engineering company can build a global-quality, IP-led electronics business. The next leg of the story will depend less on proving its technology and more on proving that it can sustain its growth across multiple products, customers and end markets. You can include this stock in your watchlist and monitor how it executes its growth plans.
Disclaimer:
Note: We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Deepan Datta has spent over a decade studying stocks and mutual funds. His passion is to uncover interesting stories in the financial markets and share them through his writings with investors at large. He is focused on delivering clear, easy to understand and research-backed insights. Deepan began his career as a Research Associate at S&P Global, where he developed a strong foundation in financial research and data analysis.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, their employees (s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.