



Artificial intelligence is driving higher infrastructure investment. Gartner estimates global data centre system spending to grow 62.5% year-on-year to US$822 billion in 2026. Over the next four years, AI infrastructure spending is projected to reach US$1.6 trillion, creating a large opportunity for companies that build and manage the physical systems behind this growth.
The opportunity, however, is not spread evenly across markets. The US is expected to remain the key data centre market. Commissioned capacity in the country is projected to rise from 87 gigawatts (GW) to 233 GW by 2030. Notably, Artificial Intelligence-specific load is expected to surge almost 6X to 117 GW by 2030E from 20 GW in 2025, as per Black Box.
Expanding Capacity and the Integrator Opportunity
India is also expanding, with capacity expected to scale from around 1 GW to 5-6 GW by 2030. As AI, cloud computing and digital services expand, data centres need more than servers and software. They require companies that can design, install and manage the electrical, network, and other infrastructure needed to keep these facilities running.
This is creating a growing opportunity for IT system integrators and digital infrastructure solution providers. Against this backdrop, two companies stand out for different reasons.\
Join now
One has built a strong position in India’s data centre infrastructure market, while the other focuses more on the US and is expanding its presence in India. Their strategies offer two different ways to participate in the next phase of the data centre buildout.
#1 Dynacons Systems: Building India’s Sovereign and Enterprise Cloud Infrastructure
Dynacons Systems is a Digital Infrastructure Platform and a pure-play Systems Integrator. This means that rather than designing or manufacturing its own hardware, it acts as a strategic ecosystem partner between global technology vendors and enterprise customers.
Ecosystem Partnerships and the Annuity Lifecycle Model
The company partners with leading technology brands, including Apple, Microsoft, Cisco, Dell, Oracle, and Lenovo. Dynacons designs, implements, and manages customised end-to-end solutions. It has end-to-end capabilities to design, build, optimise, and modernise data centres.
This includes private and hybrid cloud deployments, hyper-converged infrastructure, AI infrastructure, enterprise backup, recovery, and disaster recovery automation. In addition, the company has three other business segments: Network and Cybersecurity, Digital Workplace Solutions, and IT Managed Services.
Shifting to High-Value Annuities
Instead of the traditional transactional IT procurement model, Dynacons uses an annuity-linked lifecycle model. It guides clients through the entire process: design, deploy, operate, monitor, refresh, and renew. This creates long-lasting relationships with high customer stickiness.
Data Centre Revenue Expansion and Structural Margin Gains
The company focuses primarily on high-barrier, security-sensitive and regulated markets such as banking, financial services and insurance (BFSI), government and public sector companies, and global corporates and enterprises. The Data Centre and Cloud Infrastructure business is its core business driver.
Data centre revenue grew 2.5x between FY23 and FY26. Revenue from this segment has grown at a CAGR of 52% over the past five fiscal years, from ₹60 crore in FY21 to ₹484 crore in FY26. Data centre solutions have consistently contributed to Dynacons’ overall revenue profile, growing from 14% of the mix in FY21 to 37% by FY26.
Marquee Contract Wins: RBI, NPCI, and GPU Cloud Deployments
This shift to a higher-value data centre mix has structurally boosted the company’s margins. EBITDA (earnings before interest, taxes, depreciation, and amortisation) margin more than tripled to 12.8% in Q1FY27 from just 4.2% in FY21. Similarly, net profit margin increased from 2.0% to 6.3% during this period.
Margin improvement was also driven by improved project economics and higher relative contributions from value-added services and annuity engagements. The company transitioned from historical maximum order sizes of up to ₹350 crore to ₹750 crore now. This has repositioned Dynacons to compete directly with much larger Tier-1 and global system integrators.
During Q1FY27, Dynacons won three marquee public sector and financial data centre wins. The first is a 5-year contract worth ₹750.8 crore from the Reserve Bank of India to implement Private Cloud Infrastructure across RBI data centres. Another order is worth ₹267.6 crore from National Payments Corporation of India for a Data Centre Augmentation mandate.
The third dedicated contract is worth ₹125.9 crore from the Central Bank of India and includes scaling up a private cloud, building a containerisation platform, and deploying servers powered by next-gen NVIDIA H200 Blackwell GPUs. These contracts have pushed the company’s total order book to ₹3,104 crore as of July 2026.
Execution Timelines and the ₹6,650-Crore Bidding Pipeline
The average execution timeline for this backlog is 18-24 months, with some long-term contracts spanning up to 5 years. In addition, Dynacons sees a bidding pipeline of approximately ₹6,650 crore across its business segments. The historical win rate is approximately 30% on its bidding pipeline, offering healthy conversion visibility.
Q1FY27 Financial Profile: Expanding Profitability and Zero Net Debt
During Q1FY27, Dynacons delivered a performance marked by margin expansion and improving profitability, despite a temporary fall in revenue growth. Revenue from operations fell 4.6% year-on-year to ₹313.7 crore due to execution and timing mismatch. Despite that, EBITDA grew 26.5% to ₹40.2 crore, driven by a better product mix and value-added services.
EBITDA margin expanded by 315 bps to 12.8% as the contribution from high-margin contracts rose. As a result, net profit remained stable at ₹19.8 crore. The company has very low net debt and has been free cash flow positive for the last four financial years.
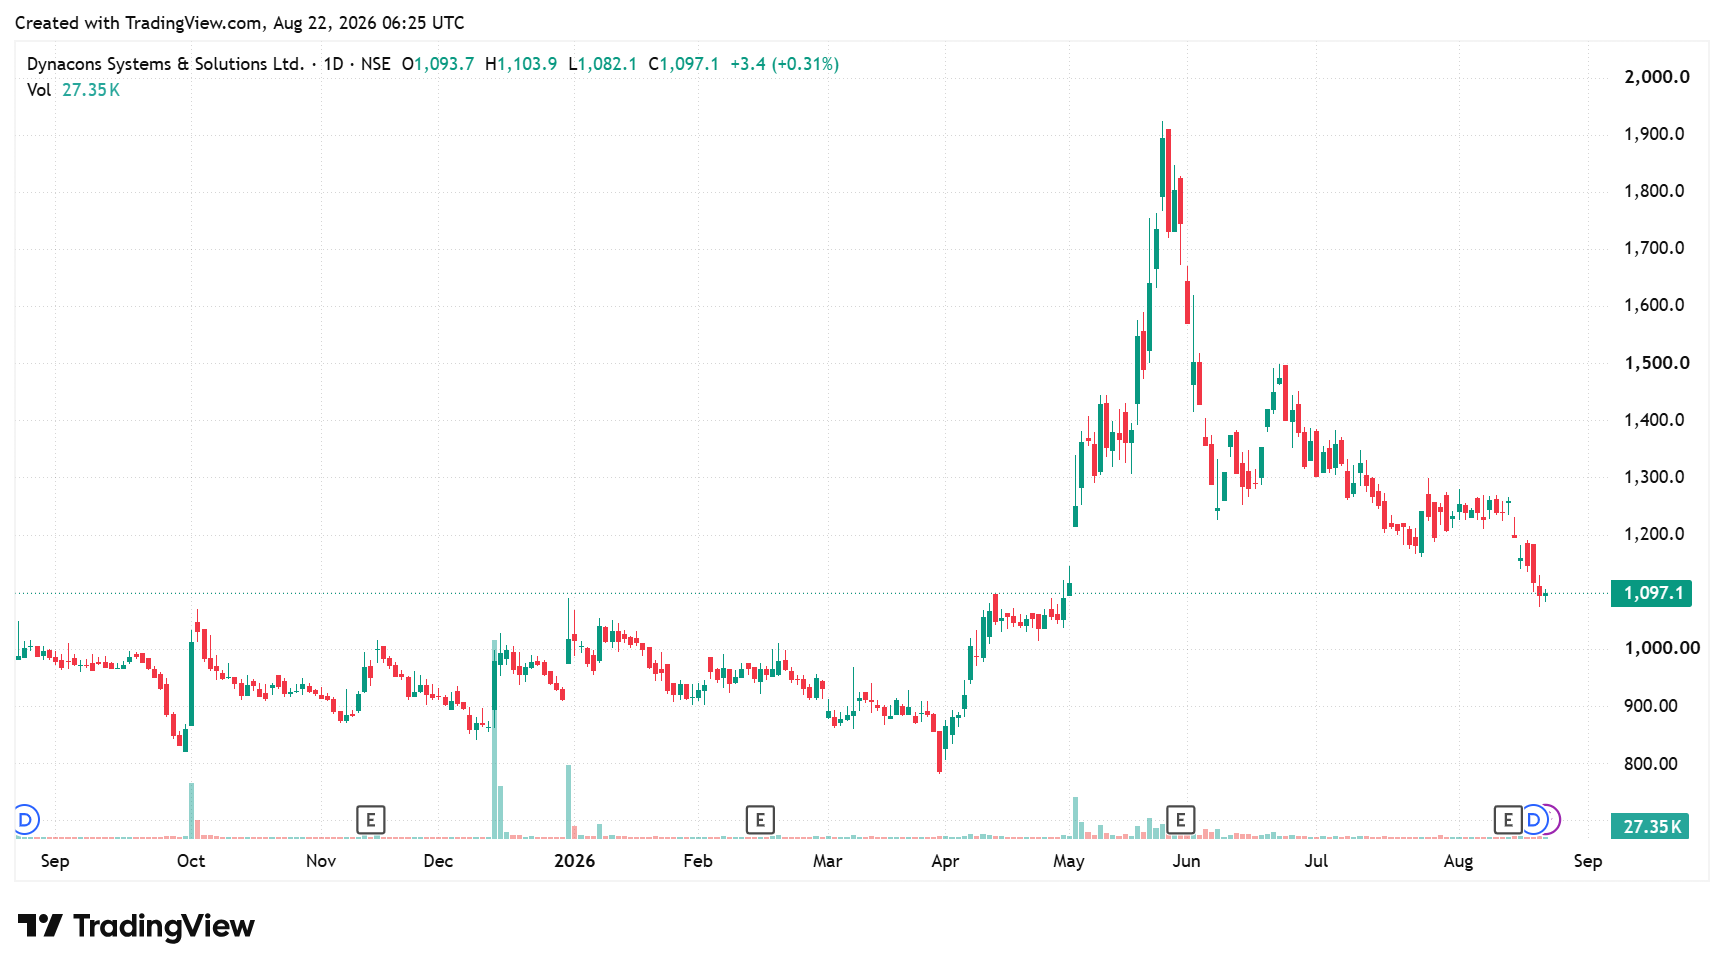
#2 Black Box: Scaling Operations in the North American Hyperscaler and Gigawatt Buildout
Black Box is also a digital infrastructure services provider and integrator, but it operates globally. The company delivers network and system integration services, solutions, support services, and technology products across the United States, Europe, India, the Asia-Pacific, the Middle East & Africa, and Latin America.
It serves a wide array of industries, including financial services, technology, healthcare, retail, public services, and manufacturing. The company delivers its services through three primary business segments. Global Solutions Integration (GSI) accounts for 84% of revenue.
Revenue Segmentation and Dominance in the US Hyperscaler Market
GSI is the largest business engine. It provides digital infrastructure services across five key horizontals: data centre connectivity, enterprise networking, modern workplace, connectivity infrastructure, and cybersecurity. Technology Product Solutions contributes 14% to revenue, while other services account for 2%.
North America is Black Box’s dominant market. About 60% to 70% of the company’s addressable spend opportunity is targeted in the US, and 70% to 80% of current spend is focused there. The data centre business accounted for approximately 17% of Black Box’s total revenue in FY26. This is projected to nearly double to approximately 30% of total revenue in FY27.
Gigawatt-Scale Data Centre Execution and the ₹8,986-Crore Backlog
It is currently the only Indian-origin digital infrastructure company executing gigawatt-scale data centre programs globally. Black Box’s data centre business operates as a 100% services business. This includes delivering high-value data centre connectivity infrastructure, complex fibre installs, structured cabling, and ongoing networking support for hyperscalers and colocation providers.
The company’s strong order book highlights the demand. Its order backlog was ₹8,986 crore at the end of Q1 FY27, providing 1.5 years of revenue visibility based on FY26 revenue of ₹6,322 crore.
The tenure of Black Box’s data centre projects ranges from 24 to 36 months, compared to the normal 6-12 months for standard enterprise projects. This improves the company’s long-term revenue visibility and predictability. The company won a ₹1,240 crore data centre project from a US hyperscaler. Major revenue is scheduled to be booked in FY28.
Targeting the $40-Billion AI Addressable Market: Multi-Year FY28 Horizon
Black Box estimates a total addressable opportunity of US$40 billion out of US$1.6 trillion in total AI infrastructure spending. Although Black Box is evaluating expansion into European and Indian data centre markets, the US remains its key focus. Management expects investment in data centre build-outs to come from enterprise IT spending, with a slight lag.
Q1 Financials and FY27 Guidance: Profitability Across Global Footprints
This lag is anticipated to create a growth cycle starting in FY28 and beyond. Financially, Black Box’s revenue grew 24% year over year to ₹1,719 crore. EBITDA increased 38% to ₹160 crore, while margins expanded 90 bps to 9.3%. Net profit increased 18% to ₹47 crore. The company expects revenue to grow by 23-27%, EBITDA (27-32%) and Net profit (38-50%) in FY27.
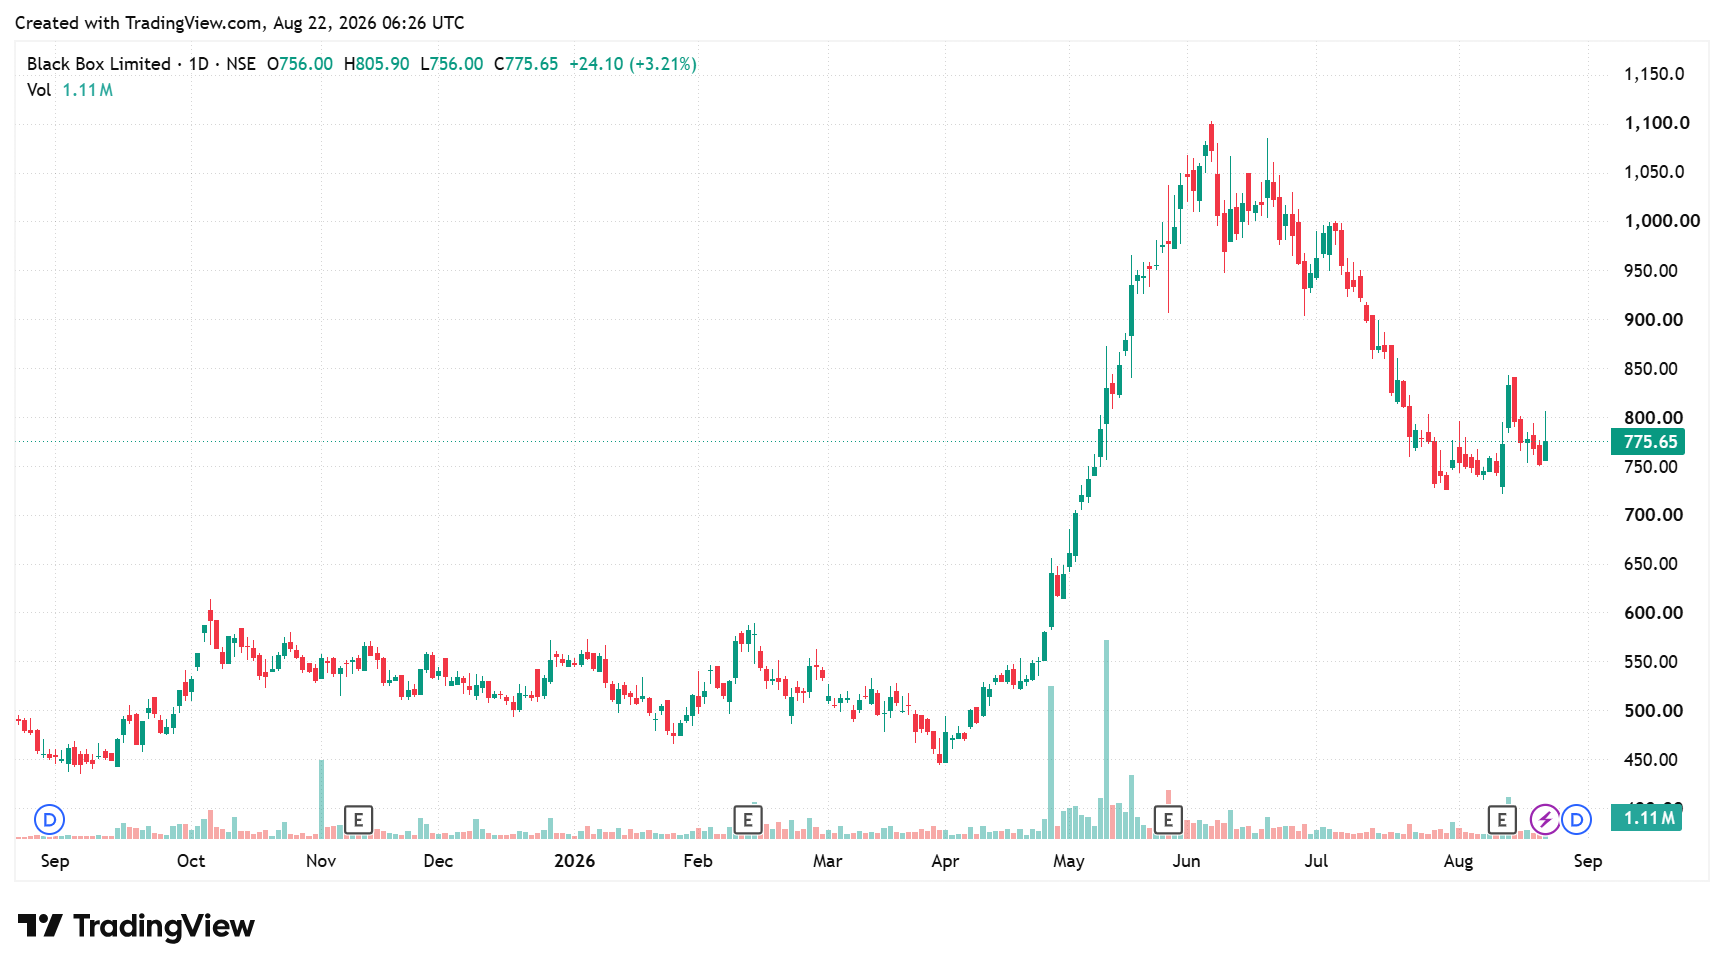
Here’s a look at the Q1FY27 performance of both companies:-
| Particulars | Dynacons Systems | Black Box |
| Revenue (Growth) | ₹313.7 crore (-4.6% YoY) | ₹1,719 crore (+24%) |
| EBITDA (Growth) | ₹40.2 (+26.5% YoY) | ₹160 (+38% YoY) |
| Margin | 12.8% | 9.3% |
| Net Profit (Growth) | ₹19.8 crore (Flat) | ₹47 crore (+18% YoY) |
| Order Book | ₹3,104 crore | ₹8,986 crore |
| Source: Management Commentary and Investor Presentations | ||
Black Box has the larger revenue base, stronger Q1 revenue growth, and a ₹8,986 crore order book. Dynacons, however, delivered a higher EBITDA margin of 12.8% despite a 4.6% decline in revenue, compared with Black Box’s 9.3% margin.
Valuation Realities: Why Dynacons Trades at 16x While Black Box Commands 48x P/E
Dynacons’ Return on Capital Employed (ROCE) and Return on Equity (ROE) are higher than Black Box’s, indicating stronger capital and operational efficiency. Valuation-wise, Black Box is currently trading at double the industry median and at a premium to its historical five-year median. Dynacons, on the other hand, currently trades at a discount.
| Peer Comparison (X) | ||||
Company | Price-to-Earnings Multiple | Return Ratios | ||
| Company | 5Y Median | ROCE (%) | ROE (%) | |
| Black Box | 48.2 | 34.4 | 22.2 | 26.8 |
| Dynacons | 16.5 | 18.4 | 29.7 | 31.1 |
| Industry | 24.7 | 15.4 | 12.5 | |
| Source: Screener.in (Data as of 21 August 2026) | ||||
India’s data centre buildout is undoubtedly creating opportunities across system integration and digital infrastructure. To this end, Dynacons has a stronger India-focused business, supported by a ₹3,104 crore order book and rising data centre contribution.
Black Box, on the other hand, has greater exposure to the US hyperscaler buildout, with an ₹8,986 crore backlog and a US$40 billion addressable AI infrastructure opportunity. Dynacons offers a lower valuation, while Black Box commands a premium for its scale and US exposure. You could keep these names on your watchlist to track their execution.
Disclaimer
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation. We used an alternative, widely used, and accepted source of information only when the data was unavailable.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
About the Author: Madhvendra has been deeply immersed in the equity markets for over seven years, combining his passion for investing with his expertise in financial writing. With a knack for simplifying complex concepts, he enjoys sharing his honest perspectives on startups, listed Indian companies, and macroeconomic trends.
A dedicated reader and storyteller, Madhvendra thrives on uncovering insights that inspire his audience to deepen their understanding of the financial world.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources, and only after consulting such independent advisors as may be necessary.