



Ask investors what a microcap is and they will describe a penny stock. A company nobody has heard of trading with low volumes and with a promoter who gives interviews about a turnaround.
But that’s not what the microcap segment actually is.
Most investors get scared or worries when they hear about microcaps. But there’s an index, the Nifty Microcap 250, which tracks the top microcap companies in India. The index currently has a combined market value of Rs 17.96 trillion (tn) across those 250 names, which works out to an average of a little over Rs 70 bn each.
These are not shell companies. Several of them are household names with decades of operating history that simply happen to sit below the index cut-off.
What makes the microcap segment difficult is not company quality but three specific things:
The first is coverage. A Nifty 50 company is followed by multiple analysts. Many microcaps are followed by hardly anyone.
The second is liquidity.
And third, it’s where the damage concentrates when markets turn down. In the correction between September 2024 and March 2025, large caps fell about 17% while small caps fell about 22%. Microcaps were hit even harder.
But on the flip side, if you do find a good name, the gains could be huge.
Keeping that in mind, let’s look at 5 fundamentally strong microcaps in India that are also undervalued right now.
We have applied filters of a dividend payout above 10%, return on equity and capital employed above 10%, profit margin above 5%, receivable days under 90, profit growth in each of the last three years, and debt-to-equity below 1.
For valuation, the current price-to-earnings ratio had to be below the company’s five-year median.
Eighteen companies cleared the fundamental filter and these five are the cheapest against their own historical valuations.
#1 Redtape
First on the list is Redtape.
The company trades at a PE of 26.7 times against a five-year median of 42.6, a discount of 37%.
The footwear and apparel company earns 26.9% on equity and 31.3% on capital, converts 10.1% of revenue to profit, and collects its money in 24 days, which for a business selling through 435-plus stores plus distributors is genuinely tight.
Its debt-to-equity is 0.38 and it pays out 45% of profits.
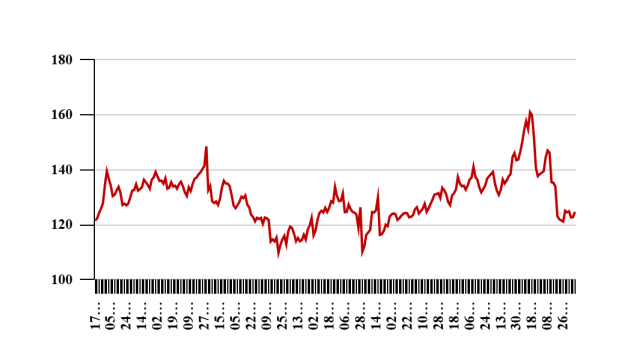
The interesting part is Redtape reported its highest-ever first-quarter profit on 10 August, with revenue of Rs 4.8 bn, EBITDA of Rs 1.01 bn, and profit of Rs 470 m.
So, what justifies its undervaluation?
It reflects a market that has stopped paying up for branded consumption after a long de-rating across the sector. It remains to be seen how and when the company bounces back.
Redtape – 1 Year Share Price
Data Source: BSE
#2 Privi Speciality Chemicals
Second is Privi Specialty Chemicals.
It makes aroma and fragrance chemicals, largely from crude sulphate turpentine, and is India’s largest exporter in the category.
The company’s operating numbers are the strongest on this list. Its FY26 revenue rose 22% to Rs 25.6 bn and profit 75% to Rs 3.28 bn, at an EBITDA margin of 25.76%.
The June quarter continued it, with profit up 36% to Rs 842 m. Its return on equity is 28.2%. The management has set out a target of Rs 50 bn of revenue and Rs 10 bn of EBITDA by FY30.
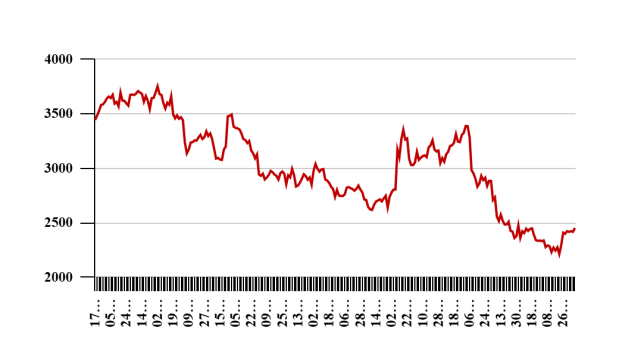
The stock is up about 42% in a year and sits close to its all-time high of Rs 3,700 reached in June 2026, and trades at 9.6 times book value. Its dividend payout is 10.9%.
Its PE of 36 is below its five-year median of 50 but do note that the median was set during years when Privi’s earnings were depressed. A PE falling because profits tripled is a different thing from a PE falling because the price fell.
There is also a governance point that belongs in plain sight. Its promoter holding has fallen 13.4 percentage points over three years, to 60.6%. Sustained promoter selling into a rising share price is not disqualifying, but it deserves an explanation before capital is committed.
Privi Speciality Chemicals – 1 Year Share Price
Data Source: BSE
#3 Gujarat Pipavav Port
Third is Gujarat Pipavav Port.
On the raw numbers this is the cleanest business in the group.
A 38.1% profit margin, 31.8% return on capital, no debt at all, receivables collected in 13 days, and a 100% payout ratio.
It currently trades at 14.1 times earnings against a five-year median of 19.4.
The reason it’s cheap is not about the numbers above. The port operates under a concession from the Gujarat Maritime Board that runs to September 2028. That is roughly two years away.
An extension is provided for and generally expected, but until it’s signed an investor owns a port operator whose legal right to operate the port has a visible expiry date.
That single fact explains the valuation gap between this company and other listed Indian port assets.
The 100% payout should be read in the same light. A company distributing everything it earns is either extremely confident about its cash flows or has no reason to retain capital for reinvestment.
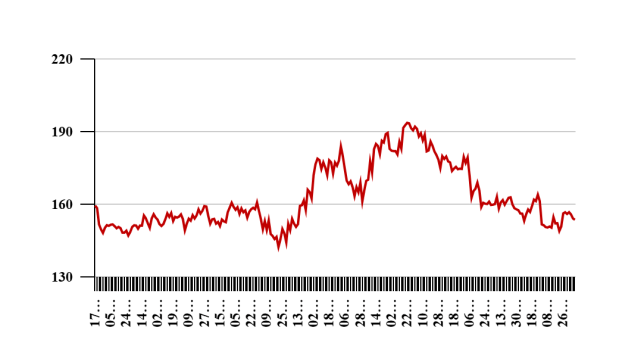
Gujarat Pipavav Port – 1 Year Share Price
Data Source: BSE
#4 Godrej Agrovet
Fourth on the list is Godrej Agrovet.
It’s a company with animal feed, crop protection, palm oil, and dairy, across a group with a long institutional history.
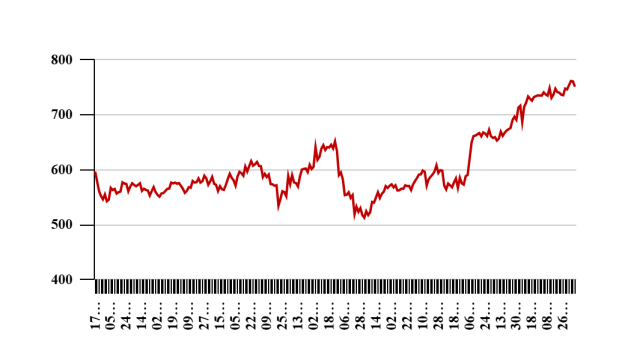
Its return on equity of 19.3% and capital of 22.6%, receivables at 16 days, debt-to-equity of 0.26, and a 40% payout are reasons why it appears on this list.
Also, it currently trades at a PE of 21.2 against a five-year median PE of 28.7.
That said, its profit margin of 6.5% is thin, barely clearing the 5% threshold, which is a function of the businesses it is in.
Feed and palm oil are structurally low-margin. More significantly, profit growth in the latest year was 4.7%, against 40.7% and 17.6% in the two years before.
That deceleration is likely why the stock has de-rated, which makes this the most conventional value proposition in the group. It’s a decent business in slow-margin categories, priced low by the market because growth has slowed.
Godrej Agrovet – 1 Year Share Price
Data Source: BSE
#5 Canara Robeco Asset Management
Last is Canara Robeco AMC. It’s India’s second-oldest asset manager, a joint venture between Canara Bank and ORIX Corporation Europe.
It earns 30.3% on equity, 41.1% on capital, converts 44.9% of revenue to profit, and carries no debt.
Asset management at scale is an attractive business model. Its quarterly average assets under management crossed Rs 1.11 tn.
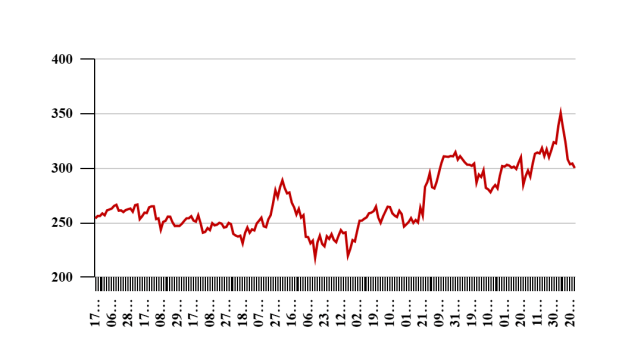
Canara Robeco AMC listed on 16 October 2025. So, a five-year median price-to-earnings ratio is not available but the stock does trade below its historical PE. The IPO was priced at Rs 266 and the stock currently trades around Rs 254.
Canara Robeco Asset Management – 1 Year Share Price
Data Source: BSE
Conclusion
The purpose of a screen is to shorten the list of stocks for research.
Of the five names here, Redtape shows the widest gap between operating results and share price, with a record June quarter but the stock has gone nowhere for a year.
Gujarat Pipavav is the cleanest business. Privi has the best growth rate but the least convincing claim to being cheap. Godrej Agrovet is the plainest value case, with slowing growth as the reason for the discount. Canara Robeco is an excellent business that has not been listed long enough.
The point from the introduction still stands. These stocks are thinly covered and thinly traded.
Evaluate each company’s business quality, financial performance, management execution, corporate governance, and valuation as key factors before drawing any investment conclusions.
Happy investing.
Disclaimer: This article is for information purposes only. It is not a stock recommendation and should not be treated as such. Learn more about our recommendation services here…
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary