



A stock can look cheap for a very good reason. The business may be struggling, margins may be under pressure or the growth that investors once expected may simply not be coming through.
The more interesting opportunities are often in companies where something is beginning to change, but the market has not fully priced it in yet.
That is what makes Vijay Kedia’s portfolio worth examining.
His holdings range from businesses with improving earnings and large order books to companies trying to move into entirely new areas of growth. The common thread is not that these stocks are cheap, but that there is a potential change in the earnings trajectory.
The latest portfolio data shows Kedia holding stakes in 23 listed companies, with the portfolio valued at around Rs 14.15 billion (bn) as of 21 August. There have also been some notable changes in the June quarter, including a new position in Eimco Elecon, a higher stake in Websol Energy Systems and reductions in Innovators Facade Systems and Affordable Robotic & Automation.
That makes it useful to look at some of his holdings not simply as “Kedia stocks”, but as businesses where the next few years could look quite different from the last few.
#1 Atul Auto
First on our list is Atul Auto.
Atul Auto makes three-wheelers for passenger and cargo applications, with products spanning diesel, petrol, CNG and electric powertrains. The company is trying to grow its conventional three-wheeler business while building a larger presence in electric mobility.
Atul Auto is one of the larger holdings in Vijay Kedia’s portfolio. Kedia held 18.2% of the company at the end of June 2026, while Kedia Securities held another 2.71%, taking the combined holding to 20.9%. The holding was unchanged during the quarter.
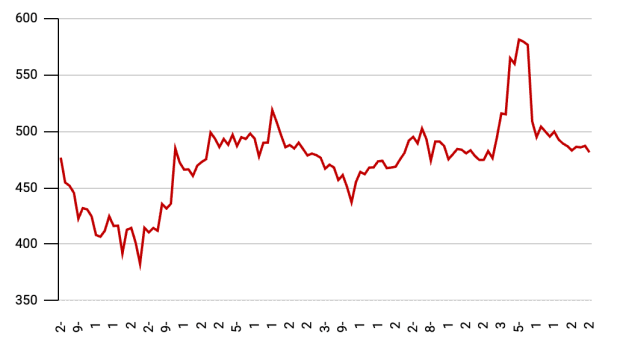
Atul Auto Share Price – 6 Months
Source: NSE
The business has been showing signs of a sharper recovery. FY26 sales grew 14%, while the EBITDA margin improved to 10% from 7% in FY25. Higher capacity utilisation and tighter cost control helped the company improve profitability as volumes recovered. Q1 FY27 sales grew 42.97% year-on-year, while the EBITDA margin stood at 7.72%, compared with 6.55% a year earlier. Higher three-wheeler volumes drove the growth, with sales volumes rising 42.5%.
Atul Auto spent Rs 107 m on capital expenditure in FY26, compared with Rs 160 m in FY25. Looking ahead, the company plans to consolidate manufacturing at its Ahmedabad facility, which has installed capacity of around 60,000 vehicles a year. Management says the facility can meet anticipated demand for several years and expand capacity with minimum capex. The company has no outstanding term borrowings.
At Rs 481, the stock trades at 27.7 times earnings, a 61% discount to its five-year median PE of 71 times.
#2 Innovators Facade Systems
Next on the list is Innovators Facade Systems.
Innovators Facade Systems designs, engineers, fabricates and installs facade systems for buildings. Its offerings include glazing and curtain walls, doors and windows, skylights, canopies and different forms of cladding.
The company is among the stocks in Vijay Kedia’s portfolio, although his holding has declined. Kedia held 8.71% at the end of June 2026, down from 10.66% at the end of March, after selling more than 3,66,000 shares during Q1 FY27.
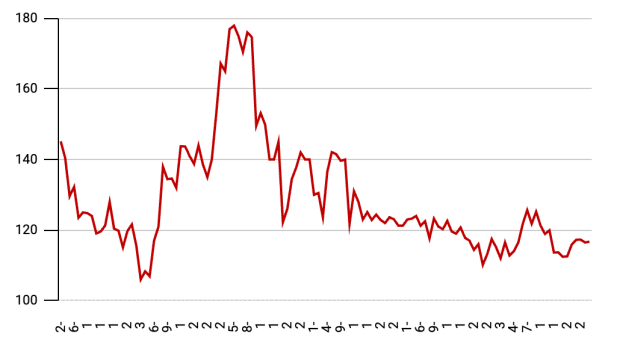
Innovators Facade Systems Share Price – 6 Months
Source: NSE
The financial performance has been mixed as FY26 sales grew 3%, while the EBITDA margin fell to 13% from 15% in FY25. The pressure came despite a strong order flow, highlighting the importance of project execution and costs in a business where raw material prices and competitive conditions can affect margins.
Looking ahead, Innovators Facade Systems spent Rs 80 m on capex in FY26, mainly on leasehold improvements and plant, machinery and equipment to support higher production and future demand. The company ended FY26 with a record Rs 7.4 bn order book and has since won fresh orders, including a Rs 768 m Lodha Developers project in August.
At Rs 117, the stock trades at 16.2 times earnings, around a 46% discount to its five-year median PE of 29.8 times.
#3 Affordable Robotic & Automation
Third on our list is Affordable Robotic & Automation.
Affordable Robotic & Automation provides industrial automation solutions, including robotic welding, automated parking and warehouse automation through its Humro subsidiary. The company is now trying to move beyond project-based automation and build a larger robotics business.
The stock is part of Vijay Kedia’s portfolio. Kedia held a 7.01% stake at the end of June 2026, or 831,043 shares.
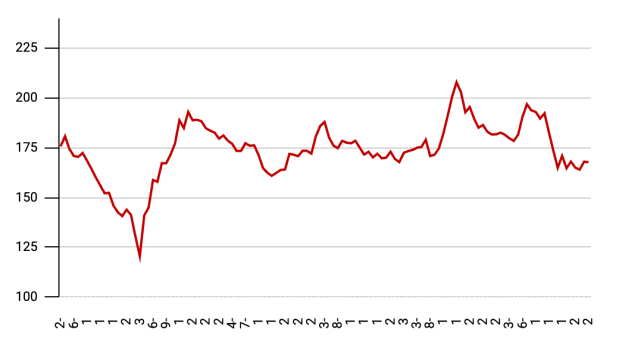
Affordable Robotic & Automation Share Price – 6 Months
Source: NSE
Meanwhile, Q1 FY27 sales fell 41.2%, while the company continued to report an operating loss in Q1 FY27, with EBITDA margin at -29.6%, compared with -10.4% a year earlier. The company said around Rs 130 m of sales scheduled for Q1 moved into Q2 because of project execution and dispatch timing, rather than a loss of orders. FY26, however, was a year of margin improvement, with the company prioritising higher-quality, profitable projects over chasing revenue.
Looking ahead, the bigger bet is Humro. The business has secured Rs 480 m of strategic investment, of which Rs 240 m has been received, while the confirmed order book stood at around Rs 1.49 bn in August. The company has also booked another Rs 220 m of orders since June. Management said Humro will manufacture five products locally this year, with the aim of reducing costs, while the funding provides capital for this expansion.
At Rs 167, the stock trades at 34 times earnings, a 53% discount to its five-year median PE of 72 times.
#4 Repro India
Fourth on our list is Repro India.
Repro India provides printing and publishing solutions, with its business increasingly moving beyond conventional printing towards print-on-demand, digital content management and technology-enabled book distribution. The company works with publishers, authors and content creators and connects their books with online marketplaces and readers.
The stock is one of the holdings in Vijay Kedia’s portfolio. Kedia held 6.32% of Repro India at the end of June 2026. The promoter group held 46.71%, while foreign portfolio investors held 9.05% at the end of March 2026.
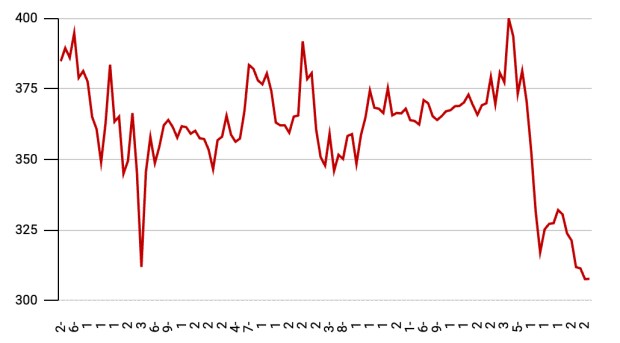
Repro India Share Price – 6 Months
Source: NSE
The latest numbers show a sharper improvement in the underlying business. Q1 FY27 revenue grew 20% year-on-year to around Rs 1.41 bn, the highest quarterly revenue in the company’s history. Digital business revenue grew 11% to Rs 1.04 bn, while the platform business grew 24% to Rs 740 M, giving it an annualised revenue run-rate of around Rs 3 bn. The company said Q2 FY27 revenue is expected to be higher than Q1, while the long-run business is expected to grow in double digits from its FY26 base.
Looking ahead, Repro is trying to build a more asset-light publishing ecosystem through print-on-demand, publisher integrations, e-commerce channels and data-driven content management. The company was debt-free with a cash surplus of around Rs 700 m at the end of Q1 FY27 and expects FY27 capex of only Rs 100-150 M. It has also incorporated Repro Books Inc. in the US to strengthen its international presence, while Repro DMCC in the UAE was dissolved in July 2026.
At Rs 309, the stock trades at around 1.27 times book value. A PE-based valuation is not meaningful at present because FY26 ended with a loss and Q1 FY27 profit was boosted by an exceptional gain of around Rs 1.67 bn from the Mahape land sale.
#5 TechD Cybersecurity
Last on our list is TechD Cybersecurity.
TechD Cybersecurity provides end-to-end cybersecurity services, including managed security services, security operations, vulnerability assessment and penetration testing, digital forensics, incident response and compliance. The company is now trying to move beyond a services-led model by building its own AI-powered cybersecurity products through its TechD One platform.
The stock is part of Vijay Kedia’s portfolio. Kedia held 5.26%, at the end of June 2026, unchanged from the previous quarter.
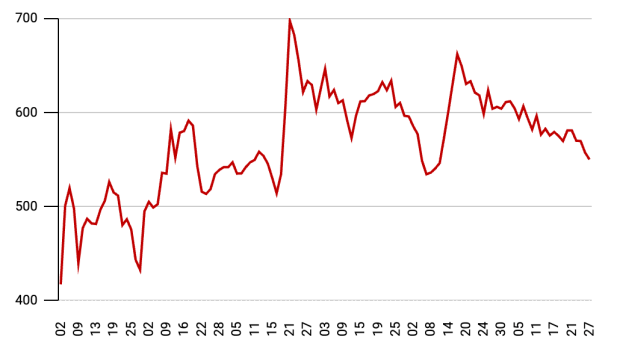
TechD Cybersecurity Share Price – 6 Months
Source: NSE
The business has been growing rapidly. FY26 revenue grew 73.9%, while the EBITDA margin improved sharply as the company used AI to automate repetitive tasks and reduce its employee costs. Management said employee expenses fell from over Rs 120 m to Rs 93.6 m, helping improve operating efficiency. The company also said it had a 98% customer renewal rate, suggesting that much of its business is coming from customers who continue to use its services.
Looking ahead, TechD is targeting Rs 750-800 m of revenue in FY27, with management aiming to increase its order book from around Rs 430 m to Rs 750-800 m by the end of H1 FY27. It is also expanding its 60,000 sq ft Global Capability Center in Ahmedabad, which will house IT and OT security operations, a vehicle SOC, product development and an AI experience centre. Management said construction of the main structure was completed in June and it was targeting completion of interiors by August, with operations expected to start around August-end or September.
There has also been fresh order activity. TechD received orders and an LOI worth Rs 30.9 m on 5 August, following orders worth Rs 29.1 m in July, adding to the revenue visibility already provided by its existing order book. The bigger near-term question is whether the company can convert its services growth and new orders into recurring product revenue, since management expects TechD One’s contribution to become meaningful over the next few quarters.
At Rs 550, the stock trades at 29.3 times earnings, below its five-year median PE of 36.4 times.
Conclusion
Vijay Kedia’s portfolio offers a useful reminder that the interesting part of investing is often not finding the next fashionable stock, but understanding what can change in a business. His holdings span companies at very different stages, from businesses recovering from weak periods to smaller companies trying to build new growth engines. That also means the risks are different, and a low valuation by itself does not make a stock attractive.
For investors looking at these stocks, the real question is whether the businesses can deliver on what the market is expecting. Sales growth, margins, order books, capital allocation and execution will matter far more than simply having a well-known investor on the shareholding list. Kedia’s presence can draw attention to a stock, but ultimately the businesses have to do the heavy lifting.
Happy investing.
Disclaimer: This article is for information purposes only. It is not a stock recommendation and should not be treated as such. Learn more about our recommendation services here…
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary