



India’s railway infrastructure story continues to gather steam, backed by sustained government spending on tracks, signalling, rolling stock, electrification and high-speed rail projects.
For railway companies, however, the headline order wins are only part of the story. A large and healthy order book provides revenue visibility, but the real differentiators are execution capability, order quality, margins and the pace at which these projects convert into cash flows.
As of June 2026, several listed railway and rail-infrastructure companies are sitting on sizeable order books, offering investors good earnings visibility and growth potential.
Here, we look at 5 railway stocks with strong order books as of June 2026 and examine what their backlogs could mean for future growth.
#1 Rail Vikas Nigam
First on the list is Rail Vikas Nigam Ltd (RVNL) is a major public sector infrastructure enterprise under the Ministry of Railways. It’s mandated with rail project development, financial resource mobilisation, and project implementation across India.
Its core business encompasses executing a complete range of railway infrastructure projects, including new lines, doubling, gauge conversion, railway electrification, metro systems, workshops, mega bridges, cable-stayed bridges, and complex hilly railway lines such as the Rishikesh-Karnaprayag rail link.
Beyond traditional rail civil engineering, RVNL has strategically expanded its operational scope across multi-sector infrastructure verticals, including highways and roads, metro rail, ports and harbours, telecommunications (such as the BharatNet project), power transmission, and solar energy.
It’s also establishing an international footprint across countries including Oman, UAE, Uzbekistan, Saudi Arabia, South Africa, and the Maldives.
Coming to its financial performance, the topline has been flat and its net profit has delivered a compounded annual growth rate (CAGR) CAGR of -13% over 3 years. The last 3-year return on equity (ROE) has been 14%.
As of June 2026, RVNL had an order book of Rs 934.92 bn, which is 4.6 times its FY26 consolidated revenue, offering multi-year visibility.
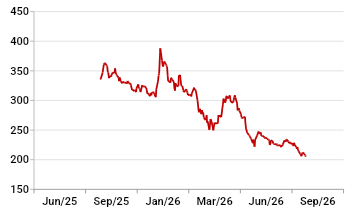
Rail Vikas Nigam Stock Price – 1 Year
Data Source: Ace Equity
Looking toward the future, management has guided a top-line revenue growth of around 15% and a bottom-line profit growth of approximately 15-20% for FY27.
The company is targeting annual order inflows of Rs 200-250 bn during the fiscal year, having already secured over Rs 50 bn in 1QFY27 supported by an active L1 and Letter of Award pipeline of Rs 92.62 bn.
Over the next three years, RVNL envisions maintaining an EBITDA margin of 5-7%, an ROE of 12-13%, and evolving its order book structure to a 50-50% balance between nomination-based railway management works and competitive bidding contracts.
#2 Ircon International
Second on the list is Ircon International, a major public sector engineering and construction enterprise under the Ministry of Railways specialising in large-scale transportation and infrastructure projects.
Its core business is providing turnkey Engineering, Procurement, and Construction (EPC), Project Management Consultancy (PMC), and Public-Private Partnership (PPP) services across specialised infrastructure domains.
These include railway track laying, gauge conversion, railway electrification, high-speed rail, complex tunnels, bridges, highways, metro systems, EHV substations, building construction, and renewable energy.
Operating on an asset-light model supported by strong in-house engineering and centralized procurement, IRCON executes high-impact domestic projects across challenging Indian terrains as well as international projects across 25 countries, including Algeria, Sri Lanka, Nepal, Myanmar, and Bangladesh.
Coming to its financial performance, the company has delivered a top-line growth of -4% CAGR over 3 years and a net profit CAGR of -12%.
The last 3-year ROE has been 12%.
As of June 2026, IRCON maintained a total order book of Rs 233.66 bn, representing 2.58 times its FY26 consolidated revenue, providing multi-year revenue visibility.
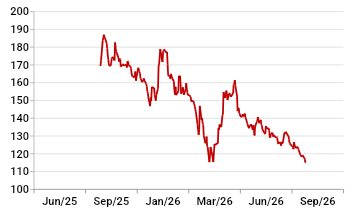
Ircon International Stock Price – 1 Year
Data Source: Ace Equity
Looking ahead, management expects standalone core EBITDA margins to remain in the range of 4% to 4.5% due to heightened industry competition and margin compression under open tendering rules.
To expand its order pipeline, the company has submitted bids for 107 projects valued at approximately Rs 480 bn across India, which are currently under evaluation.
IRCON’s capex and expansion roadmap anticipates total equity and quasi-equity commitments of Rs 7-8 bn in its Special Purpose Vehicles (SPVs), with planned investments of Rs 4 bn to Rs 5 bn earmarked for FY27 primarily across road/highway PPP projects (HAM/BOT) and coal-connectivity rail lines.
#3 Titagarh Rail Systems
On number three comes Titagarh Rail Systems, incorporated in 1997, is India’s leading private-sector integrated rail mobility solutions provider, manufacturing rolling stock across both freight and passenger rail segments.
Its core business is in two segments: Freight Rail Systems (FRS) encompassing the design and production of freight wagons, bogies, couplers, steel castings, specialised defence equipment, and bridge girders and Passenger Rail Systems (PRS) focused on metro coaches, Vande Bharat trainsets, passenger EMUs, propulsion equipment, traction motors, and Train Control and Management Systems (TCMS).
Additionally, Titagarh has transferred its Shipbuilding & Maritime Systems division into a wholly-owned subsidiary, Titagarh Naval Systems (TNSL), while expanding strategic backward integration through major joint ventures, notably Ramkrishna Titagarh Rail Wheels Limited (RTRWL) for domestic forged wheel manufacturing and a joint venture with BHEL for Vande Bharat trainset maintenance.
Coming to its financial performance, the company has delivered a top-line growth of 5% CAGR over 3 years and a net profit CAGR of 7%.
The last 3-year ROE has been 11%.
As of June 2026, Titagarh Rail Systems reported a standalone order book (including its wholly owned subsidiary TNSL) of Rs 133.35 bn.
Including its prorated share from joint ventures such as the forged wheel manufacturing JV (Rs 63 bn) and the Vande Bharat AMC JV (Rs 70 bn) its order book was Rs 266.35 bn.
The total order book, including joint ventures, is about 8.47 times its FY26 revenue.
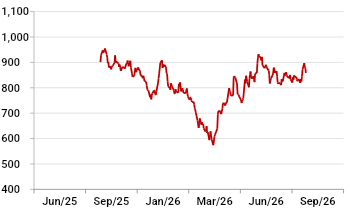
Titagarh Rail Systems Stock Price – 1 Year
Data Source: Ace Equity
Looking ahead, management expects Passenger Rail Systems revenue to expand quarter-on-quarter and structurally become the dominant business segment, complemented by a long-term rebound in freight wagon procurement as Indian Railways targets doubling rail freight traffic to 3 bn tons.
Further capital expenditure is directed toward expanding foundry capacity to achieve 100% self-sufficiency in captive wagon castings, building Asia’s second-largest forged wheel plant in Chennai via its JV with RKFL, and establishing a brownfield shipyard at Falta via TNSL.
#4 BEML
BEML is a multi-disciplinary engineering infrastructure enterprise operating across three business verticals: Rail & Metro, Defence & Aerospace, and Mining & Construction.
Its core business encompasses designing, manufacturing, and supplying heavy capital equipment and rail mobility solutions.
These include metro cars, Vande Bharat sleeper trainsets, high-speed rail trainsets, and LHB coaches, heavy earth moving machinery (HEMM), defence platforms, and aerospace structures.
Serving domestic infrastructure and defence sectors while exporting products to over 73 countries, BEML’s revenue mix in FY26 was led by Mining & Construction (41%), Defence & Aerospace (35%), and Rail & Metro (24%).
Coming to its financial performance, the company has delivered a top-line growth of 4% CAGR over 3 years and a net profit CAGR of -3%.
The last 3-year ROE has been 9%.
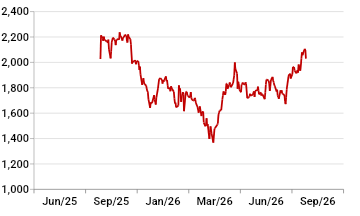
As of June 2026, BEML maintained an order book of a little over Rs 160 bn. Compared with the company’s FY26 total revenue, the June 2026 order book represents 3.78 times its FY26 revenue.
BEML Stock Price – 1 Year
Data Source: Ace Equity
Looking ahead, management has guided for top-line revenue growth in the high-20s percentage range for FY27. It expects EBITDA margins to recover to at least 13% in FY27 and is targeting 17-18% over the medium term.
BEML is targeting full-year FY27 order inflows of around Rs 200 bn supported by an active opportunity pipeline of Rs 350-400 bn across six live metro tenders, high-speed rail corridors, defence mandates (Rs 40–50 bn), and international metro/HEMM export opportunities (Rs 150 bn).
The company’s capex and expansion roadmap involves stepping up annual capital expenditure to over Rs 6 bn.
Expansion initiatives include operationalising the new ‘Aditya’ High-Speed Rail complex (Rs 2.5 bn capex) and leasing 36 acres in Bengaluru for LHB coach production; leasing 300 acres in Mysuru for aerospace manufacturing; setting up a greenfield metro manufacturing unit in Bhopal (‘Brahma’ project) with a planned capex of Rs 9 bn over 24 months; and establishing an 80-acre greenfield hub near Bilaspur (Chhattisgarh) to produce and service heavy earth moving machinery close to Coal India’s mining belt.
#5 Texmaco Rail & Engineering
Fifth on the list is Texmaco Rail & Engineering (Texmaco), an Adventz Group company incorporated in 1998.
It’s an engineering and infrastructure enterprise specialising in railway rolling stock, steel castings, and turnkey rail infrastructure solutions.
Its business operates across three major divisions:
- Freight Car Division (FCD) manufacturing freight wagons, bogies, couplers, draft gears, locomotive shells, and commodity wagons
- Infra – Rail & Green Energy executing turnkey rail EPC projects, track laying, signalling, telecommunications, hydro-mechanical equipment, and bridge girders
- Infra – Electrical (Bright Power) handling overhead railway and metro electrification, SCADA systems, high-voltage transmission lines, and power distribution asset maintenance.
Texmaco’s reach is strengthened through strategic joint ventures and subsidiaries.
On its financial performance, the company delivered 25% top-line CAGR over 3 years and 94% net profit CAGR.
The last 3-year ROE has been 8%.
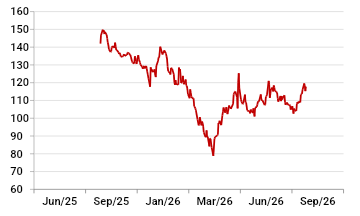
As of June 2026, Texmaco Rail & Engineering reported an order book of Rs 99.23 bn against the company’s FY26 consolidated revenue of Rs 43.77 bn. The June 2026 order book stands at 2.27 times its FY26 revenue.
Texmaco Rail & Engineering Stock Price – 1 Year
Data Source: Ace Equity
Looking ahead, under its ‘Texmaco 2.0’ and Vision 2030 roadmap, management aims to double its core top-line to Rs 50 –60 bn while steering profit margins toward the mid-teens and expanding core EBITDA margins by 1.2-3% over the next 1-3 years.
For FY27, management guided for higher execution and better profitability over FY26, supported by orders from private domestic clients and international export mandates.
The company’s capex and expansion roadmap focuses on modernizing its 7 manufacturing facilities, upgrading foundry capacity at Belgharia and Raipur with NABL lab accreditation, securing AAR M-1003 certification for Raipur to enter the US market, scaling the Touax Texmaco-TrinityRail leasing fleet, establishing a greenfield wagon manufacturing plant at Sodepur via Texmaco Nymwag, expanding into high-margin technology segments, and establishing a digital engineering Global Capability Centre (GCC) in partnership with Hörmann Vehicle Engineering.
Conclusion
The five stocks covered here offer different investment propositions, with variations in business mix, execution capabilities, growth prospects and profitability.
While a strong order book provides comfort on future revenues, investors should not confuse order-book size with guaranteed earnings growth.
The pace of execution, margin trajectory, working-capital requirements, and the ability to secure fresh orders will ultimately determine shareholder returns.
For investors tracking the railway theme, these companies are worth watching. However, valuations and execution will be as important as the order book when assessing their long-term investment potential.
Conduct thorough research on financials and corporate governance before making any investment decisions and ensure they align with your financial goals and risk tolerance.
Happy investing.
Disclaimer: This article is for information purposes only. It is not a stock recommendation and should not be treated as such. Learn more about our recommendation services here…
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary