



On Friday, 14 August 2026, the Department of Atomic Energy published a set of draft rules around nuclear energy.
The rules set out how a private company can go about building a nuclear power plant in India.
Under the draft, a company can obtain in-principle approval to prepare a site, acquire land, and select vendors before a formal licence is granted, which removes the chicken-and-egg problem that has stalled private interest in the sector for years.
For six decades, none of this was possible. The Atomic Energy Act of 1962 reserved nuclear power generation for state-owned entities, and the Civil Liability for Nuclear Damage Act of 2010 made equipment suppliers so nervous about liability that foreign vendors largely stayed away.
Both laws were repealed in December 2025 and replaced by a single statute, the SHANTI Act. Last week’s draft rules are the machinery that makes it operable.
Keeping that in mind, let’s look at the top 5 nuclear power companies in India that are sitting closest to this opportunity.
Please note, since India has only a handful of listed companies with genuine nuclear involvement, and none of them is a nuclear pure-play, we have ranked the companies basis their market capitalisation.
Further, we have selected them basis their involvement in the nuclear value chain.
#1 Larsen & Toubro
First on the list is L&T.
L&T is the most complete industrial exposure to Indian nuclear power, and it has been for forty years.
It manufactures reactor pressure vessels, steam generators, end shields, calandria, and pressurisers, which between them account for most of the heavy engineering inside a reactor.
More significantly, it runs a joint venture heavy forge unit with NPCIL at Hazira in Gujarat, which will forge the pressure vessels for the Indian Pressurised Water Reactor programme designed by BARC.
Few facilities anywhere can forge components at that size and tolerance, and India has exactly one.
If the nuclear fleet expands, someone has to make the vessels, and there is no domestic alternative other than L&T.
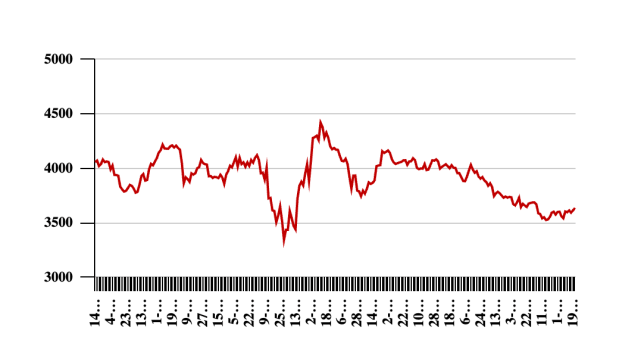
At present, L&T carries a diversified order book of about Rs 6.13 tn, and infrastructure projects alone were 47% of its FY26 revenue.
Nuclear equipment sits inside a heavy engineering business that is itself a modest share of the group.
But a doubling of India’s nuclear orders would be a good year for one division of L&T.
Larsen & Toubro – 1 Year Share Price
Data Source: BSE
#2 NTPC
Second is NTPC.
NTPC is the only company on this list that will own and operate reactors instead of supplying.
It’s targeting 30 GW of nuclear capacity by 2047, roughly a third of the national goal, pursued through two vehicles: ASHVINI, a joint venture in which NPCIL holds 51% and NTPC 49%, and a wholly owned subsidiary, NTPC Parmanu Urja Nigam.
The flagship is Mahi Banswara in Rajasthan, four 700 MW reactors totalling 2,800 MW at an estimated cost near Rs 500 bn.
The Prime Minister laid the foundation stone in September 2025, and the tender for the nuclear island EPC package was issued on 15 July 2026.
NTPC’s management says close to 34 sites are being explored across Andhra Pradesh, Madhya Pradesh, Gujarat, Maharashtra, Odisha, Bihar and Chhattisgarh, with Tamil Nadu and Karnataka under discussion.
That said, its first unit at Mahi Banswara is expected around six and a half years from groundbreaking, which puts first power near 2032.
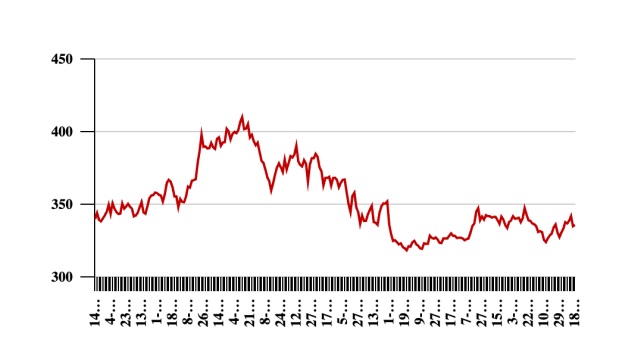
And NTPC has a long record of missing its own capacity targets, having delivered on average about 59% of them over the past decade. Nuclear is the hardest thing it has attempted.
Against a total planned capex of roughly Rs 16.7 tn over eleven years spanning coal, renewables, storage and nuclear, the nuclear slice is not dominant. Even then, NTPC remains a thermal and renewables company with a nuclear option.
NTPC – 1 Year Share Price
Data Source: BSE
#3 BHEL
Third on the list is BHEL.
It has supplied turbine generator sets to 14 of India’s 24 operating reactors, which works out to roughly half the country’s installed nuclear turbine capacity.
On incumbency alone, BHEL has the strongest claim of anyone in this list. The company’s financial picture looks decent. BHEL earned Rs 24.3 bn on revenue of Rs 360 bn.
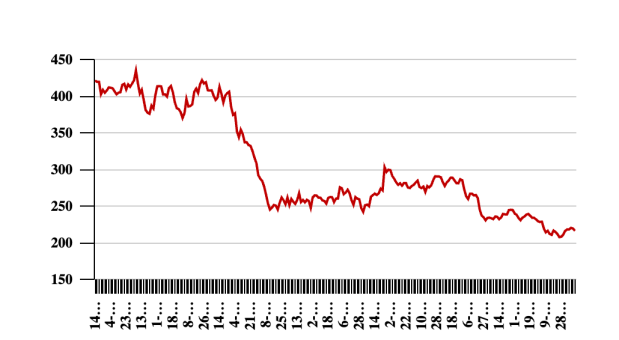
Its return on equity has averaged 3.18% over three years while its shares are up 90.5% in a year.
A company earning a low single-digit return on equity, re-rated to sixty times earnings on the expectation of orders that have not yet been placed, is being valued on a story.
The story may well come good, since a nuclear build-out at a serious scale needs turbines and BHEL is the obvious supplier. But the price already assumes a great deal of it so investors must note that.
Also, investors should watch its order inflow, specifically nuclear order inflow disclosed separately.
BHEL – 1 Year Share Price
Data Source: BSE
#4 Tata Power
Fourth is a Tata group company.
Tata Power is on this list for what it has applied to do rather than for anything it currently does in nuclear. It was one of six companies that responded to the request for proposals under the Bharat Small Reactor programme, alongside Hindalco, Jindal Steel & Power, Reliance Industries, JSW Energy, and Adani Power.
Between them the six identified sixteen prospective sites across Gujarat, Madhya Pradesh, Odisha, Andhra Pradesh, Jharkhand, and Chhattisgarh.
Under the small reactor model, a private company funds and hosts the plant, typically to power its own industrial operations, while NPCIL retains operating responsibility. This is precisely the activity that last week’s draft rules are designed to enable.
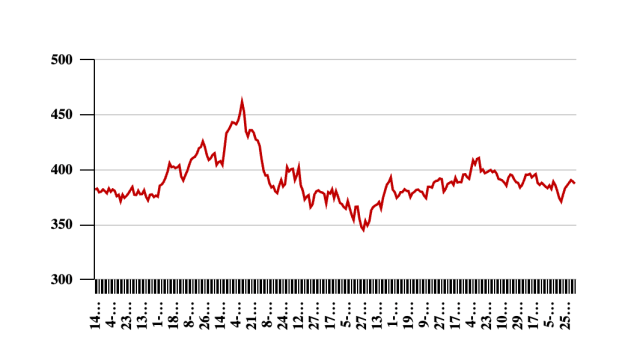
The stock is down 0.8% over a year, and it trades on about 23 times earnings against Rs 52.6 bn of profit on Rs 634 bn of revenue. Its return on equity has averaged 11% over three years.
Tata Power – 1 Year Share Price
Data Source: BSE
#5 MTAR Technologies
Last on the list is MTAR Technologies.
MTAR is the smallest company here and the only one where nuclear is material to the business.
It has been supplying coolant channel assemblies to the Department of Atomic Energy since 1969, and makes grid plates, drive mechanisms and other close-tolerance components that very few Indian firms can produce.
Its customers read like a list of the country’s strategic programmes: NPCIL, ISRO, DRDO, and HAL, alongside Bloom Energy, Rafael, and Elbit overseas.
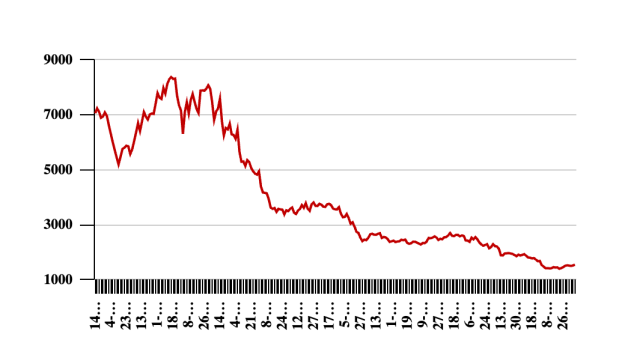
MTAR earned Rs 1.35 bn on revenue of Rs 10.8 bn. Its shares are up 365% in a year, trading around Rs 7,140 against a 52-week low of Rs 1,390.
That leaves the stock at roughly 161 times earnings and 26 times book value, with no dividend.
For context, its return on equity was around 7.4%, below any sensible estimate of its cost of capital, which means the business was consuming economic value.
But there is a genuine operating story underneath. The clean energy business is expanding hot box capacity from 8,000 units a year toward 30,000 by FY28, backed by supply commitments including a US$ 43.9 m order from Bloom Energy.
That is the near-term earnings driver, and it has nothing to do with nuclear.
MTAR Technologies – 1 Year Share Price
Data Source: BSE
Conclusion
After six decades in which private nuclear participation was not merely difficult but illegal, there is now a statute, a target, a funding line and a draft procedure for applying.
What has not changed is the physics of the industry.
The first unit at Mahi Banswara is around 2032. The small reactor programme aims for 2033. An investor buying today on nuclear grounds is underwriting outcomes most of a decade away, and the market has already re-rated two of these five names hard on that expectation.
The right thing to track over the next twelve months is whether the draft rules are notified largely intact, whether the Supreme Court leaves the liability structure standing, whether any of the six small-reactor applicants converts an expression of interest into a signed project, and whether BHEL and L&T begin disclosing nuclear order inflows separately.
When those things start happening, the theme becomes investable on evidence. Until then, the companies are worth knowing and the prices are worth waiting on.
As always, evaluate each company’s business quality, financial performance, management execution, corporate governance, and valuation as key factors before drawing any investment conclusions.
Happy investing.
Disclaimer: This article is for information purposes only. It is not a stock recommendation and should not be treated as such. Learn more about our recommendation services here…
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary