



Somewhere in the unglamorous segment of the Indian stock market, below the Nifty 50 biggies and below the mid-caps that fund managers fawn over, there sits a segment that nobody important visits.
No brokerage analyst is paid to cover this segment. Nor any business channel runs prime-time debates on it. We’re talking about the microcap space in India.
This is where, paradoxically, some of the biggest wealth creation opportunities of the next decade can be found.
But the problem is that this segment plays tricks on you. If you buy the wrong microcap stock, the wealth destruction could leave you crippled.
But if researched well, this segment can be very rewarding.
We looked at the entire microcap space to find out some potentially good businesses.
We applied these filters:
- Market cap under Rs 50 billion (bn)
- Yearly sales growth above 20%
- Yearly net profit growth above 25%
- ROCE above 20%
- ROE above 18%
- Debt to equity below 1
- Free cash flow per share above zero
Only a select few names stood out after we applied this filter. From that list, let’s look at the 5 fastest growing microcap stocks in India.
#1 Canara Robeco Asset Management Company
First on the list is Canara Robeco Asset Management Company.
The company manages mutual fund schemes across equity and debt categories, serving both retail and institutional investors. It’s backed by Canara Bank and ORIX Corporation, which provides strong institutional credibility.
Over time, it has built a wide distribution network across India while strengthening its digital platforms. This has helped improve investor reach and participation.
A key strength of the company lies in its high share of equity-oriented AUM, which accounts for around 90% of its total AUM. This supports higher fee income, although it also makes earnings sensitive to market movements.
Recently, Canara Robeco has experienced steady AUM growth, because of rising retail participation and SIP inflows. As AUM expands, operating leverage plays a key role in improving profitability.
This is visible in its financials. It has grown its sales nearly at 27% yearly over the past three years while the profit during the same period has grown 26%. It has done this with a debt-to-equity of zero, meaning a completely unleveraged balance sheet.
With ROCE of 49% and ROE of 36%, this is a business compounding capital quite well.
Going forward, the company is looking to expand into B-30 cities, add new offerings such as AIFs and PMS, which is likely to support further growth in its AUM.
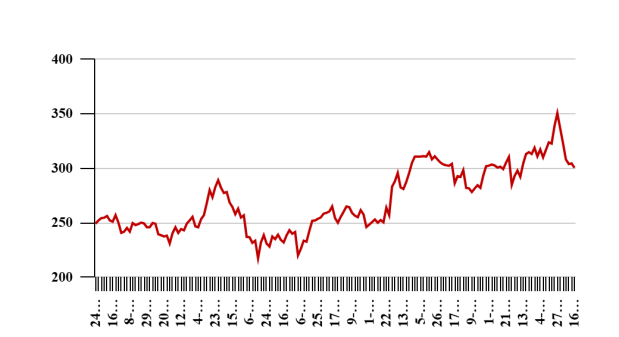
Canara Robeco – 1 Year Share Price
Data Source: NSE
#2 Crizac
Second on the list is Crizac.
Crizac is a leading B2B education platform. It specialises in international student recruitment.
The company connects universities with a global network of over 10,000 registered student recruitment agents across more than 75 countries.
Crizac operates a proprietary cloud-based technology platform that streamlines the entire recruitment process – lead generation, application processing, eligibility screening, real-time tracking, and admissions management.
Its revenue have grown at a CAGR of 60% in the last three years while net profit has climbed nearly 30% during the same time, yet the company carries no debt whatsoever.
A 48% ROCE paired with a 36% ROE shows the education-platform business is converting that top-line expansion into genuine returns.
In its latest earnings call, the management framed FY26 as their most active year in the inorganic front, with acquisitions and investments used to compress timelines for geographical entry and capabilities built out.
Currently, Crizac leans heavily on the UK and plans to bring that below 60% of its business within about two years.
The new UK rules (the Agent Quality Framework) have raised the bar for those who can operate as a student-recruitment agent. Crizac’s management sees this as a good thing as weaker, smaller players get squeezed out and market consolidates.
On cash generation, the company has sufficient cash on its books, but in FY26 the amount converting looked weaker than usual due to a single one-off of Rs 550 million (m) termination fee. It remains to be seen how the company navigates a challenging macro environment.
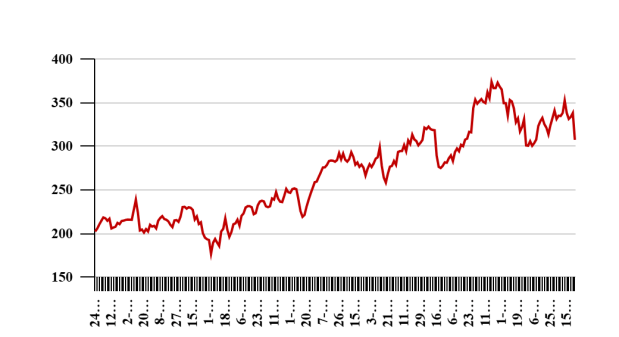
Crizac – 1 Year Share Price
Data Source: NSE
#3 Network People Services
Third on the list is Network People Services.
The company provides software and digital payment solutions to the banks and fintech firms, focusing on transaction processing, payment platforms, RegTech, and digital engagement.
Its software help modernising payments infrastructure for banks, payment aggregators, and merchants, and ensures smooth flow of payments.
The company has more than 700 merchant locations, operates across India, has tie-ups with more than 15 banks and 2 m bank merchants.
Network People’s UPI platform further supports banks by extending secure transaction processing infrastructure for customer and merchant payment.
It has recently also introduced a CBDC Switch for handling Central Bank Digital Currency transactions.
Coming to its financials, the company’s sales have grown at nearly 36% CAGR over the past 3 years while its net profit has grown at a much faster pace of 68%.
The company has ROCE of 74% and ROE of 58%, while its debt-to-equity is a negligible 0.03.
The digital-payments infrastructure player is the clearest case here of profit outrunning revenue, showing good use of operating-leverage.
For Network People Services, FY26 was a year of deliberate trade-offs. The company chose to scale revenue by dominating the TSP (technology service provider) space, accepting weaker cash conversion, and slightly softer margins as the price of that growth.
As per the management, FY27 is going to be all about execution. The company has signed deals and is close to signing more international and large-scale projects, which suggests the real impact will land in the second half of the year (Q3 and Q4).
The company’s management has explicitly said their RegTech AI would start generating revenue in FY27. They’ve already won a large PSU bank order, and they’re seeing demand signals across the banking sector. So, the company’s AI angle has actual orders behind it.
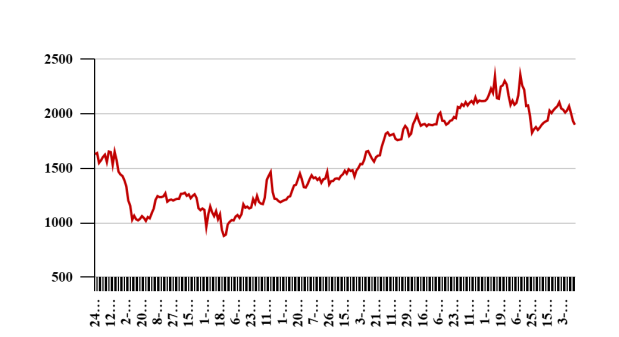
Network People – 1 Year Share Price
Data Source: NSE
#4 MPS
Fourth on the list is MPS.
MPS is one of the leading players globally in the publishing outsourcing space. It’s a B2B model with end clients being scholarly and research community, education community, Edtech, corporate learning space.
Its clients include Macmillan, Cengage Learning, McGraw-Hill, Elsevier, Wolters, and Kluwer.
The company has multiple segments – content solutions that deals with content creation and delivery across different channels, platform business that offers a complete range of configurable platform solutions throughout the entire content lifecycle, delivered as SaaS and e learning segment.
Of the five companies we are going to list here, MPS is the cash machine of the lot.
Its free cash flow per share of Rs 61 is comfortably the highest among the five, backed by 33% sales growth and a 25%-plus net profit rise over the past three years. All this has been achieved on a zero-debt balance sheet.
With ROCE of 43% and ROE of 32%, this publishing-and-platform business proves that boring and highly profitable are not mutually exclusive.
Going forward, its management has shared a vision of revenue base of Rs 15 bn by FY28, almost 5x of current topline, with significant contribution (60%) from acquisitions.
The operating profit margins are north of 40% while its balance sheet remains debt free.
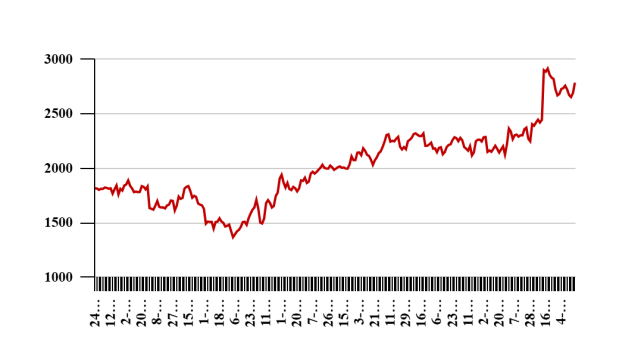
MPS – 1 Year Share Price
Data Source: NSE
#5 Advait Energy Transitions
Last on the list is Advait Energy Transitions.
Advait Energy Transitions is a key player in power infrastructure, with execution experience spanning 450+ projects across 45+ countries. The company focuses on core power delivery solutions such as stringing tools, OPGW cables, and Emergency Restoration Systems (ERS).
Last year, the company expanded its focus toward emerging clean-tech segments such as green hydrogen, fuel cells, BESS, carbon markets, and renewable energy-linked opportunities as part of its long-term energy transition strategy.
In recent years, the company’s growth has accelerated sharply. In fact, Advait has posted the fastest profit growth on this entire list. Its net profit has nearly doubled, growing at 91% CAGR over the past three years, alongside 47% sales growth during the same period.
It has the highest leverage though, at a debt to equity of 0.34, still well within the sub-1 threshold and reasonable for a company riding the energy-transition and power-infrastructure theme.
The company’s ROCE of 28% and ROE of 24% reflects the structural trend it’s riding.
The order book stands at a little over Rs 10 bn with 84% of it coming from the power transmission solutions business, while the remaining 16% comes from the new and renewable energy segment.
Going forward, the company plans to manufacture electrolyzers, battery energy storage systems (BESS), fuel cells and transmission equipment under one roof. The first 30 MW electrolyser assembly line is operational, while the 300 MW expansion is expected to scale over the next two years.
The core transmission EPC business is also scaling rapidly. During the quarter, Advait secured its largest-ever EPC order from PGVCL for reconductoring work under the distribution upgrade scheme.
The management is guiding for 40-45% revenue growth, backed by both the existing order book and a large tender pipeline.
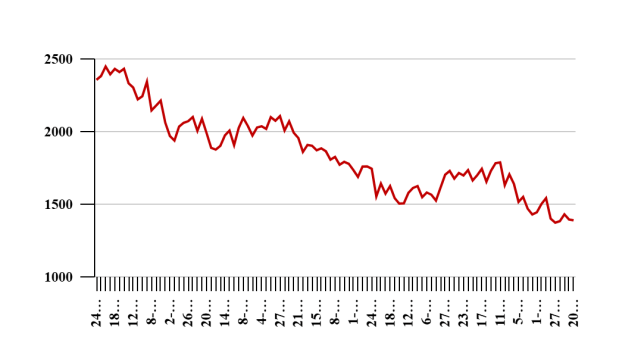
Advait – 1 Year Share Price
Data Source: NSE
Conclusion
If there’s a single thread running through these five companies, it’s discipline: growth that hasn’t come at the cost of the balance sheet, returns that haven’t been propped up by leverage, and profits that actually convert into cash.
That combination is very rare in the microcap space.
That said, these metrics only capture where each business stands today. They say nothing about management quality, competitive moats, promoter intent, or the cyclical tailwinds/headwinds.
A microcap clearing every filter this quarter can stumble the next, and that’s the nature of companies this small. Whether these smaller companies earn a place in your portfolio is a question only deeper, company-specific research can answer.
Approach this space with conviction but also humility. The same volatility that makes microcaps capable of multiplying your capital can erode it just as quickly.
Investors should evaluate the company’s fundamentals, corporate governance, and valuations of the stock as key factors when conducting due diligence before making investment decisions.
Happy investing.
Disclaimer: This article is for information purposes only. It is not a stock recommendation and should not be treated as such. Learn more about our recommendation services here…
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.