



Something unusual happened in the June 2026 quarter. Every listed wires and cables company of consequence in India reported strong numbers in the quarter so far. Not most of them, all of them.
When an entire sector posts the same result in a quarter, the cause is usually external. In this case the cause is copper.
The London Metal Exchange (LME) 3-month copper price traded around US$ 14,100 per tonne in early August 2026, against less than US$ 11,000 at the end of November 2025.
Cable is largely copper by cost, and the industry sells on a cost-plus basis, so the metal price flows almost directly into the invoice.
So, a good deal of what looks like growth in the recent quarter is the same quantity of cable sold at a higher rupee value. That does not make the quarter fake. The interesting thing to look at is which company converted a metal-driven revenue boom into something durable.
Here, we look at 5 wire and cable companies that posted excellent Q1 results.
This list excludes Apar Industries as its conductor and specialty oil division drove the numbers. Havells and Paramount are also excluded.
#1 Polycab India
First is Polycab India.
Polycab is the largest company in the Indian electrical industry by revenue and it delivered its highest-ever first quarter.
Its revenue reached Rs 82.1 bn, up 39%, and profit was at a record Rs 7.97 bn, up 33%. The wires and cables segment alone did Rs 72 bn, with domestic sales up 43%.
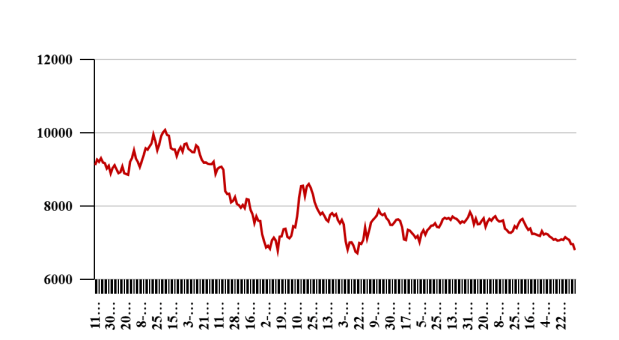
Despite this, the market sold the stock down about 4% on the result day.
The reason is buried in the earnings call, and it’s the most useful disclosure of the entire results season. Asked about volumes, its management said growth in the domestic cable and wire business was in the low to mid-single digits.
Revenue grew 39% and volume around 5%. Everything in between is copper and aluminium, and Polycab said as much, describing itself as operating on a cost-plus model and declining to guide on metal prices.
Its EBITDA margin tells the same story. At 13.8% it improved roughly 70 basis points over the March quarter but fell 70 basis points against the 14.5% of a year earlier.
What is genuinely working for Polycab is the FMEG business, up 71% and outperforming its industry for a tenth consecutive quarter, and the balance sheet, with net cash of Rs 39.9 bn and a working capital cycle of 15 days.
Its international business fell 13% on Middle East disruption.
Polycab India – 1 Year Share Price
Data Source: BSE
#2 KEI Industries
Second on the list is KEI Industries.
The company grew its revenue at the slowest pace among these five, at 23% to Rs 31.9 bn. That said, its margins grew the most.
EBITDA margin expanded 247 basis points year on year to 12.4%, which is why a 23% revenue increase produced a 40% profit increase, to Rs 2.74 bn.
Its business mix explains it. Domestic wires and cables rose 29% to Rs 27.8 bn while exports fell 7% to Rs 3.08 bn on Middle East shipping disruption, and extra-high-voltage cables, the most technically demanding product KEI makes, grew 48% to Rs 1.86 bn.
KEI also has pending orders of about Rs 42.9 bn as of 30 June and net cash of Rs 8.5 bn, and plans to take the Sanand plant to Rs 70 bn of annual capacity from an earlier Rs 60 bn target.
There are some points of concern though. Its EPC segment swung to a loss of Rs 51 m on revenue of Rs 1.31 bn, having made money a year earlier.
Also, the Income Tax Department conducted search and seizure operations at KEI’s registered office, plants, and the residences of a promoter and certain executives between 7 and 12 May 2026.
The company said it cooperated fully and had received no written communication on the outcome as of the results date, and the statutory auditors flagged it as an emphasis-of-matter note without modifying their conclusion.
The financial impact is not quantifiable today, which is precisely why it stays on the watch list until it is resolved.
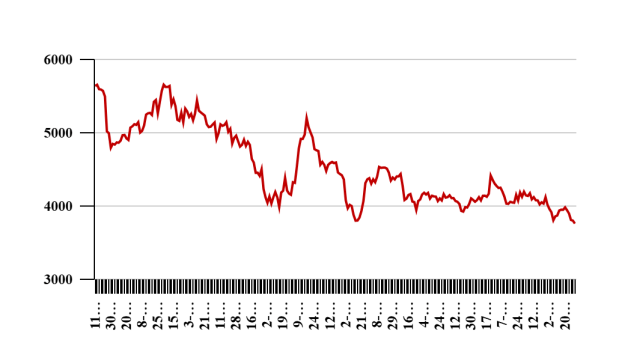
KEI Industries – 1 Year Share Price
Data Source: BSE
#3 RR Kabel
Next is RR Kabel.
This company posted the sharpest numbers of the quarter: revenue up 54% to Rs 31.7 bn, EBITDA up 99% to Rs 2.85 bn, and profit up 129% to Rs 2.05 bn.
Wires and cables, about 90% of the business, grew 57%. But the number that matters most is EBITDA margin, which went from 7% to 9%.
That sounds modest until you consider where RR Kabel started. This has always been the low-margin operator among the branded players, running at roughly half Polycab’s profitability.
Closing that gap is worth more to the company than any amount of copper-driven revenue, and management is targeting 9.5% for FY27 and 10.5% for FY28.
Its FMEG business reaching operational breakeven is the other genuine milestone, as it has been a drag for years.
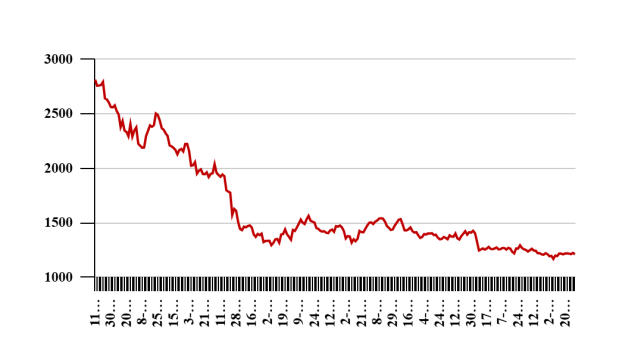
That said, the stock is up 122% over a year and trades at roughly 12 times book value, the most expensive multiple of the five on this list.
Its management has guided to 16-18% volume growth in cables and wires for FY27 and is spending Rs 12 bn of capex between FY26 and FY28, about Rs 6.5 bn of it this year.
RR Kabel – 1 year Share Price
Data Source: BSE
#4 Finolex Cables
Fourth is Finolex Cables.
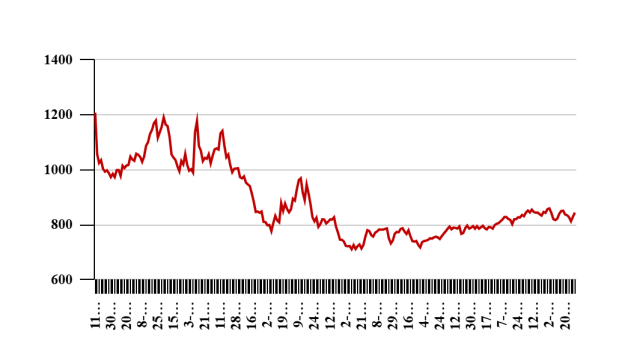
Finolex reported its results on 11 August, later than the rest, and the stock rose about 30% across two sessions to a 52-week high.
Its revenue grew 44% to Rs 20.1 bn and consolidated profit 53% to Rs 2.49 bn, while EBITDA rose 79% to Rs 2.44 bn and margin expanded 236 basis points to 12.1%.
Finolex is also the one company here that told us its volumes. Electrical wire volumes rose 7%. Electrical cable revenue rose 47%. The gap between those two figures is the whole sector’s story in a single company’s disclosure.
The more interesting development is communication cables, up 62% to Rs 1.76 bn, with optic fibre volumes described as significantly higher and realisations improving.
Finolex is expanding its fibre draw facility to 4 m fibre km, on track for the December 2026 quarter.
Optical fibre has been a bad business in India for 3 years on Chinese oversupply and weak telecom capex, so a genuine turnaround matters more to FY28 than another quarter of copper pass-through.
There are two things to keep in mind. The copper rod segment collapsed 98% to Rs 80 m, which the company attributes to limited LPG and PNG availability arising from the Middle East conflict, making it an input constraint.
Finolex has long carried a large treasury and an associate stake contributing materially below the operating line.
Finolex Cables – 1 Year Share Price
Data Source: BSE
#5 Universal Cables
Last is Universal Cables.
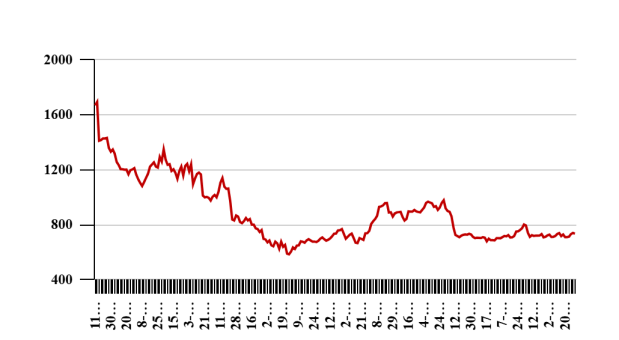
The smallest company here produced the most dramatic quarter. Its revenue rose 57% to Rs 9.45 bn, its highest-ever first quarter, and profit more than doubled to Rs 701 m. The stock rose nearly 16% on the day and is up around 127% over a year.
Universal Cables belongs to the M P Birla group and makes extra-high-voltage cables at Satna, a different business from selling house wire through dealers.
It had an order book of about Rs 28.6 bn as of 1 July 2026, including roughly Rs 4.85 bn of export orders, and has guided to 25% or better revenue growth in FY27 on that basis.
It has raised its capacity expansion outlay to about Rs 6.17 bn from Rs 5.5 bn, with a further Rs 740 m going into modernising the EHV facility.
Its joint venture Birla Furukawa Fibre Optics has separately proposed roughly tripling optical fibre capacity along with an upstream preform plant, at an indicated investment near US$ 500 m.
That figure is comparable to Universal Cables’ entire market capitalisation of about Rs 57.9 bn, and it is a proposal at a joint venture rather than committed spending.
The other number to note is return on equity, which has averaged under 7% over three years.
Its finance costs of Rs 365 m in the quarter against profit before tax of Rs 848 m tell you this is a leveraged, working-capital-hungry business in a way the branded players are not.
Universal Cables – 1 Year Share Price
Data Source: BSE
Conclusion
A rising copper price handed every company in this sector a good headline, and then the companies separated themselves on what they did underneath it.
But copper will not rise forever. When it stops, revenue growth across this sector will compress sharply and the companies that used this window to fix mix, margin and product will look very different from those that simply invoiced a higher metal price.
Evaluate each company’s business quality, financial performance, management execution, corporate governance, and valuation as key factors before drawing any investment conclusions.
Happy investing.
Disclaimer: This article is for information purposes only. It is not a stock recommendation and should not be treated as such. Learn more about our recommendation services here…
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary