



Fertiliser is one of those industries where growth is rarely just about selling more tonnes. It is also about adding capacity, improving the product mix, securing raw-material availability, and moving towards higher-value nutrients. For Indian fertiliser companies, these levers are becoming increasingly important as domestic demand rises and the industry looks to reduce its dependence on imports.
The next phase of growth, therefore, could favour companies that are willing to invest ahead of demand. Capacity additions, new product launches, backward integration and expansion into speciality fertilisers can help companies improve both volumes and margins over time.
In this article, we look at four fertiliser stocks with strong growth plans.
#1 Deepak Fertilisers & Petrochemicals Corp
First on the list is Deepak Fertilisers & Petrochemicals Corp a manufacturing company that turns natural gas into a suite of industrial and agricultural products, including fertilisers, agri services, bulk chemicals, mining chemicals, and real estate.
The company operates three key business segments: Crop Nutrition, which has completed a strategic shift to offering crop-specific, branded nutrient packages under the ‘Mahadhan’ brand; Mining Chemicals, where it is India’s sole producer of explosives-grade low-density prilled ammonium nitrate; and Industrial Chemicals, as South Asia’s largest nitric acid producer and a key manufacturer of Isopropyl Alcohol (IPA).
Coming to its long-term financial performance, the company has delivered a top-line growth of 1% compounded annual growth rate (CAGR) over 3 years, a net profit CAGR of -16%, and the last 3-year return on equity (ROE) has been 11%.
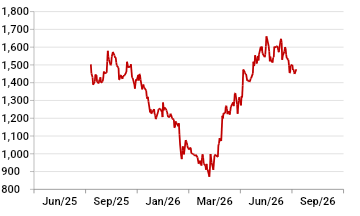
Deepak Fertilisers & Petrochemicals Corp Stock Price Performance – 1 Year
Data Source: Ace Equity
Looking ahead, the company is in the final stages of its capital expenditure cycle, which is expected to drive its next leg of growth as both of its major projects are scheduled to commence operations in 2QFY27. Specifically, the greenfield Technical Ammonium Nitrate (TAN) project at Gopalpur, Odisha, is approximately 96% complete, and the Dahej, Gujarat nitric acid expansion (adding 300 KTPA of Weak Nitric Acid and 150 KTPA of Concentrated Nitric Acid) is approximately 93% complete.
Both projects remain within their approved capex envelope, with total spending till 1QFY27 of around Rs 38.5 bn, and the company management expects the Gopalpur TAN project to reach approximately 80% utilisation by 4QFY27 and deliver a peak ROCE of 18-20%. Furthermore, the commencement of gas supplies in May 2026 under the company’s 15-year LNG agreement with Equinor ASA is projected to phase out more expensive gas contracts by 4QFY27, yielding estimated annual savings of around Rs 3 bn at current prices, structurally improving overall margins and supply security.
#2 Paradeep Phosphates
Coming second on the list is Paradeep Phosphates, India’s second-largest private sector phosphatic company and a major manufacturer of non-urea complex fertilisers. The company is into manufacturing, trading, distribution, and sales of finished crop nutrition products, including Di-Ammonium Phosphate (DAP), three grades of Nitrogen-Phosphorus-Potassium complex fertilisers (NPK-10, NPK-12, and NP-20), and specialty and industrial by-products such as Zypmite, Phospho-gypsum, and Hydrofluorosilicic Acid.
The company operates on a distinct backward-integration model, strategically acquiring granulation plants across sites like Paradeep, Goa, and Mangalore, and integrating them with in-house phosphoric and sulphuric acid facilities to secure key raw materials and capture higher margins. Backed by its joint promoter, Morocco’s OCP Group, which controls roughly 70% of the world’s phosphate rock reserves, Paradeep Phosphates enjoys stable long-term supply agreements for rock and acid, protecting it from volatile spot market prices.
In terms of long-term financial performance, the company has delivered 18% top-line growth CAGR over 3 years and a net profit CAGR of 48%. The last 3-year ROE has been 13%, and the most recent year’s ROE reached 19%.
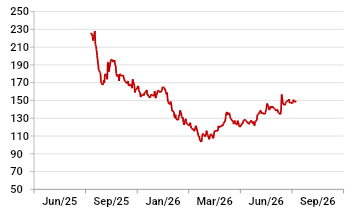
Paradeep Phosphates Stock Price Performance – 1 Year
Data Source: Ace Equity
Looking ahead, the company is undertaking significant capital expenditure and diversification plans designed to drive structural profitability and volume growth. It is currently executing Phase 1 of its captive phosphoric acid debottlenecking at Paradeep, expanding capacity from 500 KTPA to 600 KTPA by December 2026, and further to 700 KTPA by August-September 2027 at a capex of around Rs 2.5 bn.
In addition, the company’s board has approved a new Rs 2.5 bn investment to set up a 15,000 MTPA Aluminium Fluoride plant at Paradeep. This plant will convert Hydrofluorosilicic acid (a manufacturing by-product) into high-value specialty chemicals, commissioning in 22 to 24 months and projected to generate Rs 1800-2000 m in revenue and Rs 500 m in EBITDA.
For the long term, it is pursuing a massive Rs 36 bn expansion to add 1 million tons of granulation capacity at Paradeep alongside 500,000 tons of phosphoric acid and 1.5 million tons of sulphuric acid plants, scheduled for commissioning around mid-FY29-30. Collectively, these expansions are guided to elevate sustainable EBITDA from the current base of Rs 5,000 per MT to Rs 7,000+ per MT in the next two to two and a half years.
#3 Madhya Bharat Agro Products
On number three comes Madhya Bharat Agro Products, part of the Ostwal Group of Industries, a leading Indian manufacturer of fertilizer and chemical products.
It is the country’s third-largest private-sector phosphatic fertiliser company. The company’s business model is centred on crop nutrition, producing Single Super Phosphate (SSP) under the ‘Annadata’ brand and Nitrogen-Phosphorus-Potassium (NPK) and Di-Ammonium Phosphate (DAP) complexes under the ‘Bharat’ brand.
The company’s competitive advantage lies in its captive chemical-intermediates backbone, which produces its own sulphuric acid, phosphoric acid, and beneficiated rock phosphate, insulating the company from global raw material price fluctuations.
It is notably the only manufacturer in India capable of beneficiating low-grade rock phosphate into high-grade. The company’s raw material security is further reinforced by a 10-year agreement with the Jordan Phosphate Mines Company for 500,000 tonnes of rock phosphate annually, and a strategic 10-year Green Ammonia Purchase Agreement with the Solar Energy Corporation of India (SECI) commencing in April 2029 to supply 130,000 tonnes per annum.
In terms of long-term financial performance, the company has delivered 24% top-line growth CAGR over 3 years and a net profit CAGR of 6%. The last 3-year ROE has been 19%.
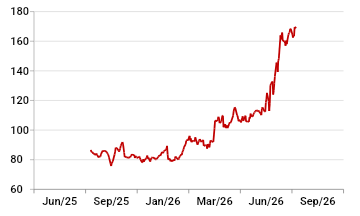
Madhya Bharat Agro Products Stock Price Performance – 1 Year
Data Source: Ace Equity
Looking ahead, the company is doing a massive expansion to reach a total fertiliser capacity of approximately 1.6 MTPA by FY28. This capacity expansion is projected to drive revenues to between Rs 35 bn and Rs 40 bn by FY28, more than doubling its current base.
A key driver of this growth is the state-of-the-art integrated Dhule Fertiliser Complex in Maharashtra, where the SSP and sulfuric acid plants have already been commissioned and stabilised. Phase 1 of the Dhule project, scheduled for commercial production in October 2026, will add 330,000 MTPA of DAP-NPK capacity and 99,000 MTPA of phosphoric acid capacity, which management guides will add over Rs 20 bn in revenue, with an initial capacity utilisation of 50-60% in FY27 and 75-80% in FY28.
In-principle approval was also granted for Phase 2 at Dhule, requiring a Rs 4.5 bn investment to add another 330,000 TPY DAP/NPK capacity, 66,000 TPY phosphoric acid, and 396,000 TPY sulfuric acid plants by October 2027.
Management expects a quantum jump in revenues and a more than 50% increase in overall turnover in the coming months of FY27, once the first phase of Dhule is commissioned.
#4 Krishana Phoschem
Fourth on the list is Krishana Phoschem, another member of the Ostwal Group, Its core business revolves around three synergistic segments: a fertilizer manufacturing engine that turns out Nitrogen-Phosphorus-Potassium (NPK) complexes, Di-Ammonium Phosphate (DAP), and Single Super Phosphate (SSP) under its proprietary ‘Bharat’ and ‘Annadata’ brands; a robust backward-integration core that upgrades low-grade domestic rock phosphate through India’s first private-sector beneficiation plant and produces captive sulphuric and phosphoric acids; and a chemicals division that markets surplus acid to external buyers.
The company’s raw material security is ensured by a 10-year, 5-million-tonne rock phosphate supply agreement with Jordan’s state-owned mining company.
In terms of financial performance, the company has delivered a 96% top-line CAGR over 3 years and an 89% net profit CAGR. The last 3-year ROE has been 28%.
Krishana Phoschem Stock Price Performance – 1 Year
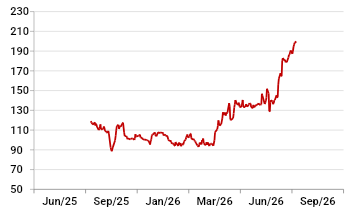
Data Source: Ace Equity
Looking ahead, commercial production at its newly expanded 165,000 MTPA NPK/DAP and 99,000 MTPA sulphuric acid units, which commenced on March 31, 2026, increases Krishana Phoschem’s total NPK/DAP capacity to 495,000 MTPA and is expected to drive an additional 30% to 40% turnover growth over the previous fiscal year as utilisation climbs from its initial 1QFY27 level of 43%.
Margin stability and cost advantages will be structurally enhanced by a landmark 10-year purchase agreement with SECI signed in March 2026, securing 70,000 MTPA of green ammonia at a price that locks in a >30% procurement cost advantage over global grey ammonia benchmarks once supplies start in FY29. Additionally, it plans to expand its trading business with an FY27 import target of approximately 150,000 metric tons, translating to around Rs 10 bn in revenue at an EBITDA margin of 6% to 8%, which will complement its manufactured product portfolio and support management’s target of growing its national phosphatic fertiliser market share from 18% to 25% within the next 2 to 3 years.
Conclusion
The four companies featured here are taking different routes to the same destination: building capacity today to capture the next phase of growth in India’s fertiliser market.
But expansion is only part of the story. Large capex programmes need to translate into higher utilisation, better margins and stronger returns on capital. For investors, the key is therefore to track project execution, funding requirements, raw-material security and the pace at which newly added capacity starts contributing to earnings.
The opportunity is meaningful, but so is the execution risk. As these companies move from expansion plans to actual production, the next few years should reveal which businesses can turn capacity additions into durable shareholder value.
As always, do your homework on the financials, corporate governance and valuation before making any investment decision, ensuring they align with your financial goals and risk tolerance.
Happy investing.
Disclaimer: This article is for information purposes only. It is not a stock recommendation and should not be treated as such. Learn more about our recommendation services here…
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary