



India’s education story is moving beyond classrooms and campuses. As the country aims to expand access to higher education, online and flexible learning is becoming an important part of that transition. The National Education Policy 2020 targets an increase in higher-education Gross Enrolment Ratio to 50% by 2035, from 26.3% in 2018.
The EdTech Macro Environment
The government is also encouraging technology-led and flexible learning models. The opportunity is reflected in the size of the market. Technopak Report expects India’s online higher education and upskilling market to expand 3X from ₹13,200 crore in FY23 to ₹41,450 crore by FY28.
Importantly, the opportunity extends beyond universities taking their courses online. It spans the broader education ecosystem, including companies offering online learning, partnering with universities for degree programmes, and providing executive education and skill-development courses.
This creates a larger addressable market for education and e-learning companies. Against this backdrop, let’s look at three leading listed EdTech Players.
Join now
#1 PhysicsWallah: From Online Scale to Offline Profitability
PhysicsWallah is an educational technology company. The company has three business divisions.
The online segment includes online coaching, digital learning services, and book sales. The online segment revenue grew 33.2% year-on-year to ₹548.8 crore in Q1FY27, representing 52.1% of revenue.
It aims to increase the share of online business in its revenue mix to 55% over the next three years. This is the only profitable segment so far. Operating EBITDA (earnings before interest, taxes, depreciation, and amortisation) of the online business increased 200.2% to ₹75.9 crore in Q1FY27.
Why the Offline Segment Remains a Capital-Heavy Drag
On the other hand, the offline segment includes classroom-based coaching services (under their Vidyapeeth brand), B2B book sales, and hostel accommodations. Vidyapeeth Classroom Centres generate about 70% of offline revenue. Offline business is also slower on the growth front, with Q1FY27 growing just 14.5% to ₹489.9 crore.
As the offline segment is more capital-heavy, it remains loss-making. EBITDA losses have reduced by 47.5% to ₹27.2 crore in Q1FY27. As online revenue contribution increased, the offline mix declined to 46.5% from 50.5% in Q1FY26. This bodes well for the company’s profits.
Consolidated Losses Narrow as ARPU Climbs 11-12%
Other segments (1.4% of revenue) include student financing services, hardware device sales, and support services for K-12 schools. The other segment generated revenue of ₹15.3 crore and an EBITDA loss of ₹4.5 crore.
At the consolidated level, revenue grew 24.4% year-on-year to ₹1,054 crore in Q1FY27, driven by 11-12% growth in Average Revenue Per Student (ARPU). EBITDA loss after accounting for unallocated corporate costs narrowed to ₹12.7 crore, from a loss of ₹70.1 crore in Q1FY26. Consolidated net loss narrowed to ₹88.3 crore, from ₹127 crore in Q1FY26.
Management Eyes Full-Year FY27 Profit via Offline Breakeven
Looking ahead, management projects consolidated revenue growth of more than 30% for FY27. The company is guiding for a 100% improvement in EBITDA for FY27 compared to the ₹300 crore generated in FY26. PhysicsWallah is also aiming to achieve full-year consolidated net profit in FY27.
This will be driven by the breakeven and profitability of the offline segment. Long-term target margins for offline centres are set at 13% to 15%. The group aims to use its organic community model to reduce marketing and distribution costs by 20% over the next three years. For context, marketing expenses stood at ₹353 crore (approximately 9% of revenue) in FY26.
Arabata 2.0: Pivoting 35 Lakh Users into an AI Revenue Stream
PhysicsWallah aims to create an AI-based revenue stream using data from its 35 lakh daily active app users. Artificial intelligence projects include Arabata 2.0 and an interactive AI suite that solves academic questions and evaluates subjective descriptive answer sheets.
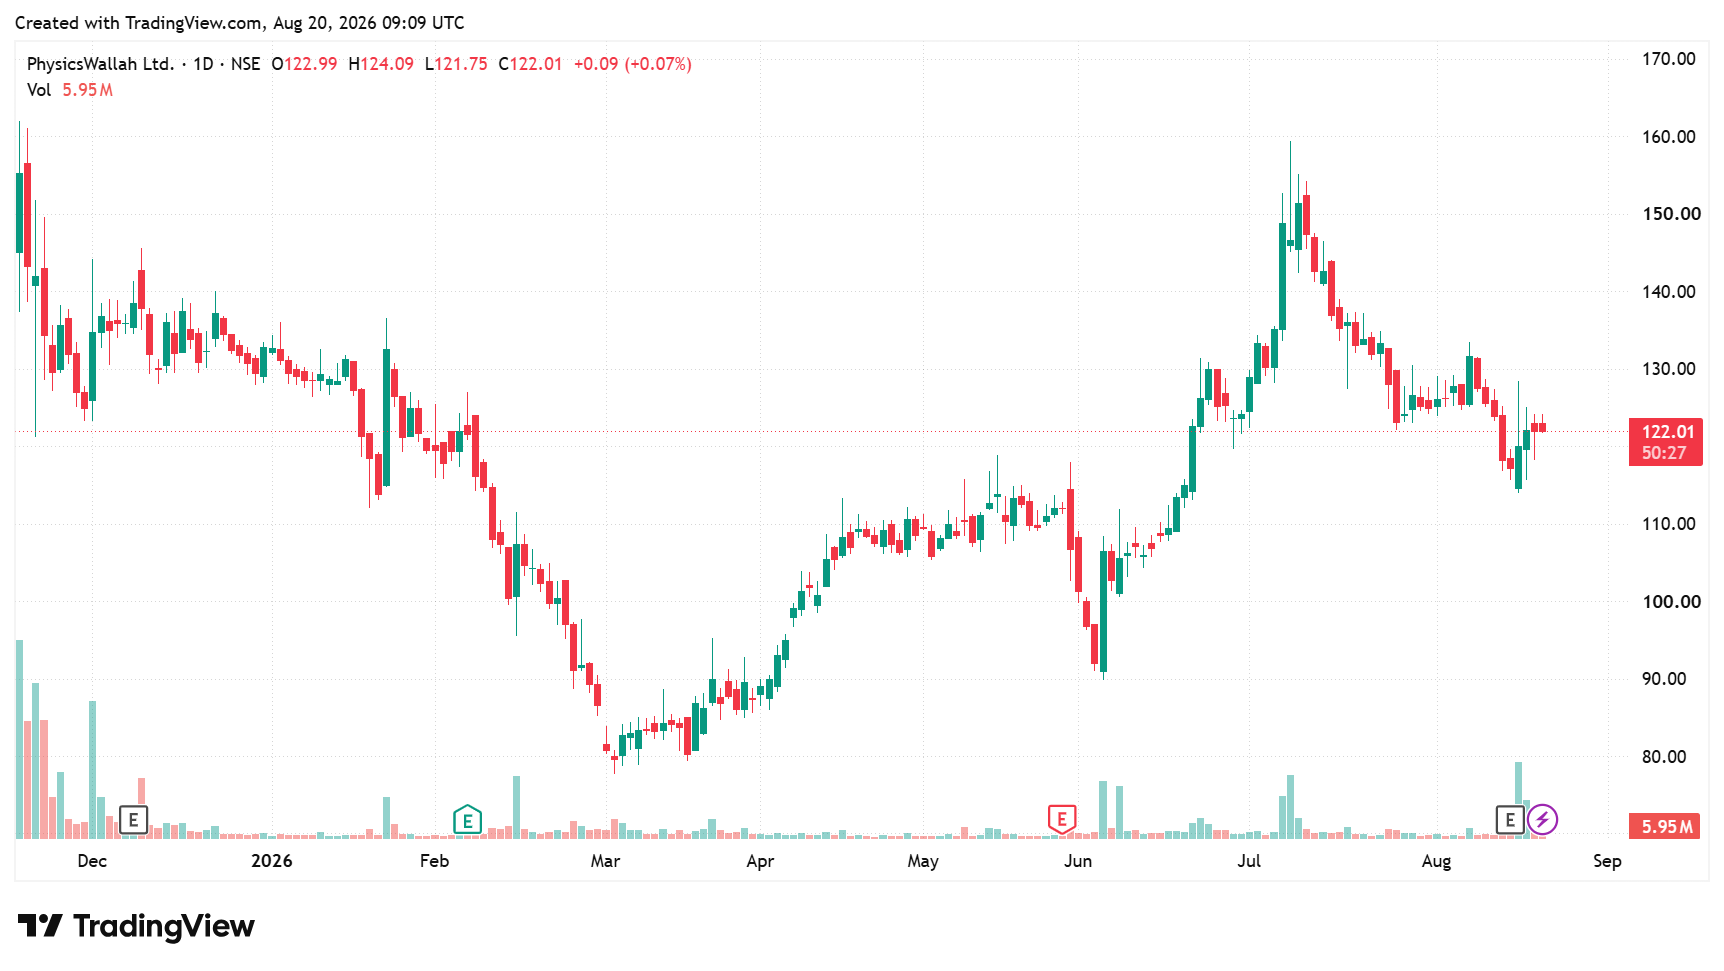
#2 Veranda Learning: Building Growth Through Diversification
Veranda Learning is an integrated learning platform. It offers diversified educational offerings in online, offline, and hybrid formats to students, aspirants, and corporate professionals. Veranda offers educational content such as Commerce Test Preparation, Government Test Preparation, and Academics (K-12 Managed Schools).
Q1FY27 Financials: Net Profit Surged 476% on 35% Enrollment Jump
Veranda has shown strong growth in Q1FY27. Revenue from operations grew 42% year-on-year to ₹150 crore, driven by 35% higher student enrollments. EBITDA surged 30% to ₹54 crore (excluding other income of ₹17.3 crore in Q1FY26), with margins at 36%. Net profit grew 476.3% to ₹34 crore from a lower base of ₹5.9 crore.
Scaling the Commerce Segment Without Heavy Capital Expenditure
Several factors drove this growth. Veranda launched a live and recorded digital delivery format targeting Class 11/12 students. This allows it to build a digital footprint across India and open up a high-growth market without incurring the capital costs of building physical infrastructure.
The company is doubling its managed commerce college footprint. In addition to its existing physical network of over 105+ centres, Veranda is expanding its managed colleges into 15 new locations with 50 new colleges in the pipeline. It is also rolling out its full suite of professional commerce courses across all 105+ existing physical centres.
Localised RACE Expansion and New Pre-School Operations
In the government test preparation space, Veranda is expanding its core RACE test prep brand in Karnataka. This expansion aims to target state-level competitive exams with localised course content and new offline coaching centres. In the K-12 segment, Veranda is entering preschool managed operations.
Beyond these expansions, reduction in customer acquisition costs (CAC) and deleveraging could aid earnings growth. Advertising expenses as a percentage of revenue have dropped from 31.2% in FY25 to just 4.8% in FY26 as the company focuses on organic enrollments. Veranda has deleveraged its balance sheet.
This successful deleveraging resulted in a 67% year-over-year reduction in finance costs to ₹8.7 crore. Going forward, quarterly finance costs are expected to remain in the range of ₹8 crore. Veranda has already been a free-cash-flow-positive company.
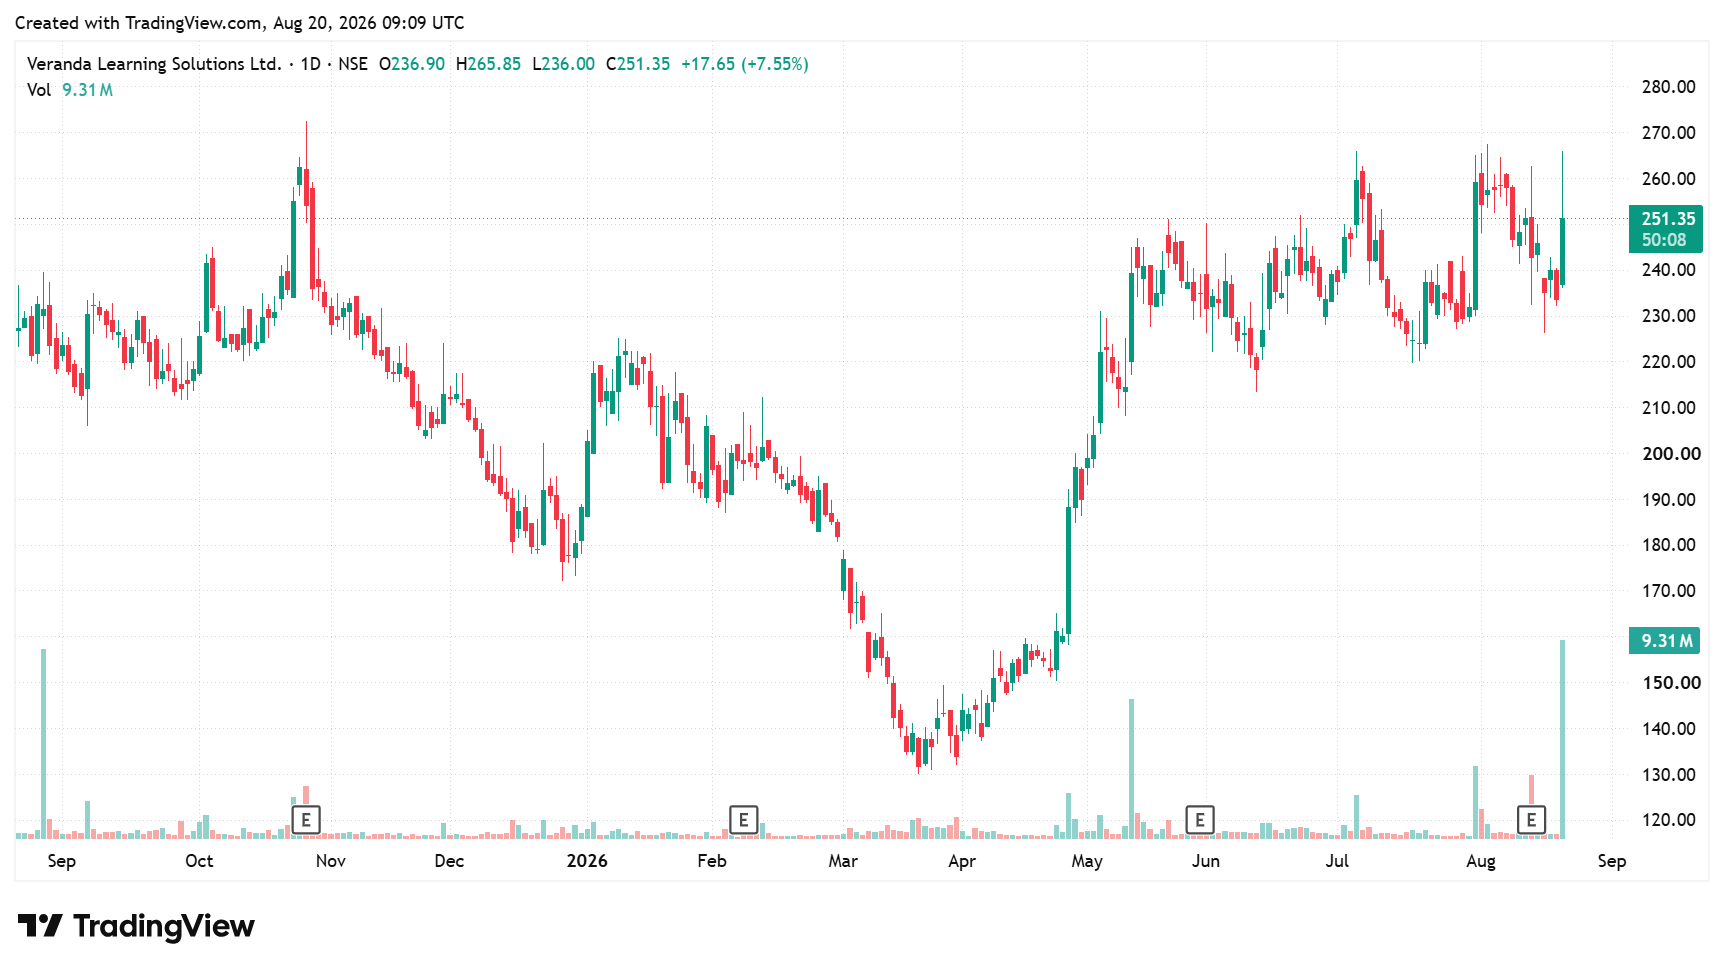
#3 Jaro Institute of Technology: Monetising India’s Online Higher-Education Shift
Jaro Institute of Technology has a major presence in India’s online higher education sector. It has a partnership with 33 institutions, including Indian Institutes of Management (IIMs), Indian Institutes of Technology, and top-ranked universities.
Jaro enters into long-duration contractual agreements ranging from 3 to 7+ years with marquee universities. This mitigates partner churn and secures long-term exclusive program pipelines. Jaro manages the entire program lifecycle, including student outreach, marketing, counselling, onboarding, and online or hybrid technology-enabled delivery.
The company operates on a fee-sharing model. This model spans programs over several months and years, giving Jaro strong and consistent revenue visibility. Specifically, long-duration degree programs act as a major revenue anchor (accounting for 85% of total Q1 FY27 admissions).
Q1FY27 Financials: Net Profit Surges 48% on Operating Leverage
Jaro reported 19% year-on-year revenue growth to ₹72.6 crore in Q1FY27. EBITDA surged 21% to ₹17 crore with margins at 23%. As a result, net profit grew 48% to ₹11.2 crore, driven by operating leverage and disciplined cost controls.
Expanding Gross Bookings Amid B2B Growth
The company saw positive traction in operating metrics. Gross bookings rose by 71% to ₹190.3 crore. Total admission enrollment increased 12%, while ARPU increased just 4% to 86,609. The partnership with J.K. Shah Classes could be a near-term growth trigger. Jaro reported free cash flow of ₹57 crore in FY26 and positive operating cash after two years.
Unlocking a 42-Lakh Learner TAM and Scaling B2B Enterprise Upskilling
This partnership unlocks a Total Addressable Market of approximately 42 lakh potential learners across India. Further, Jaro is focusing on scaling its B2B enterprise learning business. It has onboarded 14+ enterprise clients, including HCLTech, PNB MetLife, and Sutherland. This creates a steady, scalable revenue stream from enterprise workforce upskilling.
Reliance Jio Partnership Aims to Drive Smart TV Course Distribution
The company has also collaborated with Reliance Industries to include its offerings with JioFiber, JioAirFiber, and JioSet-top boxes. This tie-up aims to enable higher course distribution through smart Televisions. Using this, it aims to reach underpenetrated homes.
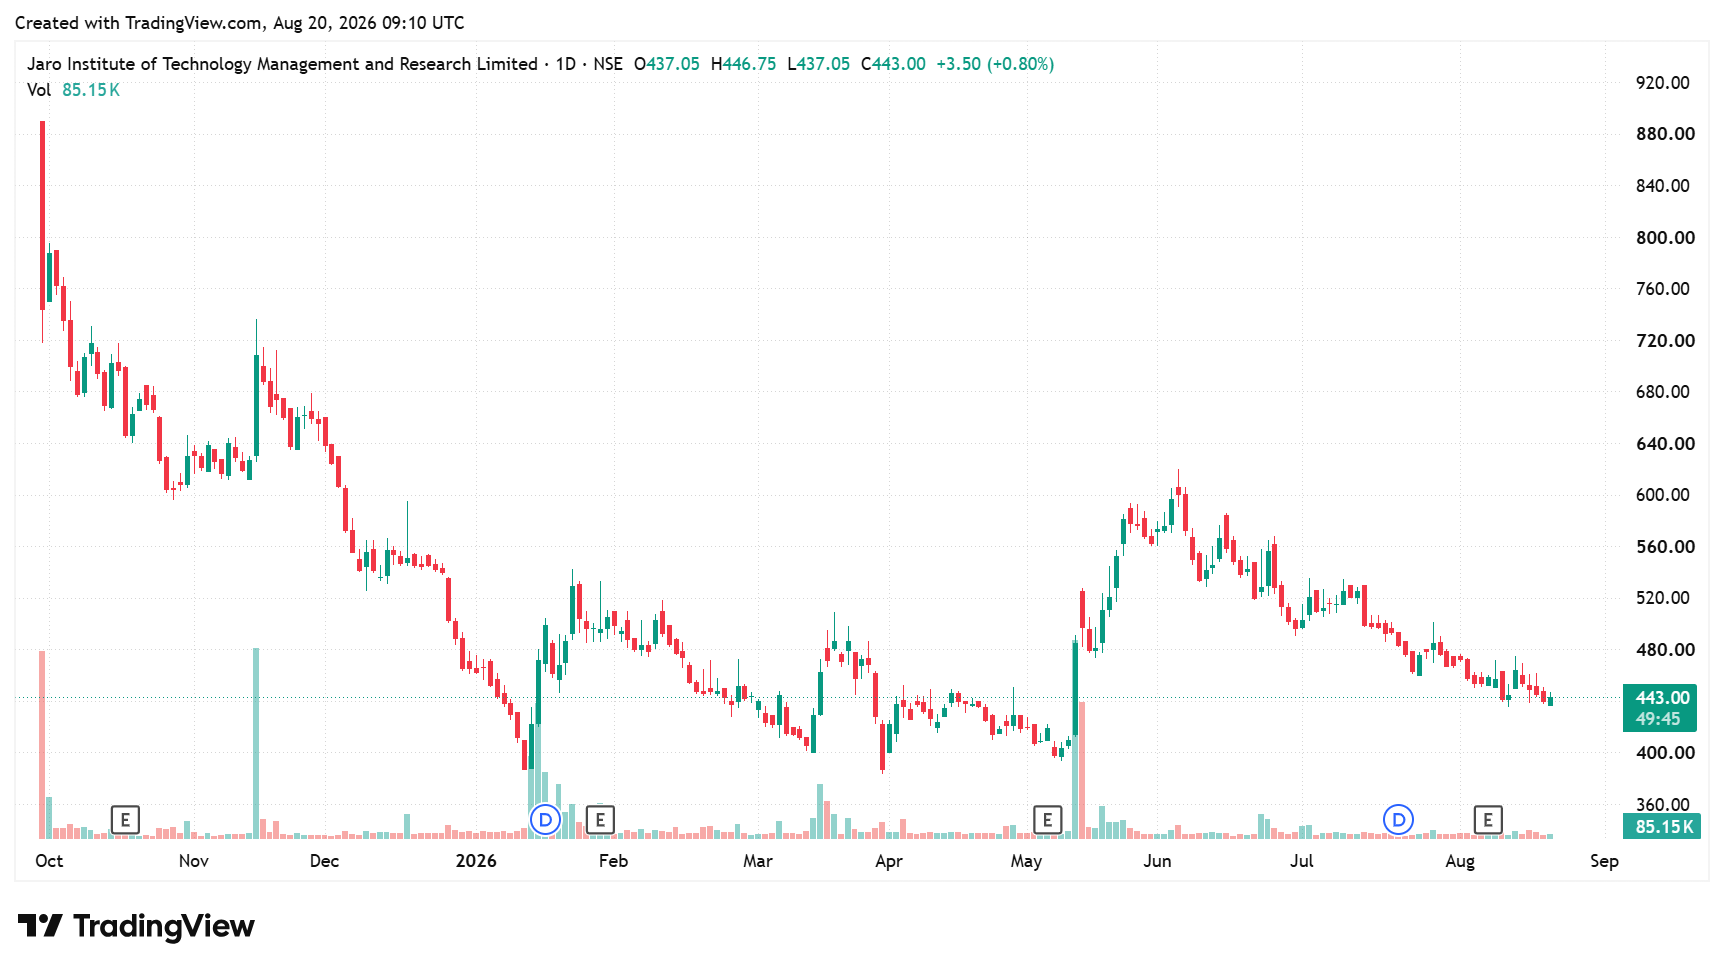
Bridging the Margin Gap: Peer Valuations
To better analyse the valuation, we have used the Price-to-Sales (P/S) metric. Accordingly, PhysicsWallah, being the largest listed player in the E-Learning space, trades at a premium to the industry P/E multiple. On the other hand, Veranda trades at a discount. Jaro’s valuation is at a discount to both the industry and the historical 3-year median.
| Peer Comparison (X) | |||||
Company | Market Cap (₹ Crore) | Price-to-Sales Multiple | Return Ratios | ||
| Company | 3Y Median | ROCE (%) | ROE (%) | ||
| PhysicsWallah | 35,500.0 | 8.6 | NA | 4.0 | NA |
| Veranda Learning | 2,491.0 | 4.8 | NA | 12.8 | 3.8 |
| Jaro Institute | 985.0 | 3.5 | 4.8 | 22.1 | 16.5 |
| Industry | NA | 5.8 | 17.5 | 10.2 | |
| Source: Screener.in (As of 19 August 2026) | |||||
The listed education and e-learning space is still at an early stage, but the underlying opportunity is expanding as online learning gains wider adoption.
PhysicsWallah offers scale and a potential earnings inflection as its online business grows and the offline segment moves towards breakeven. Veranda combines improving profitability with expansion across commerce and test preparation.
Meanwhile, Jaro offers higher-margin courses through long-duration university partnerships. Valuations remain mixed, with Jaro and Veranda trading below the industry P/S multiple. Meanwhile, keep them on your watchlist.
Disclaimer:
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation. We used an alternative, widely accepted source of information only when the data were unavailable.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
About the Author: Madhvendra has been deeply immersed in the equity markets for over seven years, combining his passion for investing with his expertise in financial writing. With a knack for simplifying complex concepts, he enjoys sharing his honest perspectives on startups, listed Indian companies, and macroeconomic trends.
A dedicated reader and storyteller, Madhvendra thrives on uncovering insights that inspire his audience to deepen their understanding of the financial world.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources, and only after consulting such independent advisors as may be necessary.