



Construction is a business where a company can sell a lot and still make very little money. The industry is fragmented, procurement involves several layers of suppliers and intermediaries, and a large part of the value created can disappear between the manufacturer, distributor, contractor and developer.
A different model is beginning to emerge. Instead of putting large amounts of capital into owning factories, a company can tie up manufacturing capacity, bring developers and contractors onto its network, use technology to manage procurement and then move into higher-margin services.
That is where Arisinfra Solutions becomes interesting. Its latest numbers suggest that the company is not merely growing its construction-materials business, but is changing the mix of that business, with contract manufacturing and Developer-as-a-Service, or DaaS, becoming much more important.
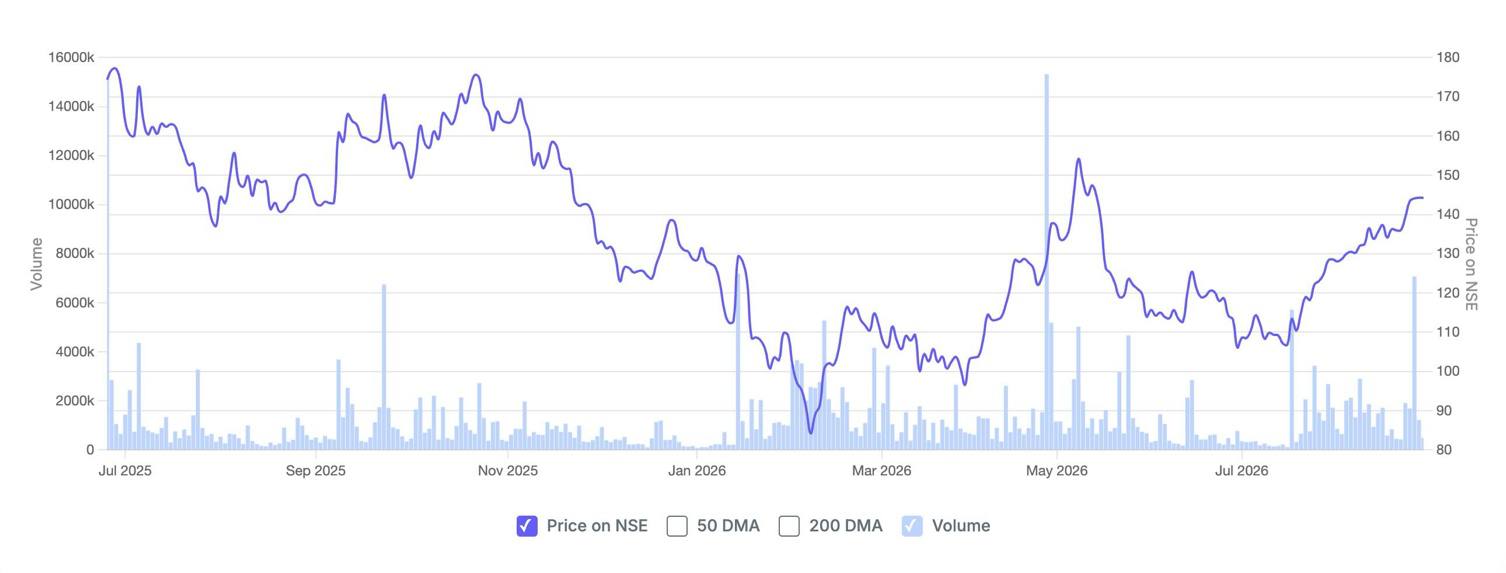
Arisinfra Solutions Ltd 1-Year Share Price Chart
The change is already visible in the numbers. In Q1 FY27, revenue rose 37% year-on-year to Rs 291 crore, while operating profit rose to Rs 31 crore from Rs 18 crore a year earlier , taking the operating profit margin to 11% from 8.5%. Net profit rose to Rs 20 crore from Rs 5 crore.
Join now
The construction middleman is changing
Arisinfra is a business-to-business, or B2B, technology-enabled company that supplies construction materials to real estate and infrastructure developers and contractors. Its model combines procurement, logistics and technology with a network of vendors and manufacturing partners, rather than relying on a large manufacturing base of its own.
The company says it serves more than 3,400 customers through over 2,200 vendors across 23 states and union territories. Repeat orders accounted for more than 82% of business in Q1 FY27, according to management.
The B2B supply business remains the entry point. But the more interesting part is what happens after Arisinfra gets a customer onto its network.
Under contract manufacturing, the company secures production capacity through long-term arrangements with manufacturing partners. Under DaaS, it works with developers across parts of the project lifecycle while earning fees without taking ownership of the underlying real estate project.
That creates a business with three different economic engines. The first generates volume and customer relationships, while the other two have the potential to generate much higher margins.
The money is moving to higher-margin businesses
The biggest change in the latest quarter was not simply revenue growth. It was the change in the composition of that revenue.
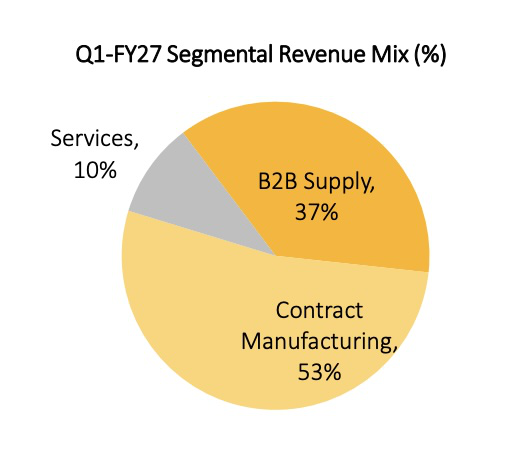
As per the company, contract manufacturing and DaaS together increased their contribution to revenue from about 46% to 63% in Q1 FY27. Management also said these businesses carry meaningfully higher margins than B2B trading and that the change in mix was the main reason for the expansion in EBITDA margin.
The financial history shows why this matters. Consolidated sales increased from Rs 768 crore in FY25 to Rs 1,067 crore in FY26, a growth of about 39%. Operating profit rose from Rs 48 crore to Rs 101 crore, a growth of about 110%, while the operating profit margin improved from 6% to 9%. Net profit rose from Rs 6 crore to Rs 60 crore.
This is the part of the story investors need to understand. A company growing sales quickly is not necessarily becoming a better business, but a company growing sales while shifting towards activities with better economics can see profits grow much faster than revenue.
That is what Arisinfra has managed so far.
Contract manufacturing is the real pivot
Contract manufacturing has become the largest part of the new model. It accounted for 53% of revenue in Q1 FY27, with segment revenue growing 84% year-on-year.
The company delivered about 8.65 lakh metric tonnes during the quarter. Existing annual capacity is around 9 million metric tonnes, with utilisation at about 65% to 70%.
Arisinfra plans to add 2 million to 3 million tonnes of annual capacity over the next two quarters, taking total capacity to roughly 11 million tonnes. The additional capacity can be created by recycling existing security deposits, without fresh deposits or significant capital expenditure.
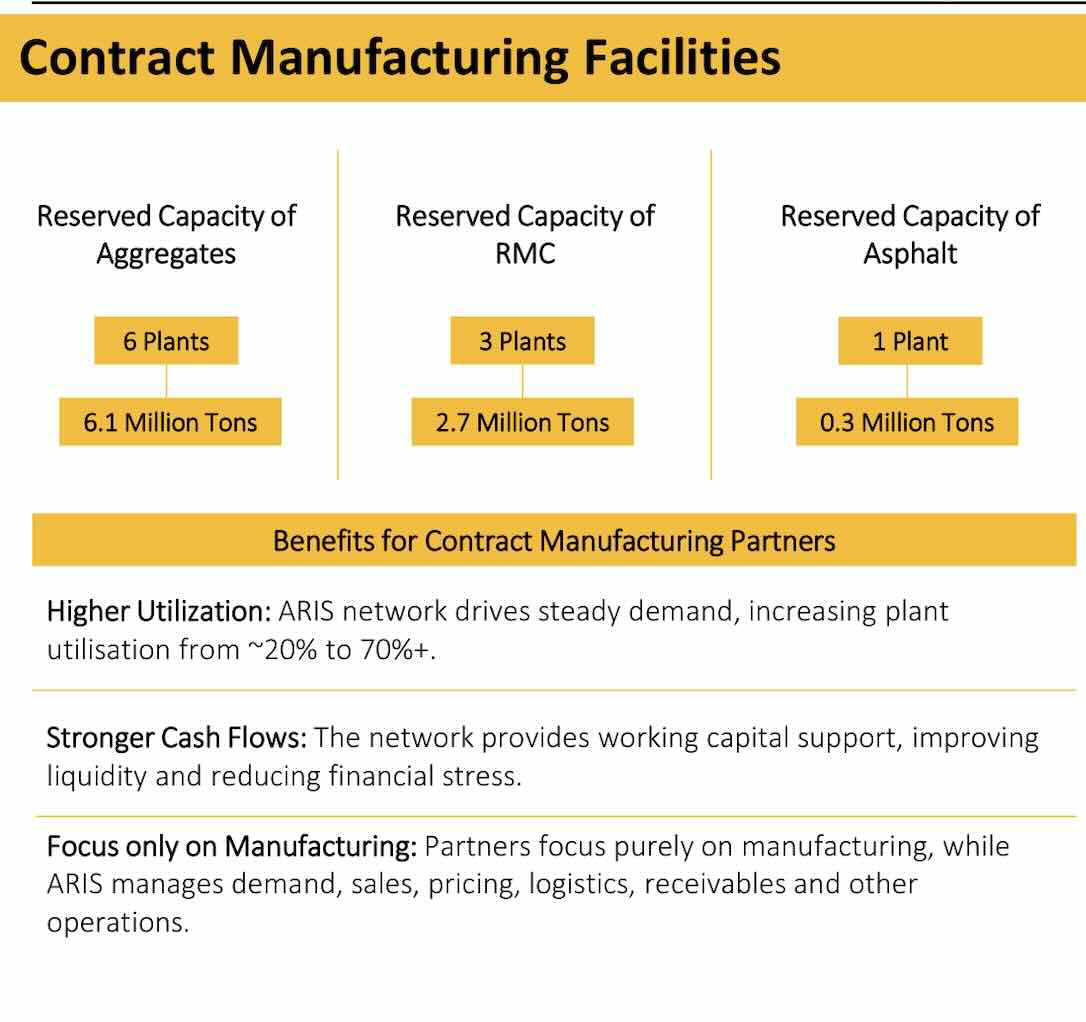
That allows the company to increase volumes without building a conventional manufacturing balance sheet. The plants remain with manufacturing partners, while Arisinfra controls the customer relationship and access to capacity.
The model is also finding applications beyond its traditional materials business. In July, the company secured a Rs 79.05 crore work order from the J Kumar-NCC joint venture for the Goregaon-Mulund Link Road tunnel project in Mumbai, involving the loading, transportation and disposal of excavated tunnel material.
The order will not transform the company on its own, but it shows Arisinfra moving beyond construction materials into a broader range of infrastructure-linked services.
Developers are becoming customers, not just buyers
DaaS is the other part of the pivot, and it is beginning to give Arisinfra access to a much larger pool of revenue around each developer relationship. During Q1 FY27, the company secured a Rs 650 crore DaaS mandate from Wadhwa Group, taking the gross development value, or GDV, of projects under management to more than Rs 1,800 crore across 10 projects, from Rs 1,250 crore at the end of Q4 FY26.
The Rs 1,800 crore is not revenue for Arisinfra. It is the value of the real estate projects on which the company is providing its services, with Arisinfra earning fees over the life of those projects. Most DaaS projects run for 18 to 24 months, and the business contributed about Rs 28 crore, or roughly 10% of Q1 FY27 revenue.
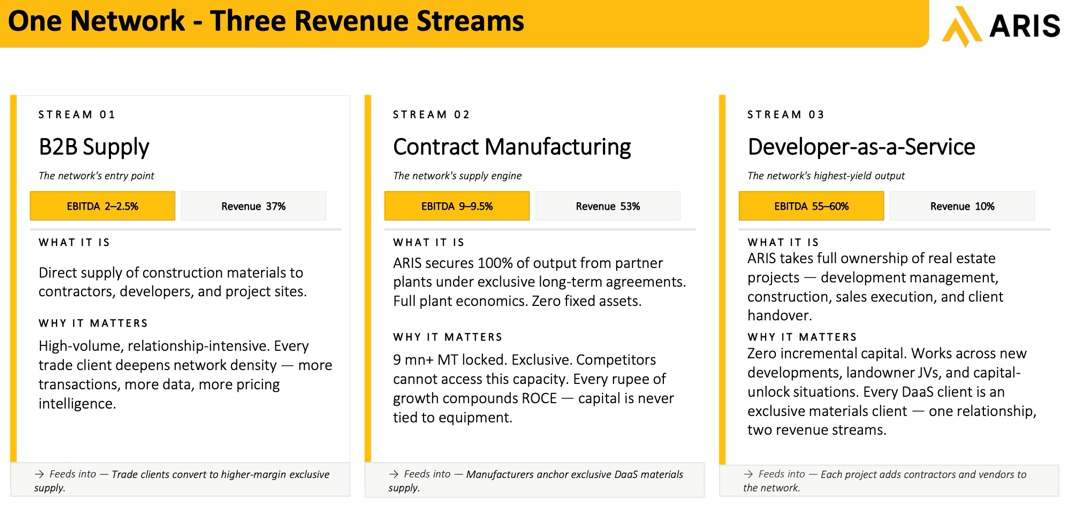
The economics are what make DaaS particularly interesting. Management has indicated that the business can generate EBITDA margins of around 60% to 65%, while Arisinfra does not put capital into the underlying real estate projects.
This gives the company a way to participate in the growth of a project without having to fund the land, construction or inventory on its own balance sheet. The developer remains responsible for its own project financing, while Arisinfra earns fees for the services it provides.
Management wants DaaS to contribute around 9% to 11% of revenue. That may sound relatively small, but a business contributing 10% of revenue at a 60% to 65% EBITDA margin can have a meaningful impact on the profitability of a company whose traditional construction-materials business operates at much lower margins.
That is the bigger attraction. DaaS does not have to become Arisinfra’s largest business to change the economics of the company.
Margins are improving, but growth is the test
The margin improvement is striking. Consolidated operating profit margins rose from negative levels in FY22 and FY23 to 1.8% in FY24, 6% in FY25 and 9% in FY26, before reaching 11% in Q1 FY27.
The improvement has been driven mainly by the higher contribution from contract manufacturing and DaaS, and management expects the current levels to sustain over the next few quarters. The company does not need to become a 15% or 20% margin business; the key is whether it can sustain around 10% to 11% while growing revenue at 35% to 40%.
Management has maintained its FY27 revenue growth guidance at 35% to 40%, with no formal guidance yet for FY28 or FY29. It also expects the second half to contribute about 60% of annual sales, compared with 40% in the first half, so quarterly revenue is unlikely to be evenly spread through the year.
For investors, the test is straightforward: can Arisinfra deliver the guided growth without giving back the margin gains that have changed the earnings profile?
Working capital is where the story can get tested
A fast-growing construction business can look excellent on the profit and loss statement while consuming large amounts of cash through receivables. That makes working capital particularly important as Arisinfra scales.
Net working-capital days were 56 days in Q1 FY27, compared with 66 days in March 2026, and management expects the longer-term range to remain around 60 to 70 days. At the same time, cash generation has improved sharply, with cash from operating activities turning positive at Rs 142 crore in FY26 from negative Rs 21 crore in FY25.
Collections were more than Rs 1,100 crore in the previous year, and the company believes its relationships with customers give it better visibility into their cash flows and credit quality. The key question now is whether cash generation can continue to keep pace with reported profit as revenue grows at 35% to 40%.
Debt is no longer the biggest worry
The balance sheet has improved substantially. Consolidated borrowings fell from Rs 343 crore in FY25 to Rs 70 crore in FY26, while reserves rose from Rs 219 crore to Rs 723 crore.
Management said net debt was around Rs 14.5 crore at the end of Q1 FY27. It expects that figure to rise to roughly Rs 75 crore to Rs 80 crore by the end of FY27 and wants to keep net debt-to-equity at no more than about 0.5 to 0.6 times.
The expected increase in debt is therefore not necessarily a warning sign. The company is growing quickly and some additional working-capital funding is part of that growth, but the important thing is that management has put a ceiling on leverage.
The stronger balance sheet also gives the company more room to pursue its asset-light strategy without having to fund large manufacturing investments itself.
Returns have room to improve
Consolidated return on capital employed (ROCE) of 15.6% and return on equity (ROE) of 11.2%. More importantly, the annual ROCE has risen from 4% in FY24 to 12% in FY25 and 16% in FY26.
That improvement is consistent with the broader story. As the company earns more operating profit without a proportionate increase in fixed assets, returns on capital can improve.
But there is still a relatively short history here. Investors have not yet seen how these returns behave through a weaker construction cycle, or what happens if the mix shifts back towards lower-margin B2B trading.
For now, the direction is encouraging. The next step is proving that the improved returns can survive at a much larger revenue base.
The stock has already taken a beating
The market has not exactly rewarded the operating improvement so far. Arisinfra’s IPO was priced at Rs 222 and the stock listed at Rs 205 in June 2025, but subsequently fell as low as about Rs 82 before recovering.
At Rs 144.26, it remains roughly 35% below its IPO price and trades at about 17.7 times earnings. The recent recovery means the stock is no longer near its lows, but investors are still waiting for the margin improvement to prove durable.
The stock has also caught the attention of ace investor Mukul Agrawal. He held 13 lakh shares, or a 1.59% stake, at the end of Q1 FY27, making Arisinfra a new disclosed holding in his portfolio.
Risks investors should keep on the radar
Customer concentration is one. The top 10 customers account for roughly 45% to 50% of revenue, although the largest customer is spread across more than 15 project sites. A delay at a major customer or a change in procurement strategy could therefore affect growth.
There is also the recent auditor change. Price Waterhouse Chartered Accountants LLP resigned as statutory auditor in May 2026 after a disagreement over the proposed audit fee, having already signed off on the FY26 accounts without qualifications. The company has since appointed M S K C & Associates LLP, so there is no basis to treat the change as evidence of an accounting problem, but it remains worth watching as the business expands.
The FY27 test is whether the mix can keep improving
Arisinfra does not need to become a completely different business for the story to work. It needs to show that contract manufacturing and DaaS can keep increasing their contribution while the company grows without losing control of cash and working capital.
At around Rs 144, the stock trades at roughly 17.7 times trailing earnings. That is no longer the valuation at which investors were buying the IPO, but it still assumes that the recent improvement in profitability has some staying power.
The next few quarters should therefore tell investors more than another headline revenue number. If the company can grow at the guided 35% to 40% rate while retaining its improved margins, Arisinfra could gradually move from being seen as a construction-materials supplier to a higher-margin services and procurement business.
Disclaimer:
Note: We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Manvi Aggarwal has been tracking the stock markets for nearly two decades. She spent about eight years as a financial analyst at a value-style fund, managing money for international investors. That’s where she honed her expertise in deep-dive research, looking beyond the obvious to spot value where others didn’t. Now, she brings that same sharp eye to uncovering overlooked and misunderstood investment opportunities in Indian equities. As a columnist for LiveMint and Equitymaster, she breaks down complex financial trends into actionable insights for investors.
Disclosure: The writer and her dependents do not hold the stocks discussed in this article. The website managers, its employee(s) and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.