



The Indian construction industry is entering a phase where speed is becoming as important as scale. A warehouse, factory, or data centre can no longer afford years of construction when demand is moving faster. That is creating a larger role for pre-engineered buildings (PEBs).
CRISIL estimates India’s PEB market has already grown from ₹13,000 crore in FY19 to ₹21,000 crore in FY25. More importantly, growth is expected to accelerate to 9.5-10.5% CAGR through FY30, taking the market to ₹33,000-34,500 crore. The opportunity is also moving beyond traditional industrial sheds.
India’s data centre capacity is expected to rise from 900-950 megawatts (MW) in FY24 to 2,000-2,300 MW by FY27. Semiconductor facilities and renewable energy manufacturing are also joining this demand pool, where faster construction can be a competitive advantage. Yet, PEBs still account for only 3-5% of India’s overall construction market.
As organised players gain share and PEB penetration rises across industrial and infrastructure projects, the industry appears to be moving from a niche construction method toward a larger structural component of India’s capex cycle. Against this backdrop, two PEB players are focusing heavily on the data center opportunity.
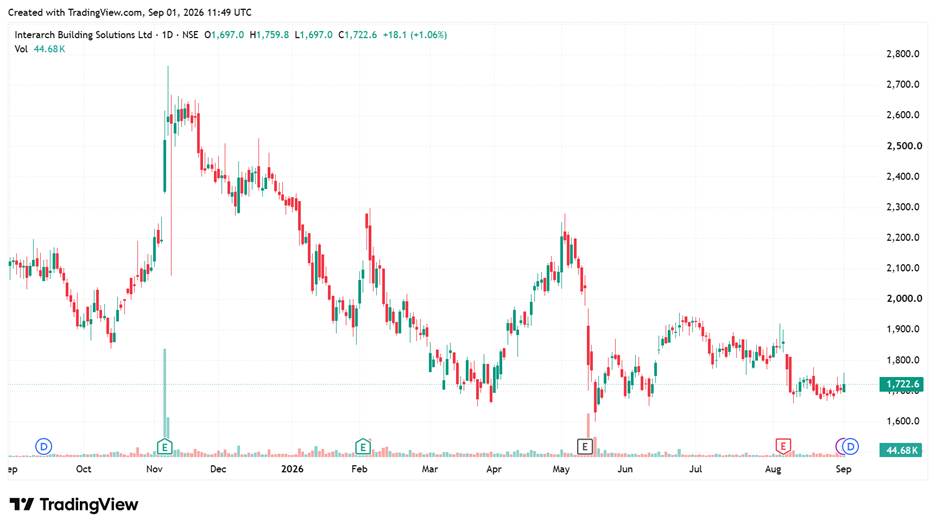
#1 Interarch Building Solutions: Bridging the Heavy Structural Gap for High-Spec Infrastructure
Interarch Building Solutions is one of the leading turnkey pre-engineered steel construction solutions providers in India. It manages the entire product lifecycle, including estimation, design, engineering, fabrication, and on-site project management for installation and erection. It operates five fully integrated manufacturing plants and a sixth PEB facility overall.
After the commissioning of Phase-1 of the Gujarat plant, the total production capacity of the company has increased to 221,000 Metric Tons. Interarch is focusing on new-age high-growth industries like electric vehicles, lithium batteries, semiconductors, data centers, and renewable energy.
Clean Energy and Data Centers Power 35% of Interarch’s ₹1,864-Crore Order Book
These segments represented around 35% of its ₹1,864 crore order book as of mid-2026. It recently secured a ₹165 crore order from a major energy company in Vadodara. The company has built a Solar PV manufacturing plant in Dholera (Gujarat) and Jaipur. It has also built a data center building in Navi Mumbai and in Noida for RailTel Corporation.
Why the Andhra Plant Shift Unlocks 20-Ton Heavy Structural Steel In-House
Historically, Interarch bid for certain complex projects due to a lack of required in-house machinery. For example, at the Tata Electronics semiconductor plant or some lithium battery plants, they had to outsource 15% to 20% of the heavy structural manufacturing work.
The remaining 80% to 85% had to be delivered through standard PEB. To eliminate this bottleneck, Interarch has initiated trial production at its new heavy steel structures plant in Andhra Pradesh. The plant is scheduled to begin commercial production by September 2026. Previously, Interarch’s plant could only weld columns and beams weighing 4 to 5 tons.
Now, it can produce structural steel elements weighing up to 20 tons. This capability enables them to deliver hybrid systems entirely in-house. The newly inaugurated Phase 1 has increased the company’s total PEB capacity to 221,000 MT. Phase 2 is expected to be operational by October 2026.
Inside the FY28 Roadmap: Targeting ₹2,700 Crore Revenue and 10% EBITDA Margins
Interarch aims to achieve revenue of ₹ 2,150-2,200 crore for FY27 and ₹2,700 crore in FY28. To achieve this, it is looking to execute an average execution run rate of ₹600 crore per quarter over the next 3 to 4 quarters.
In terms of volumes, Interarch expects 18% volume growth and aims to deliver 190,000 tonnes in FY27. It reported an EBITDA (Earnings Before Interest, Tax, Depreciation, and Amortisation) margin of 8.6% in Q1FY27. Management is targeting a margin expansion to 9.5% to 10% in FY28.
Financially, revenue from operations increased 20.7% year-over-year to ₹459.6 crore in Q1FY27. EBITDA increased 24.6% to ₹39.4 crore. However, net profit declined 0.5% to ₹28.2 crore due to lower interest income and higher depreciation costs.
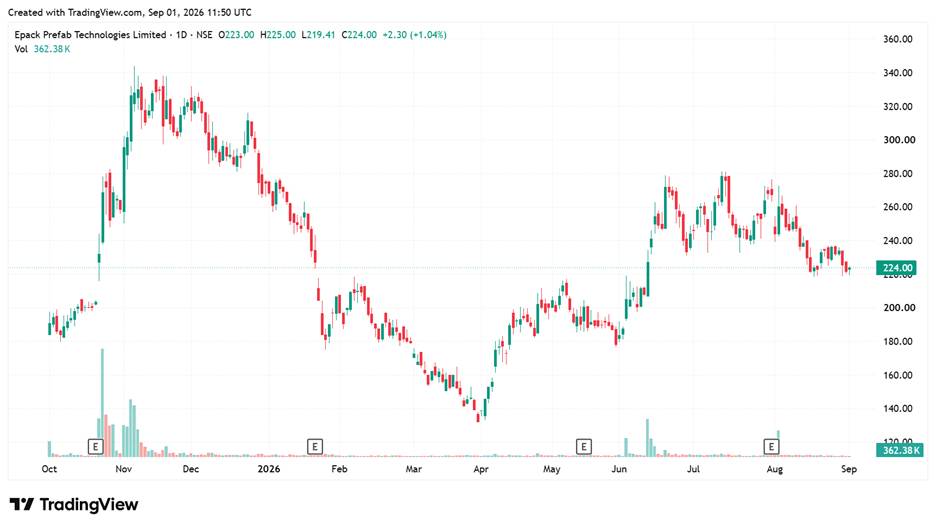
#2 EPACK Prefab Technologies: Scaling Capacity to 220,000 MTPA for Hyper-Scale Data Centers
EPACK Prefab Technologies is one of India’s fastest-growing pre-engineered and prefabricated solution providers. The company specializes in rapid, scale-driven construction projects across multiple industrial and commercial sectors. Currently, it has four existing manufacturing units spanning Uttar Pradesh, Rajasthan, and Andhra Pradesh.
EPACK’s PEB division has an annual capacity of 147,122 MT. Capacity utilization reached 75.2% in Q1FY27, with some plants operating at nearly full capacity. Management stated that utilization sometimes reached 80% to 85% during peak quarters.
Capex Roadmap: Scaling PEB Capacity Past 220,000 MT
EPACK Prefab is executing a capex of ₹160 crore in Ghiloth and Mambattu. It is also setting up a greenfield plant in Gujarat. The company is adding a second structural steel fabrication line, which will add an annual PEB capacity of 23,600 MT. The line is expected to become operational from the third quarter of FY27.
There is another plant in Gujarat with a capacity of 50,000 MT, which will start production in April 2027.The company also has 1,310,000 square meters (SQM) of sandwich insulated panels. EPACK is commissioning a continuous sandwich panel line with an 800,000 SQM capacity. Once fully operational, this line is expected to generate ₹125 to ₹140 crore in product sales. The plant is expected to be operational in Q3FY27.
FY27 Targets: ₹1,950-Crore Revenue & 10.5% EBITDA Margins
All these incremental capacities will bring the total PEB capacity to over 220,000 MTPA. The company’s peak revenue potential is estimated to climb to ₹2,700 crore to ₹2,900 crore. EPACK expects revenue to grow by 30% year-on-year to ₹1,900-1,950 crore in FY27. EBITDA margins are expected to be 10.5% for the full year.
The company’s order backlog of ₹1,380 crore provides execution visibility for the next 6 to 8 months. EPACK is targeting ₹2,000 crore in total order inflow for FY27. In Q1FY27 alone, it received orders worth ₹580 crore. EPACK is also shifting its focus toward high-margin sectors.
The Tech Pivot: Chasing Hyper-Scale Data Center Deals
EPACK has become a preferred partner in the green energy sector. It has received a ₹165 crore order (its largest single contract to date) to build a solar cell and module manufacturing plant. It has also created a dedicated subsidiary to focus on hyper-scale data center structures using the Design for Manufacturing and Assembly (DFMA) system.
The company has already bid on full turnkey projects. It aims to secure at least one turnkey data center order in the near term. From a financial perspective, revenue rose 23.9% year-on-year to ₹365.8 crore. EBITDA surged 11.7% to ₹34.5 crore while margin fell 100 bps to 9.4%. Net profit grew 13.8% to ₹18.2 crore.
Here’s a snapshot of the Q1FY27 financial performance:
| Particulars | EPACK | Interarch |
| Revenue (Growth YoY) | ₹365.8 crore (+23.9%) | ₹459.6 crore (+20.7%) |
| EBITDA (Growth) | ₹34.5 crore (+11.7%) | ₹39.4 crore (+24.6%) |
| EBITDA Margin | 9.4% | 8.6% |
| Net Profit | ₹18.2 crore (+13.8%) | ₹28.2 crore (-0.5%) |
| Order Book | ₹1,380 crore | ₹1,864 crore |
| FY27 Outlook | ₹1,900-1,950 crore revenue; 10.5% EBITDA margin | ₹2,150-2,200 crore revenue; 9.5–10% EBITDA margin |
The table shows that Interarch delivered stronger EBITDA growth and a larger order book. EPACK recorded faster revenue and net profit growth. Interarch also has a higher FY27 revenue target, whereas EPACK is targeting a slightly higher EBITDA margin of 10.5%.
Financial & Valuation Matrix: Execution Backlog vs Return Ratios
EPACK boasts a marginally stronger Return on Equity than Interarch, while the latter has a strong Return on Capital Employed. In terms of valuation, EPACK is trading at a discount to the industry median, while Interarch trades at a premium. Both are newly listed and hence have limited trading history.
| Peer Comparison (X) | ||||
| Particulars | Price-to-Earning Multiple | Return Ratios | ||
| Company | Industry | ROE (%) | ROCE (%) | |
| EPACK | 23.9 | 32.3 | 17.0 | 21.7 |
| Interarch | 21.2 | 16.4 | 16.8 | 23.7 |
The addition of data centres, semiconductor plants and renewable energy facilities is widening the addressable market for PEB players. Both companies are responding by expanding capacity and targeting newer, higher-value segments. Interarch is strengthening its heavy structural steel capabilities, while EPACK is building a dedicated focus on hyperscale data centres.
As strong contenders, these stocks are worth keeping on your watchlist.
Disclaimer
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation. Only in cases where the data was unavailable have we used an alternative, widely used, and accepted source of information.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
About the Author: Madhvendra has been deeply immersed in the equity markets for over seven years, combining his passion for investing with his expertise in financial writing. With a knack for simplifying complex concepts, he enjoys sharing his honest perspectives on startups, listed Indian companies, and macroeconomic trends.
A dedicated reader and storyteller, Madhvendra thrives on uncovering insights that inspire his audience to deepen their understanding of the financial world.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources, and only after consulting such independent advisors as may be necessary.