



Every hospital has two businesses running side by side. One is visible to the patient: doctors, nurses, tests and treatment. The other happens behind the scenes, where medical records have to be coded, bills submitted, clinical documentation completed and insurance claims processed.
For US hospitals, much of this work has become too complex and expensive to handle entirely in-house. That has created a large opportunity for companies that can take over these administrative tasks and use technology to make them more efficient.
One company that has built a profitable business around this opportunity is Inventurus Knowledge Solutions (IKS Health). It helps US healthcare providers with medical coding, billing, clinical documentation and other administrative workflows, allowing doctors and hospitals to spend more time on patient care.
Join now
Inventurus Knowledge Solutions 1-Year Share Price Chart
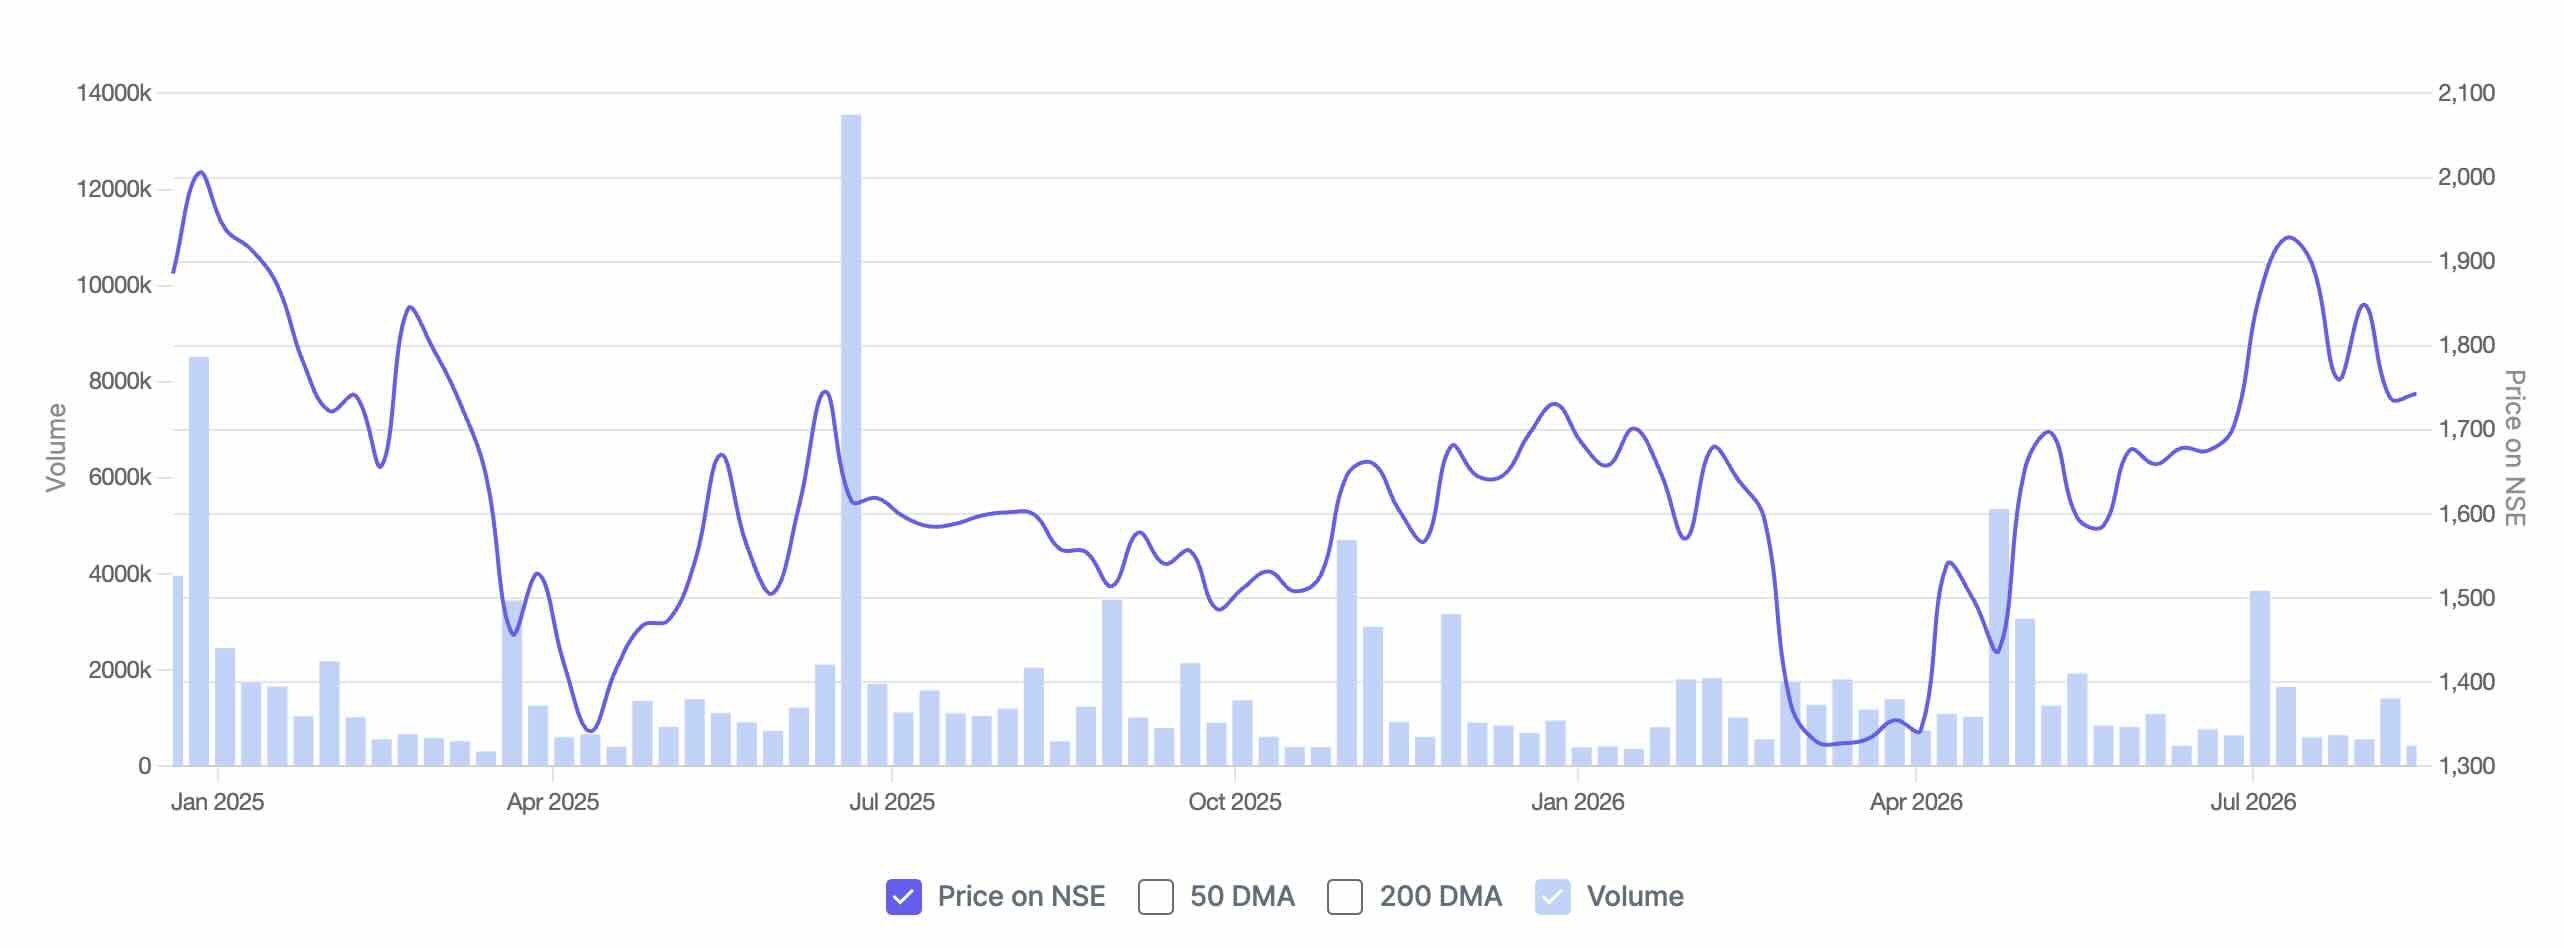
The business is already sizeable and profitable. Revenue grew 19.9% in FY26, while EBITDA margin expanded to 34.2%. In Q1 FY27, revenue grew another 20.7% YoY, while EBITDA margin stood at 33%.
But the company is now trying to build a second engine of growth.
In July, IKS completed the acquisition of TruBridge, a healthcare technology company that serves rural and community hospitals. The deal gives IKS access to more than 2,100 hospitals and, more importantly, brings together TruBridge’s electronic health record platform with IKS’s workflow automation and administrative services.
Now this changes the opportunity in front of the company. Instead of simply handling work after a patient has been treated, IKS can now sit closer to the point where the patient’s information is created and stored.
This could allow the company to sell more services around the same hospital workflow, while giving it access to the data and processes needed to build its own healthcare artificial intelligence capabilities. The larger bet is that IKS can evolve from a healthcare outsourcing company into an integrated technology and services platform for hospitals.
IKS wants to move from the hospital’s back office to its operating system
To understand why TruBridge matters, it helps to understand what IKS actually does. A hospital treats a patient, but a long administrative chain begins after that. Someone has to record the treatment, assign the correct medical codes, prepare the claim, send it to the insurer, deal with denials and make sure the hospital eventually gets paid.
This is broadly what revenue cycle management, or RCM, is about. IKS has built a large business around these processes, with more than 85% of its revenue coming from repeat customers and relationships with its largest customers averaging more than five years.
The problem is that much of the information needed for this work sits inside an electronic health record, or EHR. The EHR is where the hospital records what happened to the patient.
Before TruBridge, IKS could help process that information, but it did not own the underlying system. TruBridge changes that equation. This is because its EHR platform serves rural and community hospitals. IKS can now potentially connect the system that stores the information with the system that acts on it. This is why the acquisition is more interesting than its revenue contribution alone.
The company is effectively trying to combine a System of Record with a System of Action. That means owning the place where healthcare information is recorded and the workflows that turn that information into administrative and financial outcomes. If that works, the customer relationship could become much harder to displace.
The acquisition brings IKS something money cannot easily buy
TruBridge gives IKS access to more than 2,100 rural and community hospitals, where management says the company has about a 30% market share. It also gives IKS access to more than five million patient records that can be de-identified and used to train proprietary small language models.
This is where the artificial intelligence opportunity becomes interesting. It would be a mistake to call IKS an AI company simply because it is training its own models. The bigger opportunity is to build AI into healthcare workflows such as clinical documentation, coding and billing, rather than offer hospitals a generic chatbot.
That matters because healthcare requires a high degree of accuracy. IKS says AI can achieve high levels of automation in non-deterministic tasks such as clinical documentation, while deterministic tasks such as medical coding and billing will continue to use rules and human oversight.
So the AI pitch is not about replacing healthcare workers. It is about using machines to handle more of the repetitive work while healthcare professionals supervise the output, potentially improving productivity and changing the economics of the business.
The real AI bet is not the model. It is what sits around the model
There are plenty of companies that can buy access to a large language model. The harder thing to replicate is a system containing healthcare data, healthcare workflows, customer relationships and trained employees who understand what the output should look like.
IKS says more than five million patient records available through TruBridge will be de-identified, meaning information that can identify individual patients will be removed, and used to train its proprietary small language models (SLMs), which are AI models built for specific healthcare tasks. The company also wants to build explainability into its generative AI workflows, so that users can understand why the system arrived at a particular recommendation, while human oversight and rules-based systems remain in place where required.
If this works, it could create a useful loop. More healthcare data can improve the models, better models can automate more of the workflow, and greater automation can reduce the amount of manual work required for each customer, improving productivity and eventually margins.
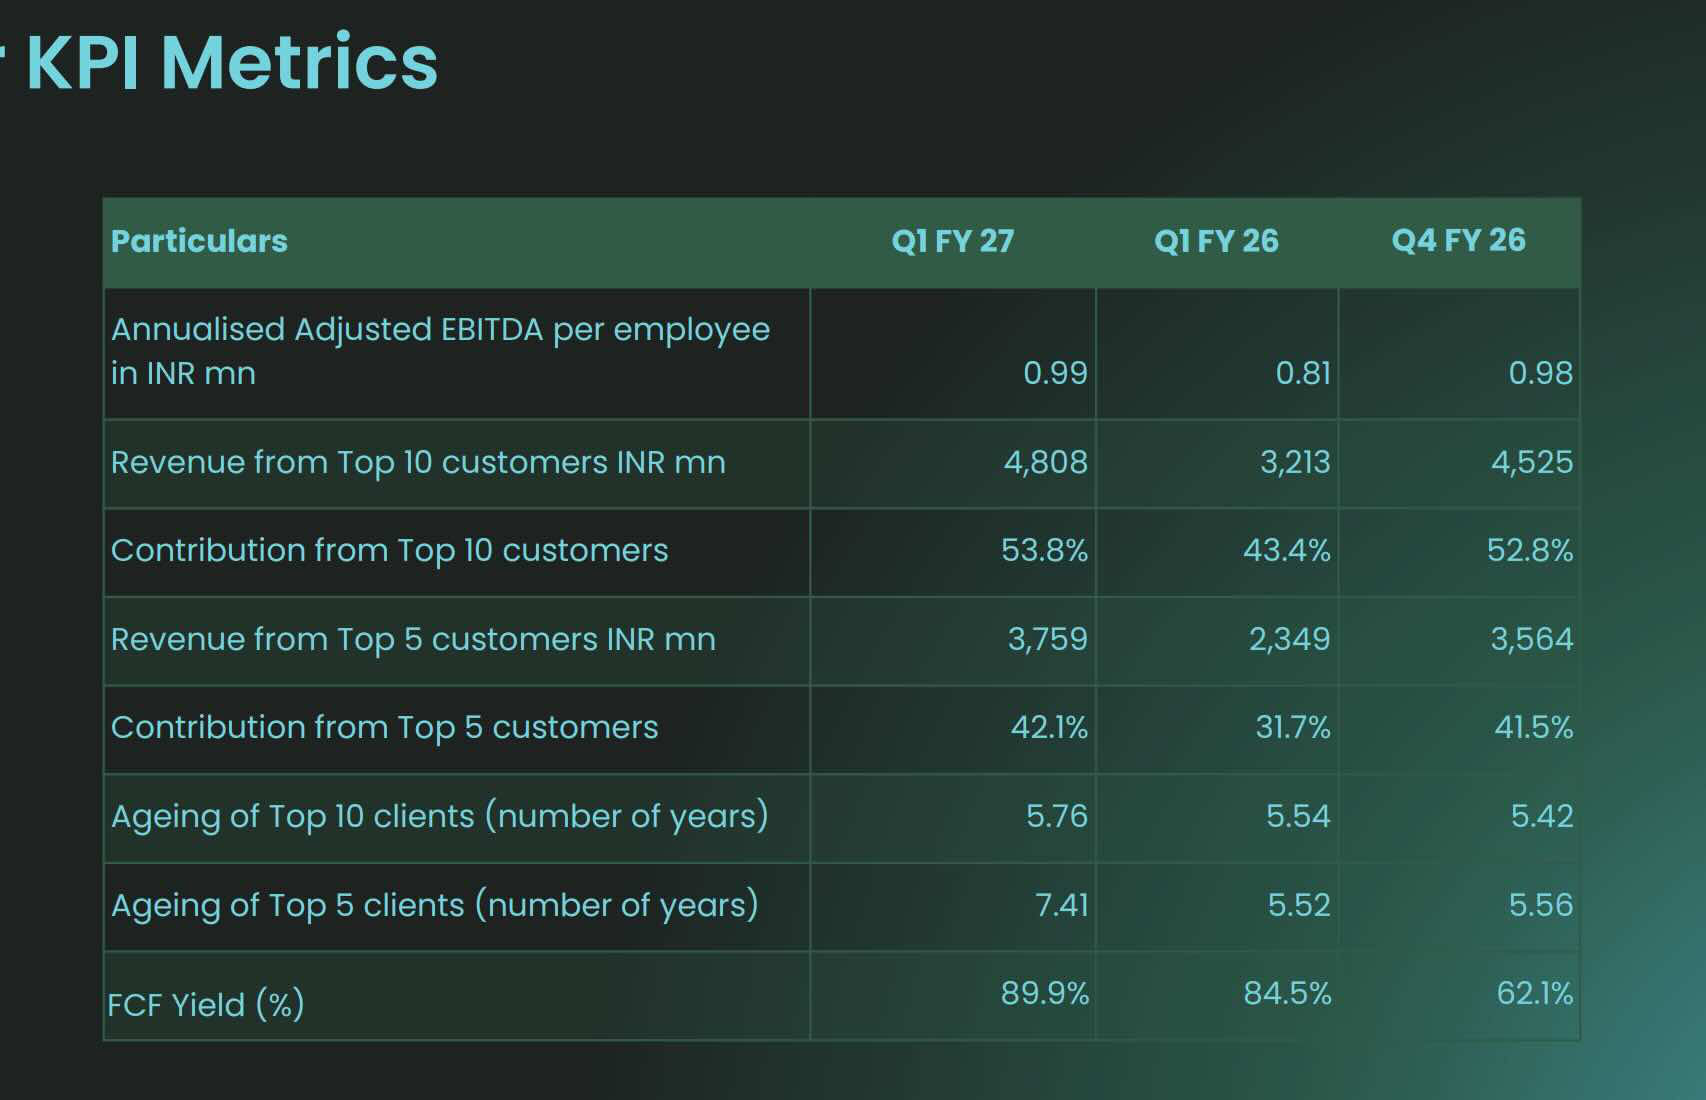
There is already some evidence that productivity is moving in the right direction. Adjusted EBITDA per employee increased from INR0.53 million in Q1 FY25 to INR0.99 million in Q1 FY27. The question now is whether IKS can carry that productivity advantage into the much larger business created by TruBridge.
IKS is taking a near-term margin hit for a bigger prize
There is a cost to this transformation, and investors will see it in the margins before they see the benefits. IKS’s standalone business entered FY27 in good shape, with revenue growth of 19.9% in FY26 and an EBITDA margin of 34.2%, while Q1 FY27 revenue grew 20.7% YoY and EBITDA margin stood at 33%.
TruBridge will pull the combined margin down in the near term because it is a lower-margin business than IKS. Management expects the combined EBITDA margin to be around 26-27% initially, compared with the roughly 35% adjusted margin of IKS’s standalone business.
At first glance, that may look like a step backwards. But that is also the price IKS is paying to enter a much larger part of the hospital’s technology stack.
The company is effectively trading some near-term margin for access to more than 2,100 hospitals, their EHR systems and more than five million patient records that could help build healthcare-specific AI models. IKS plans to recover the lost margin through automation, offshore delivery, technology integration and cost synergies, with management expecting the combined margin to move back towards 30-36% over the next few years.
The next few quarters may therefore show some margin dilution, but the bigger question is whether IKS can turn that sacrifice into a larger and ultimately more profitable business. In other words, the near-term pain is the price of gaining a bigger customer base, deeper technology capabilities and the data needed to build its healthcare AI platform.
The next test is whether IKS can make TruBridge look more like IKS
This is where investors need to watch the numbers rather than the presentations. TruBridge’s annual revenue expectation has been revised to about US$300 million from the earlier US$340 million estimate, partly because of more conservative revenue recognition and the planned exit from lower-margin information technology services. However, the annual EBITDA expectation remains around US$68 million, according to the post-acquisition commentary.
In other words, the company has already told investors that the revenue number is not the entire story. The real objective is to improve the quality of that revenue and eventually make the combined business more productive.
IKS has several ways to do this. It can sell its existing RCM and workflow products to TruBridge’s hospital customers, offer TruBridge’s EHR capabilities to its own customers and use the combined platform to introduce more automation.
The company is already pursuing a land-and-expand approach, with recent wins including an expansion with Advocate Health, a partnership with a large California health system and an extension of RCM services with existing customer StrideCare.
The key opportunity is cross-selling across two large installed customer bases, allowing IKS to grow without having to build every relationship from scratch.
The payoff, if the strategy works, could be substantial. IKS has retained its target of reaching INR3,000 crore of EBITDA by FY30, up 3x from 1,082 crore in FY26. This implies that the company expects the combined business to become much larger while recovering much of the margin lost during the initial integration.
That target is important because it shows what management believes the TruBridge acquisition can ultimately become. The next few years will determine whether the company can turn that ambition into higher revenue, stronger productivity and eventually higher margins.
The balance sheet has paid for the ambition
There is, however, a price for making this pivot. Before TruBridge was consolidated, IKS had net debt of INR265 crore at June 30, 2026, against INR251 crore at March 31, 2026. Operating cash flow increased 20.5% YoY and free cash flow increased 26.9% YoY during Q1 FY27, after adjusting for a one-time INR143 crore upfront guarantee payment.
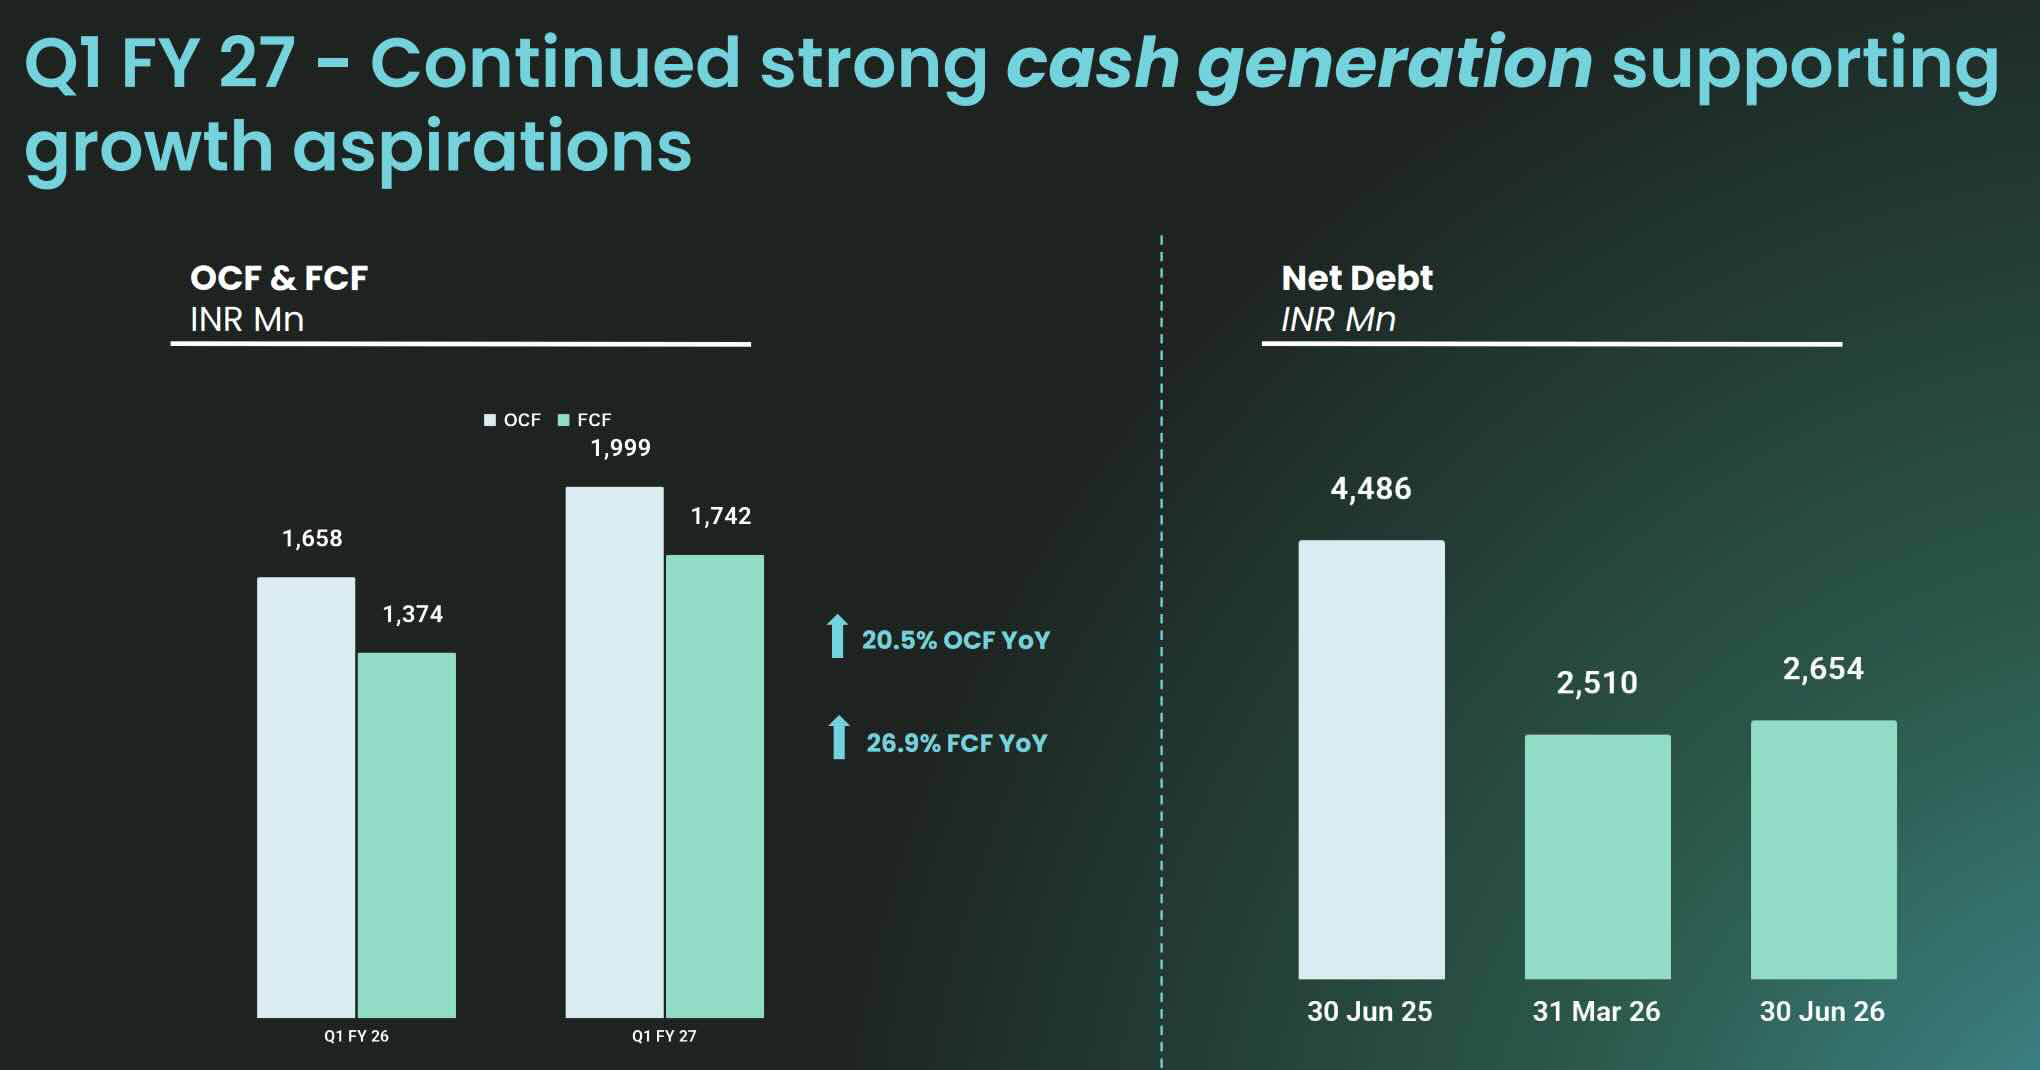
The acquisition adds significantly more debt to the picture. Management has said it expects to return leverage to pre-acquisition levels through strong cash generation, operating leverage and productivity gains, while keeping equity dilution minimal. It has also said that further acquisitions will be considered selectively, with the immediate priority being TruBridge.
This means the next few years have a simple financial equation. IKS needs to grow the combined business, improve its margins and generate enough cash to reduce debt.
If AI and automation deliver the productivity gains management expects, all three can happen together. If they do not, investors could be left with a larger company carrying more debt and a lower margin.
The market is not waiting for all of this to happen
There is another problem. The stock is already valued as a growth company. It is trading at a price-to-earnings ratio at about 44 times, while return on equity and return on capital employed remain high at roughly 40% and 37%, respectively.
The valuation is therefore not giving investors a cheap entry into a troubled acquisition story. They are paying for the possibility that IKS can make the acquisition work.
That is also why the next few quarters matter more than another quarter of 20% revenue growth. IKS has already shown that it can grow and maintain high margins. What it has not yet shown is that it can take a lower-margin acquired business, combine it with its own technology and turn the whole thing into a higher-margin healthcare platform.
IKS is betting that the hospital of the future will run on its software
The easy way to describe IKS is as another company benefiting from the rising cost of healthcare in the US.
The more interesting way is to look at what the company is trying to become. It started by taking administrative work away from doctors and hospitals. TruBridge now gives it a foothold in the software where the underlying healthcare information is recorded. Artificial intelligence then becomes the third layer, allowing IKS to automate more of the work that sits on top of that information.
That is a much bigger ambition than outsourcing. The company has retained its FY30 target of INR3,000 crore of EBITDA and management expects the combined business to move back towards its earlier margin range over time.
But there is a catch. IKS has to prove that the three pieces actually fit together. If they do, the company could have something difficult for a competitor to copy: the data, the software, the workflows and the healthcare expertise all sitting under one roof. If they do not, investors will discover that they paid a technology-platform valuation for what remains, at heart, a healthcare outsourcing company.
Disclaimer:
Note: We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Manvi Aggarwal has been tracking the stock markets for nearly two decades. She spent about eight years as a financial analyst at a value-style fund, managing money for international investors. That’s where she honed her expertise in deep-dive research, looking beyond the obvious to spot value where others didn’t. Now, she brings that same sharp eye to uncovering overlooked and misunderstood investment opportunities in Indian equities. As a columnist for LiveMint and Equitymaster, she breaks down complex financial trends into actionable insights for investors.
Disclosure: The writer and her dependents do not hold the stocks discussed in this article. The website managers, its employee(s) and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.