



Domination of Balance Sheets and Cash Yields
The Indian market has spent the last twelve months testing everyone’s patience. As of closing on 10th August 2026, the Sensex stood at 78,542, which is lower than where it was a year ago (80,604). Twelve months of holding, and the index has handed back a small loss.
In a tape like this, the old rules come back into fashion. Balance sheets matter more than stories. Cash paid into your bank account matters more than paper gains. And companies that can fund fat dividends without borrowing a single rupee start to look very different from the rest.
Two companies fit that description right now, and they could not be more different from each other. One is a Rs 1,04,234 cr banking software house that has paid out nearly all its profit, and sometimes more, for years. The other is a Rs 3,289 cr education platform that listed just last year and has already started writing dividend cheques. Let us dive in.
#1 Oracle Financial Services Software: Rs 400 Dividend Per Share Cash Machine
Incorporated in 1989 and based in Mumbai, Oracle Financial Services Software, or OFSS, builds the plumbing that runs banks. Its FLEXCUBE suite and related products handle core banking, payments, treasury and lending for financial institutions across the world.
With a market cap of Rs 1,04,234 cr, the company is a subsidiary of Oracle, which explains both the parentage premium and the product depth. Product licenses and related activities brought in 91% of revenue in the September 2025 quarter, making this a software products business first and a services business a distant second.
Oracle’s Product Engine Hits 60% Margins
That product-heavy mix is exactly what showed up in the June 2026 quarter, and in some style. Sales for Q1FY27 came in at Rs 3,125 cr, up 69% over the same quarter last year. Net profit more than doubled to Rs 1,416 cr, a jump of 121%. Operating margin hit 60%.
Join now
The trigger was a surge in license revenue, which rose 75% to Rs 2,936 cr, helped by a large deal where one of the biggest vacation ownership companies in the US signed up for the firm’s lending and leasing cloud software.
Strip out the fireworks, and the longer arc is steadier. This is a mature business that grows in single digits and converts almost everything into cash.
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5Y CAGR |
| Sales (Rs cr) | 4,984 | 5,221 | 5,698 | 6,373 | 6,847 | 7,672 | 9% |
| EBITDA (Rs cr) | 2,469 | 2,499 | 2,471 | 2,782 | 3,076 | 3,477 | 7% |
| Net Profit (Rs cr) | 1,762 | 1,889 | 1,806 | 2,219 | 2,380 | 2,639 | 8% |
EBITDA refers to operating profit before other income. The trailing twelve months tell you how much the June quarter changed the picture. TTM sales stand at Rs 8,945 cr, operating profit at Rs 4,508 cr and net profit at Rs 3,413 cr. That is a 29% jump in TTM sales and a 42% jump in TTM profit, on a base that had crawled at 9% a year for five years.
Payout Ratios Above 100%: The Dividend Mechanics
For FY26, the company paid two interim dividends, Rs 130 in November 2025 and Rs 270 with a record date of 7th May 2026. That is Rs 400 per share for the year, which works out to a payout of 132% of the year’s earnings. The current dividend yield stands at 3.4%. The industry average is a flat zero.
It must also be noted that FY26 was not a one-off act of generosity. The payout ratio has hovered near or above 100% for years, at 98% in FY21, 87% in FY22, 108% in FY23, 94% in FY24 and 97% in FY25. The company simply does not hoard cash it cannot use.
It can afford to. Borrowings stood at just Rs 32 cr as of March 2026, against reserves of Rs 7,783 cr. Free cash flow for FY26 was Rs 2,587 cr. ROCE for FY26 came in at 45.3% and ROE at 32.6%, numbers that most of the listed IT pack can only admire from a distance.
Behind the 88% Six-Month Surge
The market has noticed all this. The share price of Oracle Financial Services closed at Rs 11,890 on 11th August 2026, which is 157% higher than the 5-year-old price of around Rs 4,620 from August 2021.
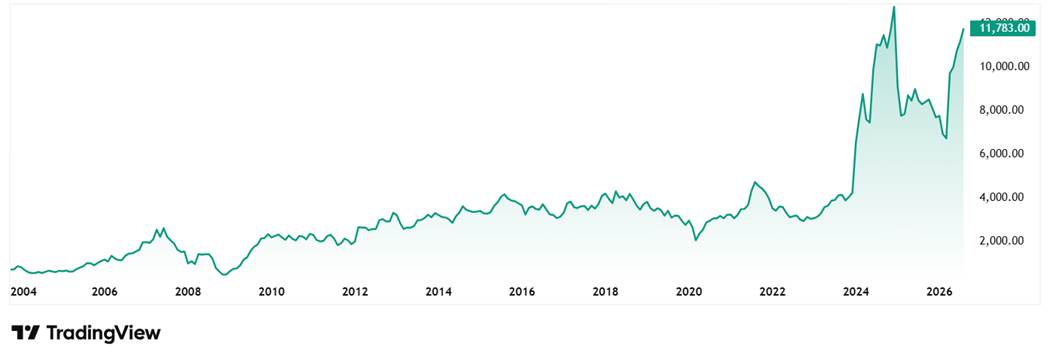
In just the last 6 months, the stock has jumped by 88% from Rs 6,300 to Rs 11,890. This run has come in a year when the broader IT index has been one of the worst performing pockets of the market, with the Nifty IT index down about 24% so far in 2026.
At current levels the stock trades at a PE of about 31x and the industry median is 33x. The 10-year median PE for the company is 23x while the industry median for the same period is 26x.
Promoter holding was steady at 72.41% as of June 2026. FII holding jumped from 8.04% in March 2026 to 9.70% in June 2026, the sharpest quarterly rise in over a year. Foreign money moved in just as the big quarter landed.
Peak Valuations and Leadership Transitions
Three things deserve to be looked at with caution. First, license revenue is lumpy by nature, and a 60% margin quarter sets a high bar for the rest of FY27. Second, the corner office changed hands in July 2026, with long-serving CEO Makarand Padalkar stepping down and CFO Avadhut Ketkar taking over as MD and CEO from 24th July. Third, the company had to formally deny a media report on 23rd July 2026 that suggested Oracle was looking to sell its stake.
The denial was clear, but the episode shows how sensitive the stock is to any noise around its parentage. And a payout above 100% of earnings, however welcome, cannot rise forever.
#2 Crizac: 4.26% yield, 52% ROCE
Incorporated in 2011, Crizac runs a B2B platform that connects student recruitment agents with universities in the UK, Canada, Ireland, Australia and New Zealand. Think of it as a wholesale marketplace for international admissions. Universities pay Crizac a commission for every student who enrols through its network, and Crizac shares a slice with the counselling agents who bring the students in. The company listed on the exchanges in July 2025.
With a current market cap of Rs 3,268 cr, the model of the company is asset light in the extreme. There are no campuses to build and no loans to write. Borrowings stood at just Rs 2 cr as of March 2026, and the company reported net cash of about Rs 570 cr in its June 2026 quarter update.
Unpacking the 52% ROCE Math
Time to look at the figures for the last few years to see math behind the impressive numbers.
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5Y CAGR |
| Sales (Rs cr) | 111 | 264 | 473 | 530 | 849 | 1,042 | 56% |
| EBITDA (Rs cr) | 27 | 89 | 107 | 145 | 213 | 286 | 60% |
| Net Profit (Rs cr) | 21 | 68 | 112 | 116 | 153 | 219 | 60% |
EBITDA refers to operating profit before other income. Sales have grown almost tenfold in five years, from Rs 111 cr in FY21 to Rs 1,042 cr in FY26. Profit has compounded at 60% a year over the same stretch. ROCE currently stands at 52% and ROE at 40%. These are the kind of return ratios that usually belong to royalty businesses, not recent listings.
Look past the top line, though, and the engine still runs. Net profit for the quarter rose to Rs 46 cr. Student enrolments, the metric the company actually gets paid on, grew 15% to 4,751. The company’s share of UK study visas granted has climbed from 3.5% in FY24 to 6% in FY26, so it is gaining share even as the pond shrinks. And it has started buying its way into new geographies, acquiring 100% of Inova Consultancy and investing in ForeignAdmits to push into Europe, Mexico and education financing.
The 4.3% Yield Catch: Why the Stock Has Corrected
In January 2026, the board approved an interim dividend of Rs 8 per share for FY26. Against earnings of Rs 12.52 per share, that is a payout of 64%. The current dividend yield works out to 4.3%, while the industry average is 0.8%. Management has gone further and committed to paying out at least 40% of annual profit as dividends for the next three years.
Now for the catch, and it is one every reader should sit with. Part of that juicy yield exists because the stock has fallen hard. The share price of Crizac is down about 39% over the past year since listing in July 2025 and trades at less than half its 52-week high of Rs 388. The stock is currently trading at PE of 15x while the industry median is 21x.
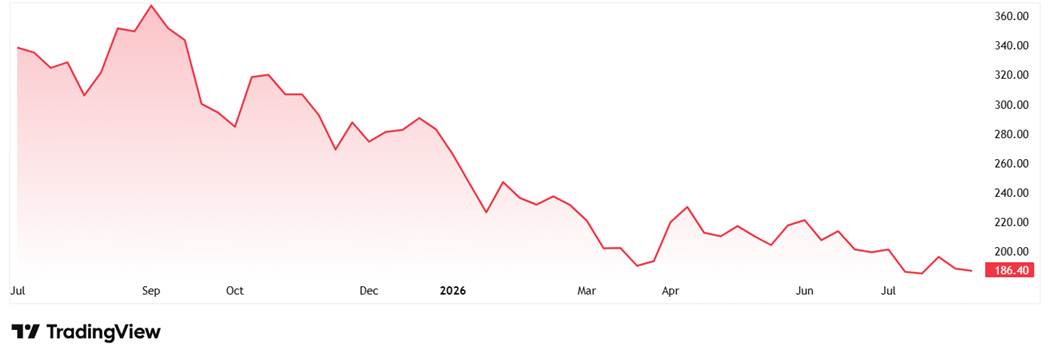
A high yield born of a falling price is a warning as much as an invitation, so the fall deserves an explanation.
Over-Reliance on a Single Geography
The June 2026 quarter gives the answer in miniature. Revenue slipped 4% year on year to Rs 201 cr, and management guided for flat revenue in FY27. The UK accounted for roughly 98.7% of quarterly revenue, which makes the business a near pure play on one country’s student visa policy. Flight disruptions between February and June 2026 hurt the April to June intakes, and the September quarter is expected to feel the same drag.
The shareholding pattern shows who blinked. FII holding has slid from 3% in June 2025 to 1.6% in June 2026, while public shareholding has climbed to 15.22%. Promoters have not sold a share, holding firm at 79.94% since listing.
The bear case writes itself. One country supplies nearly all the revenue. Student visa policy in the UK can turn on a single election or white paper. The dividend record is exactly one year old. And the listed history is too short to know how the stock behaves through a full cycle. The 40% payout commitment softens some of this, but it is a promise from a young company, not a decade of habit.
Patience Pays When the Market Stalls?
While the core story might look the same with high dividends and near zero debt, these are not similar stories. Oracle Financial Services is the finished article, a mature cash machine near its all-time high, paying out more than it earns because it has nowhere better to put the money. Crizac is the unfinished one, a 52% ROCE business at 15 times earnings, marked down 39% because it’s one big market caught a cold.
What they share is the trait that matters most when the index goes sideways. Neither owes anyone money, both generate far more cash than they need, and both have chosen to hand a meaningful chunk of it back to shareholders. In a market that has returned less than nothing over twelve months, getting paid 3.4% to 4.3% in cash to hold a debt free business is not a small thing.
Both names belong on a watchlist, with the next few quarters as the test.
Disclaimer:
Note: We have relied on data from http://www.Screener.in and http://www.trendlyne.com throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Suhel Khan has been a passionate follower of the markets for over a decade. During this period, he was an integral part of a leading Equity Research organisation based in Mumbai as the Head of Sales & Marketing. Presently, he is spending most of his time dissecting the investments and strategies of the Super Investors of India.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article. The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein.