



India’s Contract Development and Manufacturing Organization (CDMO) sector is transforming into a core pillar of the global life sciences supply chain.
Driven by global supply chain diversification (“China Plus One”), competitive operational costs, and world-class, USFDA-compliant manufacturing facilities, Indian firms are capturing high-value research and complex manufacturing contracts from multinational pharmaceutical giants.
The broader sector is rapidly advancing up the value chain. Companies are shifting focus from basic Active Pharmaceutical Ingredients (APIs) to higher-margin offerings like custom synthesis, high-potency active pharmaceutical ingredients (HPAPIs), biologics, and antibody-drug conjugates (ADCs).
Against this backdrop, here are 3 Pharma CDMO stocks to watch.
#1 Laurus Labs
First on the list is Laurus Labs. The company is a top player in the CDMO space, with integrated capabilities across API and formulation development and manufacturing services, as well as CMO supply. Its therapy focus includes areas like ARV, Oncology, Cardio, Diabetic, Gastro, CNS, Asthma, and Ophthalmic.
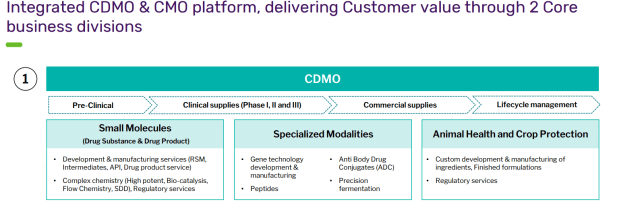
Source: Investor Presentation
According to management, the company has continued to deliver significant value through expanded applications and capabilities, especially in its enzymatic and biocatalysis platform across various clinical phases, further deepening long-term customer partnerships.
The company is also expanding rapidly. Laurus has continued to invest in capacity creation at its Vizag site and is also advancing commercial-scale peptide capacity based on customer demand.
Construction of the commercial-scale fermentation facility and strengthening of its downstream processing infrastructure are progressing in line with the plan, and management expects Phase 1 of this capacity, a little over 400 kiloliters, to be operational towards the end of this year.
Financial Highlights of Laurus Labs
| Rs m | FY24 | FY25 | FY26 |
| Revenues | 50,408 | 55,540 | 68,129 |
| Operating Profit | 8,038 | 11,304 | 18,327 |
| Net Profit Margin (%) | 3.3 | 6.4 | 13.1 |
| Profit After Tax | 1,682 | 3,544 | 8,899 |
Source: Equitymaster
Moving on to financial results. Laurus maintained its strong growth momentum, delivering the highest quarterly revenue, EBITDA, and profits during the first quarter of FY27.
The company’s revenues were Rs 20.26 billion (bn), up 29%. This was mainly driven by the growing contribution of commercial supplies in the CDMO segment and continued strength in the affordable medicine portfolio. Gross margins were also very healthy, remaining around 62.7%, and EBITDA margins expanded by 7 percentage points from the previous quarter to 31.8%.
The product mix across business divisions and operating leverage continued to perform well, supporting healthy margins overall.
#2 Divi’s Labs
Next on the list is Divi’s Labs.
Divi’s manufactures Generic APIs, Intermediates, and Nutraceutical Ingredients, and offers Custom Synthesis of APIs to Big Pharma, providing a competitive advantage throughout the entire product lifecycle.
This year marks 20 years of Divi’s in the nutraceutical segment – a journey that began with just two products has grown into a portfolio of over 100 offerings across human health, animal health and dietary supplements in multiple forms today.
Management says that, looking ahead, they are actively expanding both capabilities and capacity to meet the demand of a rapidly evolving global market. Within Custom Synthesis, projects are actively continued across a diverse portfolio of customer programs covering multiple therapeutic areas and stages of development.
The company is also supporting customers across clinical development, validation, and commercial supply preparations, with manufacturing activities aligned to individual regulatory and filing requirements.
Likewise, the company’s three major capex programmes are nearing completion and validations are going on. Management says that as the projects progress, it remains focused on timely execution while continuing to build the infrastructure and technical capabilities required to support future commercial requirements.
Financial Highlights of Divi’s Labs
| Rs m | FY24 | FY25 | FY26 |
| Revenues | 78,450 | 93,600 | 105,600 |
| Operating Profit | 25,450 | 33,210 | 39,490 |
| Net Profit Margin (%) | 20.4 | 23.4 | 24.3 |
| Profit After Tax | 16,000 | 21,910 | 25,680 |
Source: Equitymaster
For the first quarter of FY27, Divi’s reported consolidated total income of Rs 31.44 bn, up from Rs 25.29 bn in the corresponding quarter of the previous financial year.
Profit before tax rose to Rs 11.80 bn from Rs 7.33 bn in the corresponding quarter last year, while profit after tax stood at Rs 9.02 bn versus Rs 5.45 bn in the same period the previous year.
#3 Akums Drugs and Pharma
Next on the list is Akums Drugs and Pharma.
Akums Drugs & Pharmaceuticals Limited is India’s largest contract development and manufacturing organization (CDMO) for pharmaceutical formulations.
The company manufactures a vast portfolio of oral solids (tablets, capsules), liquid orals, injectables (vials, ampoules, dry powder), blow-filled seals, eye drops, and topical preparations.
Over the years, the company has steadily grown its business.
In July, Akums announced the acquisition of Oriflame India’s manufacturing business. The transaction covers two manufacturing facilities, one at Roorkee, Uttarakhand, and the other at Noida, Uttar Pradesh, along with a leased warehouse situated at Noida, Uttar Pradesh.
With the acquisition, Akums expands its manufacturing footprint in skin care cosmetics and wellness products. Management says this aligns with its strategy of tapping niche formulations to strengthen its position with existing and prospective clients and improve margins.
Financial Highlights of Akums Drugs and Pharma
| Rs m | FY24 | FY25 | FY26 |
| Revenues | 41,782 | 41,182 | 43,590 |
| Operating Profit | 1,570 | 5,166 | 6,507 |
| Net Profit Margin (%) | 0.00 | 8.3 | 5.9 |
| Profit After Tax | 8 | 3,438 | 2,564 |
Source: Equitymaster
On the financial front, Akums registered healthy revenue growth of over 13% in Q1FY27, with EBITDA increasing by more than 30%.
The CDMO segment primarily led the growth, driven by double-digit volume growth and higher API prices. Management says the CDMO segment’s consistent performance reflects a healthy demand environment and clients’ trust in Akums as their preferred manufacturing partner. Marketing segments, domestic and exports, saw muted quarterly performance, with multiple initiatives underway.
The company remains confident these segments will return to a growth path in the coming quarters. Management believes Akums is well placed to deliver robust operating performance in FY27.
Conclusion
India’s CDMO sector presents a compelling long-term story driven by global supply diversification and high-margin manufacturing capabilities. However, sector tailwinds alone do not guarantee sustained investor returns. Before investing in any CDMO business, evaluate fundamental parameters like debt levels, return ratios (ROCE/ROE), regulatory audit track records, and valuation multiples. Ensure the company possesses strong client retention, scalable infrastructure, and sound earnings quality to navigate potential supply chain or regulatory headwinds effectively.
Disclaimer: This article is for information purposes only. It is not a stock recommendation and should not be treated as such. Learn more about our recommendation services here…
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.