



The quick commerce sector is changing rapidly in India, and there will inevitably be winners and losers in this brutal competition. Eternal Limited, the company that owns Blinkit, is the market leader in this business and, despite its massive size, so far, it has been able to show a better growth trajectory than some other key players.
In the recent quarterly earnings, Eternal’s quick commerce segment reported Rs 15,664 crore revenue, representing 18.4% QoQ growth. In terms of Net Order Value (NOV), Eternal’s quick commerce segment reported NOV of Rs 17,132 crore in the recent quarter, up from Rs 14,386 crore in Q4 2026. This is 19.08% QoQ growth.
On the other hand, Eternal’s main rival, Swiggy Limited, has reported slower growth in its quick commerce business, Instamart. Instamart reported Gross Order Value(GOV) of Rs 7,907 crore in the recent quarter compared to Rs 7,881 crore in Q4 2026. Swiggy’s Instamart has shown a modest QoQ growth of 0.2% in GOV compared to a massive 19.08% QoQ growth in NOV by Eternal’s quick commerce business.
Eternal vs Swiggy comparison (Quick Commerce Segment)
| Particulars | Eternal’s Blinkit | Swiggy’s Instamart |
| Q1 FY27 | Rs 17,132 cr (Net order value) | Rs 7,907 cr (Gross order value) |
| YoY growth in NOV | 86% | 39.8% |
| QoQ growth in NOV | 19.02% | 0.2% |
| Adjusted EBITDA | Rs 102 cr profit | (Rs 778 cr) loss |
| Contribution margin | 5.3% of NOV | -0.2% of GOV |
| Dark store footprint | 2,443 stores | 1,171 stores |
| Geographic reach | Focused on dense metro clusters | Expanded across 131 cities |
There are three main reasons why Eternal could potentially deliver strong returns over the next 5 years despite increasing competition.
#1 Massive moat in terms of warehouse density
Eternal added another 200 dark stores in the recent quarter to take its total count to 2,443. This is 8.9% QoQ growth in dark stores. Investors should note that the QoQ growth in NOV was 19.08%, which is significantly higher than the dark store count growth. Hence, Eternal’s quick commerce is able to show a higher organic revenue growth from the same stores, which is a sign of higher order value and more frequent purchases by customers.
Swiggy added 28 net dark stores to take the total count to 1,171 stores. The QoQ growth in dark stores was only 2.5%. On the other hand, Swiggy’s NOV had a modest 0.2% QoQ growth. Hence, the per-store NOV for Swiggy actually declined in the recent quarter, which can be a headwind for future growth.
Join now
By the end of 2026, Eternal could reach a store count of close to 3,000. This massive infrastructure is not easy to replicate, especially as the cost of commercial rent increases. Even players with deep pockets like Amazon India and Reliance Retail will find it difficult to reach anywhere close to this presence. The recent data shows Reliance Retail has 600 dark stores.
Eternal’s strategy is to saturate the pin codes where it operates with its dark stores, which allows for faster order fulfillment. As of the end of calendar year 2024, Eternal operated 1,007 dark stores according to filings. This has increased to 2.5X in 18 months according to recent quarterly filings.
If Eternal reaches its 3,000 dark store target by the end of calendar year 2026, it would have shown 3X growth in 2 years in terms of store count. This creates a flywheel effect where higher warehouse density helps in faster delivery, which improves the transaction number and transaction value from customers.
Dark store rentals have increased over the last few quarters. Future players will face a massive challenge in expanding their warehouse presence in this saturated sector.
#2 Economies of scale with more efficient fulfillment
A higher warehouse density allows Eternal to fulfill orders quickly. This gives the company a big edge over competitors who would need to fight on other factors like pricing, promotions, etc. The supply chain efficiency is a factor which investors should closely review. The last-mile delivery is one of the biggest expenses in this sector. The ability to reduce the delivery time by a few minutes due to higher warehouse density is a massive edge for Eternal.
We can already see this difference in adjusted Earnings before interest, tax, depreciation and amortisation (EBITDA) of Eternal’s quick commerce compared to Swiggy’s Instamart. In the recent quarter, Eternal’s quick commerce segment reported adjusted EBITDA of Rs 102 crore compared to a Rs 780 crore loss shown by Swiggy’s Instamart. This is despite a much higher QoQ growth in NOV by Eternal compared to Swiggy, as mentioned above.
#3 Sector tailwinds and consolidation of industry
The third main reason which can help Eternal stock deliver strong performance in the next five years is the changing dynamics within this sector. The quick commerce segment still makes up a small sliver of the total retail market base in India.
According to estimates by IBEF, the retail market could soon reach $1 trillion or Rs 1,00,00,000 crore. In comparison, Eternal’s recent quarterly NOV was Rs 17,132 crore. On an annualized basis, Eternal’s NOV is less than 1% of the retail market base in India. This gives the company a long growth runway over the next few years.
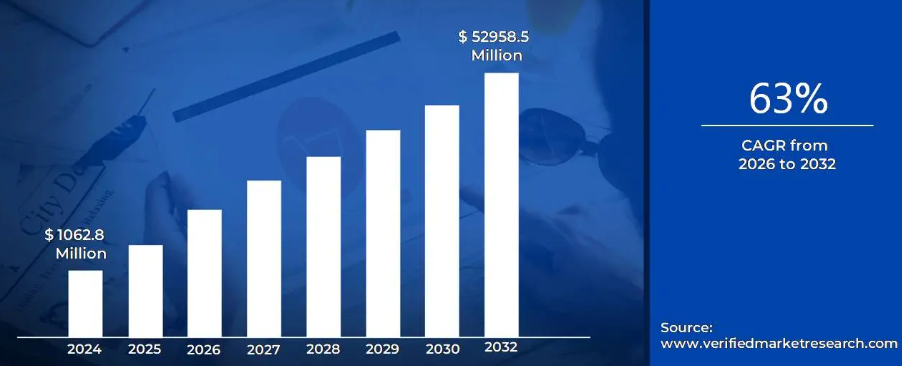
Another report by Verified Market Research shows that the quick commerce sector could deliver 63% CAGR from 2026 to 2032. Eternal, being a key player, could likely show a strong revenue CAGR also.
Another major dynamic in the quick commerce business is the possibility of consolidation. In most digital businesses, there is a strong trend towards consolidation of market share among the top 3-4 players. We have seen how Uber, Ola and Rapido have cornered a big chunk of the ride-hailing market.
Similarly, in the food delivery business, Zomato and Swiggy have built a duopoly. In China, the quick commerce business is dominated by three players, including Meituan, Alibaba’s Ele.me and JD.
It is likely that some of the loss-making players in India’s quick commerce business will get absorbed by bigger companies in the next few years. This should reduce the competitive headwind faced by Eternal and also allow the company to show a better margin and earnings trajectory.
Now, let’s dig deeper into the financial performance of Eternal and its main rival, Swiggy.
#1 Eternal Limited
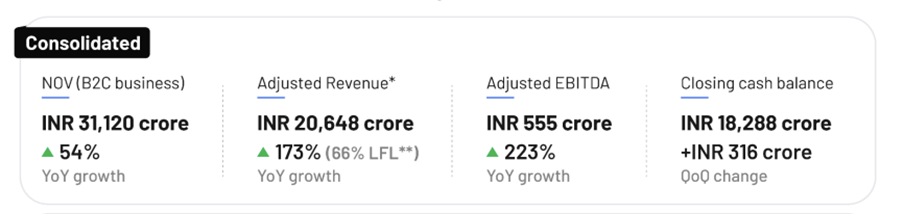
Eternal reported consolidated net order value of Rs 31,120 crore in the recent quarter, which was a 54% YoY growth. Most of this growth came from quick commerce, which showed 86% YoY growth in NOV. The like-for-like (LFL) adjusted revenue grew by 66% YoY. Adjusted EBITDA was Rs 555 crore which was equal to 223% YoY growth. Closing cash balance was Rs 18,288 crore, increasing by Rs 316 crore from the previous quarter.
Larger and more efficient stores
The capex per store is Rs 2.5 crore compared to Rs 1 crore a year ago. This is due to a larger store size and more technology investments. NOV has increased to Rs 11 lakh per store per day from Rs 7 lakh. Again, this reflects the larger store sizes. The adjusted EBITDA margin is 6%, which is close to the higher end of the earlier estimate of 5%-6%.
The profit after tax in the recent quarter was Rs 92 crore compared to Rs 25 crore in the year-ago period. This is a dip from Rs 174 crore in Q4 FY26. This is largely due to higher D&A expense, ESOP expense, and a bigger tax bill of Rs 180 crore in the recent quarter compared to only Rs 54 crore in the previous quarter.
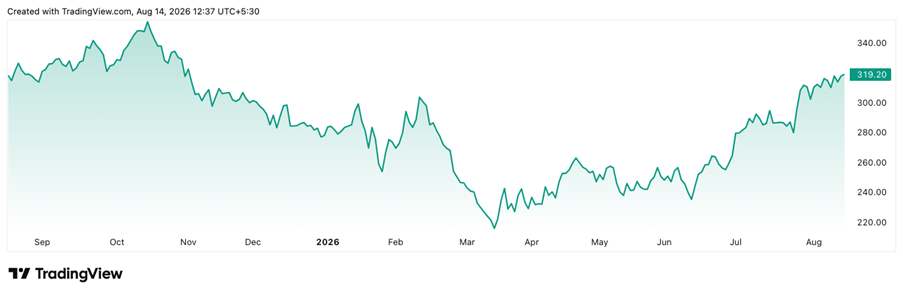
1-year price chart of Eternal Limited
#2 Swiggy Limited
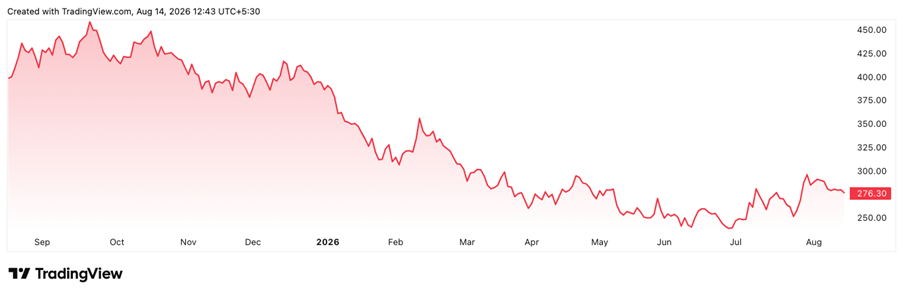
Swiggy’s overall revenue grew 34% YoY to Rs 7,112 cr (+6.7% QoQ). Instamart GOV grew 39.8% YoY to Rs 7,907 cr and QoQ growth was 0.2%. On the positive side, Instamart’s contribution margin improved 440 bps YoY to -0.2%.
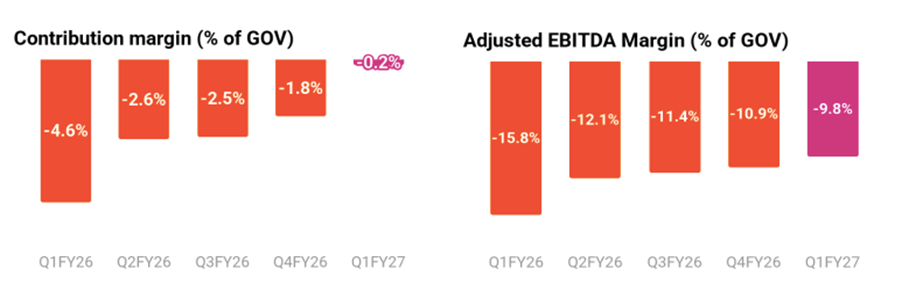
Platform’s Monthly Transacting Users (MTU) grew 27.4% YoY to 27.5 million. Consolidated adjusted EBITDA was Rs -651 cr, which was a YoY improvement of Rs 162 cr.
1-year price chart of Swiggy
Facing tough competition and slower growth in quick commerce
Swiggy’s quick commerce business faces tough competition as it competes with market leader Eternal. It has a lower warehouse density, and the QoQ growth in new stores is also quite low. This can hurt the long-term growth runway of Swiggy in this segment. The company has improved the margins in the quick commerce business, and the contribution margin turned positive from May 2026. However, it will need to ramp up the growth numbers in the next few quarters to stay in this race.
Eternal vs Swiggy: An Overall Comparison
| Metric | Eternal* | Swiggy* |
| Revenue Growth | NOV +54% YoY | Revenue +34% YoY |
| Quick Commerce | +86% YoY | Instamart GOV +40% YoY |
| EBITDA | ₹555 cr | -₹651 cr |
| PAT | ₹92 cr | Loss-making |
| Cash Balance | ₹18,288 cr | NA |
| Key Takeaway | Strong growth and profitability | Improving margins, but growth trails Eternal |
* Includes all businesses including quick commerce, and food delivery.
Peer analysis
When we look at the comparison of Eternal and Swiggy, we see that their EV-to-EBITDA ratios are quite high compared to the industry median. Eternal’s EV to EBITDA ratio is 100, and Swiggy is -32.55. The industry median is 12.81. However, Eternal’s YoY and QoQ growth trajectory is much higher than other peers. Investors should also look at the future margin expansion potential over the next few quarters, which should improve the EBITDA metric significantly.
The Return on Capital Employed (ROCE) of Eternal is 2.48%, and ROE is 0.38%, which is similar to the industry median. Swiggy is again negative in both these metrics due to its losses.
| Peer comparison | |||
| Company | EV/EBITDA | Return ratios (%) | |
| Company | ROCE (%) | ROE (%) | |
| Eternal Limited | 100.34 | 2.48 | 0.38 |
| Swiggy | -32.55 | -24.08 | -29.07 |
| Industry Median | 12.81 | 2.48 | 0.38 |
To conclude, Eternal Limited is showing strong QoQ growth in NOV as well as an increase in dark stores. This should help the company improve warehouse density, build supply chain efficiency, and gain greater economies of scale. The quick commerce retail share is still a small fraction of the overall retail market, which gives it a long growth runway over the next few years.
==============
Disclaimer
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation. Only in cases where the data was unavailable have we used an alternative, widely used, and accepted source of information
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
About the Author: Rohit is a seasoned financial writer with over a decade of experience covering Indian and international stocks. He specializes in converting complex financial data into actionable insights that can help readers make better calls. He covers macroeconomic trends globally, which gives a better analysis of the growth runway for companies in key sectors.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities, or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources, and only after consulting such independent advisors as may be necessary.