



Growth demands capital. A company that sells more usually needs to carry more inventory, give customers more time to pay, and invest more cash into its operations. That means growth can often consume cash even when the underlying business is profitable.
But some businesses turn this equation on its head. They collect money from customers faster than they have to pay their suppliers, leaving them with a negative working capital cycle. In such businesses, growth does not necessarily require the company to keep putting more of its own money into the business. Instead, the cash generated through the operating cycle can help fund expansion.
This can be a powerful advantage. A company that can grow when the Working Capital is negative perhaps has greater potential to generate cash as it scales, which in turn can improve capital efficiency and reduce its dependence on external funding. The more durable this characteristic is, the more interesting it becomes from an investment perspective.
But negative working capital on its own is not enough. It can sometimes reflect a temporary balance-sheet movement, weak collections or the peculiarities of a particular business. The important question is whether the negative cycle is structural and sits alongside a profitable, capital-efficient and growing business.
With that in mind, we focused on three such companies where working capital days are below zero but above -300 days, and where the three-year average working capital days also remains negative. So this phenomenon is not a one-off. It is a pattern in the companies. We further limited the universe to companies with a market capitalisation above Rs 5,000 crore, positive net profit, and Return on Capital Employed (ROCE) above 15%. To ensure that receivables were not undermining the cash-cycle advantage, we also required current debtor days to be below the three-year average.
#1 WeWork India: Scaling up as flexible workspaces gain ground
WeWork India Management Ltd. operates flexible workspaces across India’s major business centres, offering private offices, managed offices and other workspace-related services. The company ended Q1FY27 with 79 centres across eight cities, 9.1 million square feet (sq. ft.) of operational space and around 1,33,600 desks. Its member base stood at about 1,13,000, up by around 30% from the previous year.
What makes WeWork India relevant to the broader capital-efficiency theme is its unusually negative working capital cycle. Working capital days stood at -189 days in FY26, compared with -185 days in FY25 and -207 days in FY24. At the same time, debtor days have steadily fallen from 19 days in FY23 to 13 days in FY26.
This is significant because the negative working capital position has persisted even as the company has scaled its business.
Revenue surged from Rs 1,315 crore in FY23 to Rs 2,440 crore in FY26, while operating cash flow increased from Rs 942 crore to Rs 1,734 crore over the same period. Free cash flow (FCF) stood at Rs 1,137 crore in FY26. Up from Rs 709 crore in FY23.
However, WeWork’s negative working capital should not be interpreted as a simple case of suppliers financing its growth. The business has substantial lease-related obligations, and its expansion involves upfront investment in new centres. This distinction will be important when comparing it with companies in the list whose business models generate an even cleaner working capital advantage.
Expansion Backed By Rising Demand
The growth is being supported by rising demand for flexible office space. In the April-June 2026 quarter, portfolio occupancy increased to 84.9% from 76.5% a year earlier, while members grew faster than capacity.
Management expects the expansion to continue. By March 2027, it expects to have around 10.3 million sq. ft. and 155,000 desks operational, while FY28 and FY29 supply is already being negotiated. The company has also indicated that its FY27 pipeline is largely locked in.
The growing demand also reflects in the growing business revenue, as the same rose 28.5% YoY to Rs 698 crore during Q1FY27, with core workspace revenue increasing nearly 30%. However, the company incurred losses of Rs 4.2 crore during the quarter, compared to losses of Rs 14.1 crore a year back.
Contracted revenue provides visibility.
The more interesting part of the expansion story is the relationship between committed revenue and committed costs. WeWork India ended Q1 with Rs 3,363 crore of locked-in revenue, up 60% from Rs 2,105 crore a year earlier. Locked-in rent obligations increased by 30% over the same period. Management said that for every Rs 1 of new rent committed, the company added nearly Rs 4.7 of contracted revenue.
The company is also seeing stronger absorption at newer centres. Occupancy at centres that were less than 12 months old improved to 65% from 45% a year earlier. Portfolio break-even occupancy was 56.6%, suggesting that newer locations are reaching operating profitability faster as the network expands.
That could become increasingly important as the company adds capacity. Management expects another roughly 20,000 seats to open by October, including around 7,000 managed-office seats.
Coming to the capex, the company expects FY27 capex to remain between Rs 500 crore and Rs 600 crore, although this could increase if large managed-office contracts require additional investment.
New services could add to asset-light growth
Beyond workspace, WeWork India is also looking to increase revenue from its existing member base. In July, it launched Member Services, a marketplace connecting members with business service providers across areas such as transport, IT, hiring, insurance and other corporate services. The company says the platform requires no significant asset or capex investment to scale.
Management expects these newer businesses to be incremental to earnings. For Member Services, the company currently earns listing fees and a take rate between 6% and 16%, depending on the service.
This gives WeWork India another potential growth lever without requiring the same level of physical investment as its core workspace business. The key question going ahead will be whether the company can maintain high occupancy and cash generation while adding centres at the pace planned.
Premium Valuation Reflects Growth Expectations
Shares of WeWork India are trading at a price-to-earnings (P/E) ratio of 105.7x, which is way higher than the industry median of 18.5x; also, its price-earnings to growth (PEG) ratio is 2.9x, while the industry median is 0.54x, indicating that the stock is relatively expensive even if adjusted for growth.
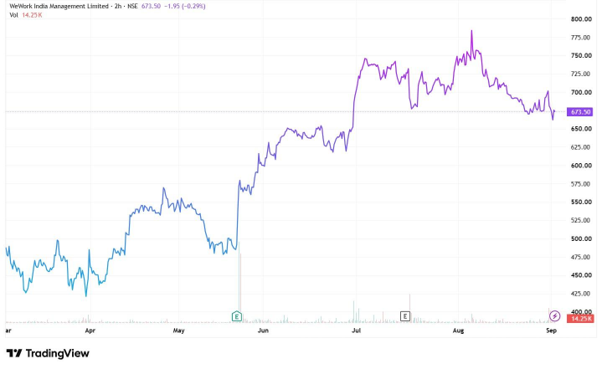
6-Month Share Price Chart of WeWork India Management Ltd.
#2 Bharti Hexacom: Negative working capital Supports Cash Generation
Bharti Hexacom Ltd. provides mobile services in Rajasthan and the Northeast, along with fixed-line and broadband services in Rajasthan. At the end of the April-June quarter, the company had a mobile customer base of 29 million, with 2,10,000 net additions during the quarter. Smartphone customer additions stood strong at 3,44,000, while Average Revenue Per User (ARPU) stood at Rs 259.
Bharti Hexacom’s working capital cycle stands out for its consistency. Working capital days stood at -171 days in FY26, compared with -215 days in FY25 and -281 days in FY24. The three-year average therefore remains deeply negative.
The company also has very little money tied up in receivables. Debtor days declined to four days in FY26, from five days in FY25 and 23 days in FY24. This has allowed the company to maintain a negative working capital position even as its business has expanded.
The cash-flow profile is consistent with this. Cash from Operating Activities (CFO) stood at Rs 4,464 crore in FY26, while FCF was Rs 3,026 crore. CFO was equivalent to 106% of operating profit.
Operating free cash generation, which management defines as Earnings Before Interest, Tax, Depreciation and Amortisation after leases (EBITDAaL) minus capex, was about Rs 830 crore in Q1FY27. Net debt excluding leases stood at around Rs 960 crore, with the ratio of net debt excluding leases to EBITDAaL at 0.2 times.
5G And Homes Offer The Next Growth Leg
Bharti Hexacom spent Rs 382 crore on capital expenditure (capex) during the quarter, primarily towards 5G densification, network modernisation and its Homes and Internet Protocol Television (IPTV) businesses. The company deployed 399 towers over the past year to strengthen coverage and improve customer experience.
The Homes business added 75,000 customers during the quarter, with revenue growing about 8% sequentially. Management sees significant headroom in the segment, but has become more selective about customer acquisition after finding that low-entry pricing in Fixed Wireless Access (FWA) had resulted in higher churn and weaker customer quality in some cohorts. The company is now focusing on fibre and deploying FWA more selectively where customer economics are stronger.
Management also sees room to increase investment in 5G densification and fibreisation while maintaining a comfortable balance sheet. It said the company would deploy adequate capital where required to support competitive and profitable growth.
Financial Performance Shows Broad-Based Growth
Bharti Hexacom reported a strong April-June quarter, with total revenue rising 10.9% YoY to Rs 2,510 crore. While mobile services revenue grew 9.3% YoY, supported by higher ARPU and customer additions, the homes, offices and other services segment remained a key growth driver, with revenue increasing 61.4% YoY.
Profit for the period grew from Rs 392 crore in Q1FY26 to Rs 482 crore, logging a 23.2% YoY growth.
Is the company fairly valued?
Shares of Bharti Hexacom are trading at a P/E of 40.9x, at par with the industry median. While the PEG ratio is 0.9x, a little over the industry median of 0.8x, indicating that the stock might be relatively overpriced even if adjusted for growth prospects.
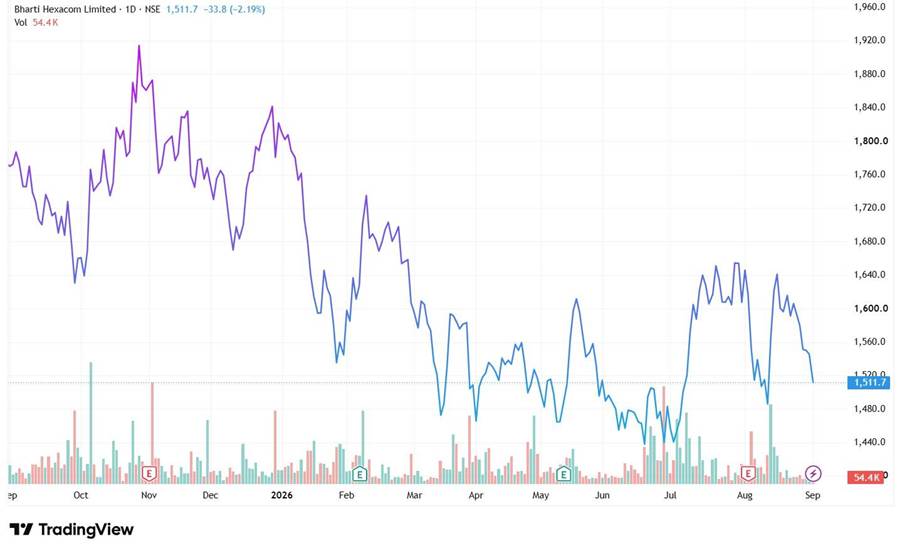
1-Year Share Price Chart of Bharti Hexacom Ltd.
#3 TBO Tek: Negative Working Capital Supports A Scalable Model
TBO Tek Ltd. operates online technology platforms that connect travel buyers with suppliers such as airlines and hotels, providing access to global travel inventory. Its business spans India and international markets, with hotels and ancillary services forming an important part of the platform.
The company’s model is built around scaling transaction volumes through its technology platform without a proportionate increase in operating costs. Management said the platform and its operating infrastructure can support higher business volumes without requiring a commensurate increase in costs.
TBO Tek’s working capital days stood at -134 days in FY26, compared with -104 days in FY25 and -114 days in FY24. This puts its three-year average at around -117 days, indicating that the negative working capital position has persisted rather than being a one-year occurrence.
The company’s debtor days were 724 days in FY26, below the three-year average of around 752 days. Though the debtor days look quite high, it is primarily due to the nature and accounting of the travel distribution business.
The cash position also benefited from the working capital cycle in the latest quarter. Cash and cash equivalents rose by Rs 392 crore to Rs 1,984 crore as of June 30, with management attributing part of the increase to a working capital release.
Europe And North America Add Growth Visibility
The company’s geographical diversification has become an important buffer. Europe delivered 24% YoY growth despite the disruption, while North America is becoming more significant following the acquisition of Classic Vacations. Management said North America now accounts for almost a quarter of hotel GTV and sees the North America-Europe corridor as relatively more resilient.
The Classic Vacations integration is another potential growth lever. TBO is expanding its sales team in North America, integrating back-office and customer-service systems, and plans to complete platform integration by the end of calendar year 2026. This should allow more seamless buying and selling between the two platforms and provide further cross-selling opportunities.
Financial Performance Shows Operating Leverage
TBO Tek reported strong Q1FY27 numbers despite disruption in global travel. Gross Transaction Value (GTV) increased 37% YoY to Rs 11,154 crore, while revenue from operations rose 81% to Rs 926 crore during the quarter. Profit for the period surged 32% to Rs 83 crore from Rs 63 crore a year ago.
Management said the quarter provided the first clear demonstration of operating leverage, with EBITDA margins expanding faster than revenue and gross-profit margins. They expect bottom-line growth to accelerate as top-line growth normalises.
Valuation Remains Elevated
Shares of TBO Tek are trading at a P/E of 69.5x, compared to the industry median of 41.6x, while the PEG ratio is 3.7x, higher than the industry median of 0.3x, indicating that the stock is relatively expensive compared to its peers.
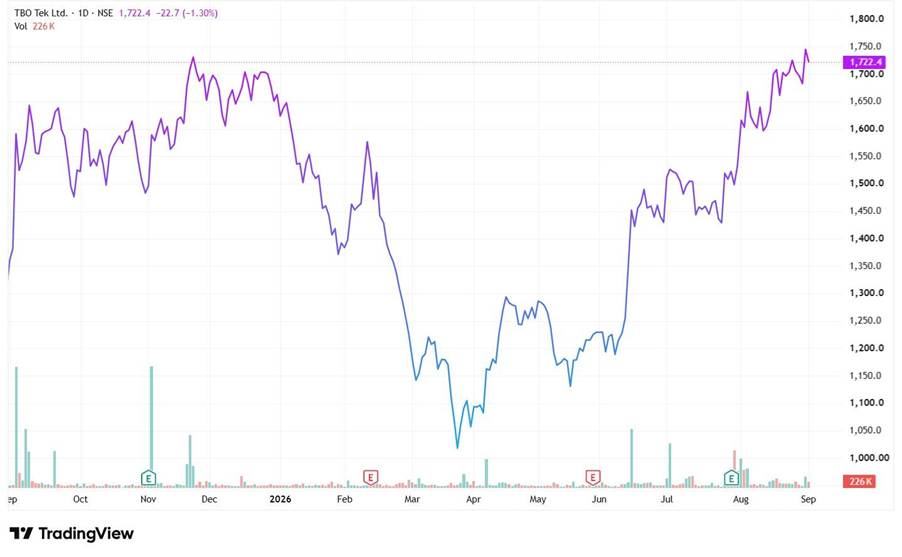
1-Year Share Price Chart of TBO Tek Ltd.
What The Cash Cycle Tells Us
Thus, negative working capital can be beneficial for businesses, but investors need to check whether that is structural and sits alongside growth, profitability, and strong cash generation. The three companies in this list illustrate different ways in which that advantage can emerge, such as low receivables and cash-generating operations, business models, customer collections, and operating leverage supporting expansion.
However, a negative working-capital cycle by itself does not make a stock attractive. The quality and durability of the cash cycle, the capital required for future growth, and the ability to sustain returns on capital remain important. Valuations also vary significantly across the three companies, with the market already pricing in strong growth expectations in some cases.
So, for investors, the key is to look beyond the negative working-capital number and assess whether the cash-cycle advantage can persist as the business scales; for that, you can add these stocks to your watchlist for now.
We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
Maumita Mitra is a seasoned writer specializing in demystifying the world of investment for a broad audience. She has a keen eye for detail and a knack for explaining complex financial concepts in the simplest manner possible.
Disclosure: The writer and her dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities, or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives and resources, and only after consulting such independent advisors as may be necessary.