



For years, textile manufacturers built their business around volume: manufacture cheaper, scale faster. That model built one of the country’s largest employment-generating export sectors, but also exposed a fundamental weakness. When the products are harder to differentiate, businesses have much less pricing power.
Over the past decade, Indian manufacturers have faced intense competition from Bangladesh and Vietnam in garmenting to China in synthetic fibres and technical fabrics. At the same time, volatility in cotton prices, labour and energy costs have reduced the cost advantage. For manufacturers competing on volume, scale can increasingly become a burden.
That leaves traditional textile businesses with relatively thin and cyclical margins. For textile companies, the opportunity is therefore shifting from making more to making more valuable products. The volume play alone may no longer be enough.
Arvind Ltd. and Welspun Living are taking different routes to get there. Arvind is moving towards technical textiles and specialised materials, where products are harder to commoditise. Welspun, meanwhile, is betting on brands, new categories and local manufacturing closer to its customers. Their latest quarter numbers offer an early indication of how these strategies are playing out.
Join now
#1. Arvind Ltd.: Moving Towards Specialised Materials
Arvind is slowly trying to reduce its dependence on the cyclical, lower-margin end of the textiles business. Its new focus area has been the Advanced Materials Business (AMB), which develops specialised solutions across human protection, industrial, and composites. In this segment, technical expertise, engineering know-how, and intellectual property matter more than manufacturing.
To strengthen its footprint in the AMB segment, Arvind acquired a 61% stake in US-based Dalco-GFT for $136 million. The company operates two manufacturing facilities in North and South Carolina and makes needle-punched non-wovens used across automotive mobility and civil geotextiles. Through this acquisition, Arvind got access to a roughly $2.5 billion addressable market.
Arvind Ltd. Financial Performance
| Period | FY25 | FY26 | Q1FY26 | Q1FY27 |
| Revenue (₹ crore) | 8,329 | 9,303 | 2,006 | 2,501 |
| YoY Growth (%) | – | 11.7% | – | 24.7% |
| EBITDA Margin (%) | 11.00% | 11.40% | 9.30% | 10.30% |
| Net Profit (₹ crore) | 367 | 444 | 55 | 80 |
| YoY Growth (%) | – | 21.0% | – | 45.5% |
Arvind’s increased focus on the AMB segment is reflected in the numbers as well. In Q1FY27, revenue increased 24.7% YoY to ₹2,501 crore. This includes the number of Dalco-GFT. EBITDA margin expanded by one percentage point to 10.3% during the period.
Arvind Ltd: Business Segment Performance
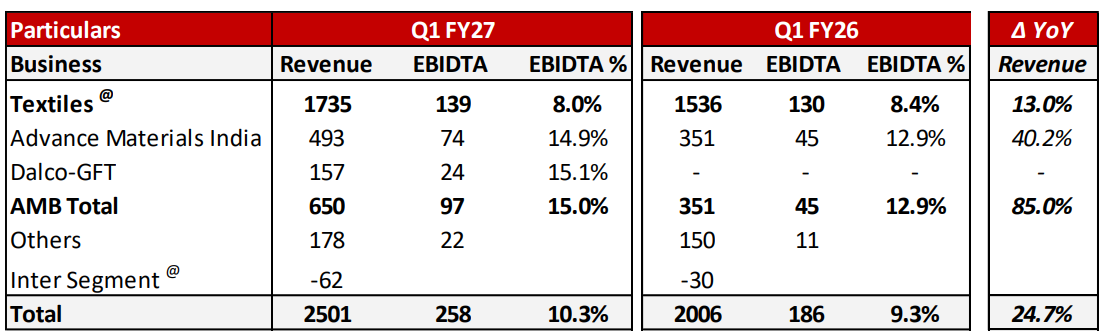
Revenue and profit growth is being led by Arvind’s Advanced Materials Business (AMB), which is growing faster and earning higher margins than its traditional textiles business. In Q1 FY27, AMB revenue rose nearly 85% year-on-year to ₹650 crore, while its EBITDA margin stood at 15%, compared with 8% for the textiles segment.
The management expects AMB to deliver high-teens to 20% revenue growth in FY27, suggesting that the segment could become an increasingly important driver of Arvind’s overall growth and profitability. The textile division is targeted to grow in the mid-teens, driven by volume expansion.
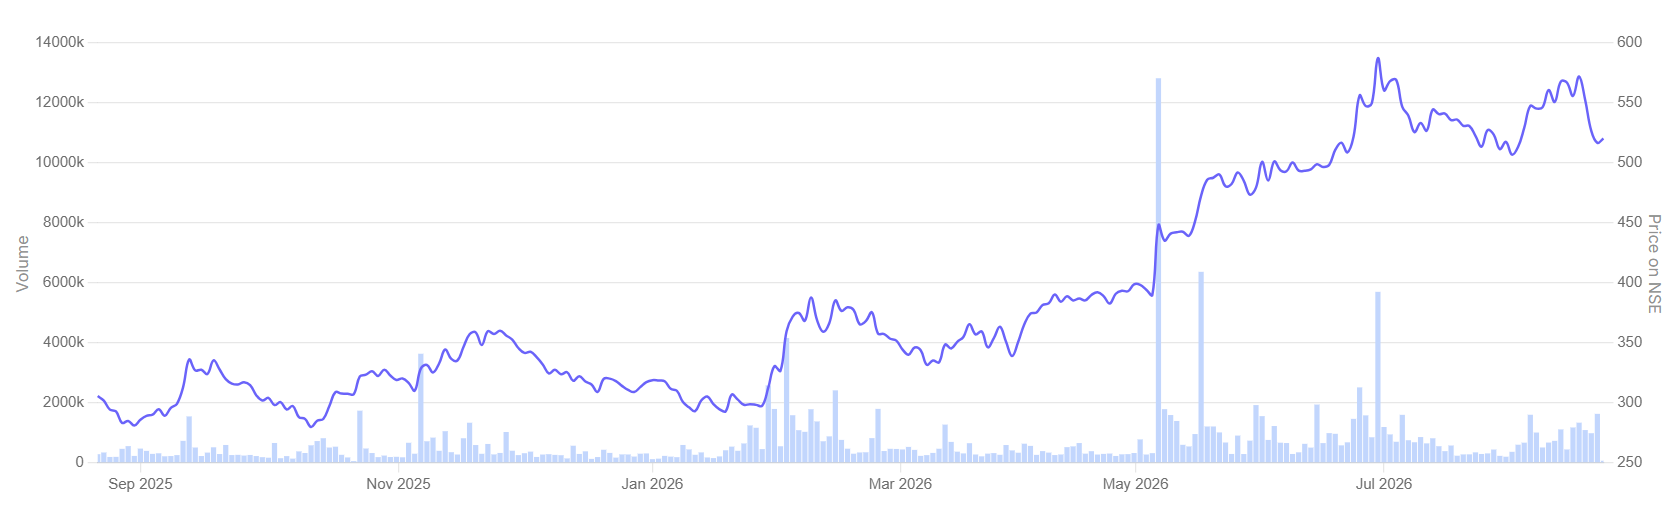
Improving operational metrics has also resulted in a sharp re-rating of the stock price. Over the past 12 months, the stock has rallied from around the ₹300 level to an all-time high of around ₹600.
Arvind Ltd.: 1 Year Stock Price Chart
Welspun Living: Moving Closer to the Consumer
Welspun Living Limited is a global leader in home textiles with vertically integrated manufacturing facilities across India and distribution across 60+ countries. It holds market leadership in towels and bath rugs and is the top-2 player in sheets in the US. The company operates across three core business segments: Home Textiles (bath linen, bed linen, rugs, and carpets), Advanced Textiles (spunlace, needle punch, wet wipes), and Flooring Solutions.
Unlike Arvind Ltd., which is moving up the value chain, Welspun is taking a different route to move away from the commoditised end of home textiles. It is building brands, proprietary products, and manufacturing capacity closer to its end consumers.
Its US pillow business is perhaps the clearest example of this strategy. Revenue from the US onshore pillow platform grew 2.3 times year-on-year in Q1FY27. The Ohio plant operated at more than 80% utilisation, while its second US facility in Nevada became fully operational during the quarter, adding capacity of 4.5 million pieces.
Welspun is targeting $60 million in US pillow revenue in FY27, more than double the $27.5 million generated in FY26.
Changing its Business Mix
Localised manufacturing helps Welspun to supply American retailers and hospitality customers locally, reducing freight disruption, tariff risks, and shortening delivery times. Welspun’s strategy also extends beyond moving closer to customers. It is also changing its business mix.
Innovation-led products, including proprietary technologies such as HygroCotton, GX Pillow and Wel-Trak, grew 16% year-on-year and contributed around 25% of consolidated revenue in Q1FY27. The company has more than 50 global patents supporting these products.
Its branded portfolio is growing even faster. Brands such as Christy, Spaces, Welspun, Welhome, and Welspun Hospitality grew 25% year-on-year and accounted for 18% of revenue.
Welspun Living: Financial Performance
| Period | FY25 | FY26 | Q1FY26 | Q1FY27 |
| Revenue (₹ crore) | 10697 | 9468 | 2289 | 2828 |
| YoY Growth (%) | – | -11.5% | – | 23.5% |
| EBITDA Margin (%) | 13.6 | 9.10% | 11.10% | 12.50% |
| Net Profit (₹ crore) | 639 | 204 | 88 | 161 |
| YoY Growth (%) | – | -68.0% | – | 83.0% |
The impact of the shift in business strategy is also reflected in the financials. In Q1FY27, consolidated revenue rose 23.5% YoY to ₹2,828 crore, while EBITDA margin improved to 12.5%.
One of the important highlights of the transformation is that management expects Return on Capital Employed (ROCE) to rebound from FY26 levels (pre-tax reported at 5.6%) to more than 15% over the next 3 years.
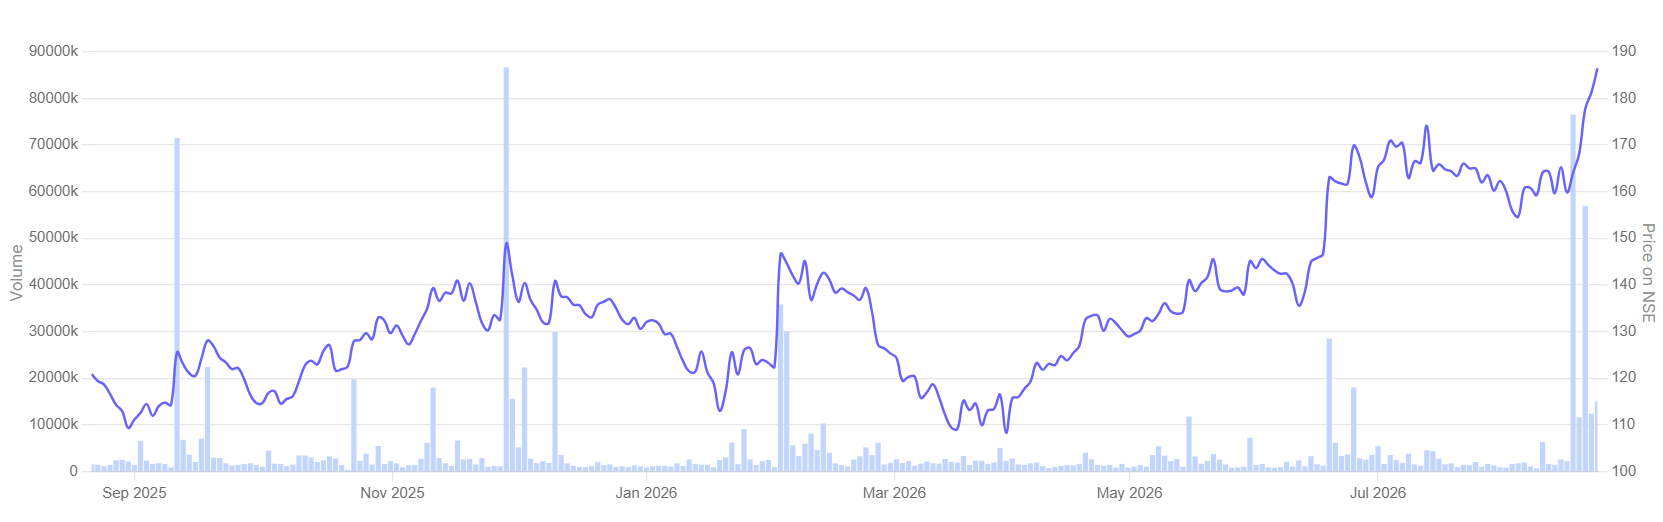
The operational turnaround in performance is resulting in a sharp rerating of the stock. Welspun Living stock has rallied from around ₹120 in August 2025 and has reached closer to ₹190.
Welspun Living: 1 Year Stock Price Chart
Valuation: Investors Are Already Pricing in the Transformation
Both Arvind and Welspun are ideally trying to capture more value by developing differentiated products and changing the business mix. And the strategy seems to be working for both companies.
Valuation Trend
| Metrics | Trailing P/E | 5-yr Median PE |
| Arvind Ltd. | 33.4 | 22.0 |
| Welspun Living | 64.1 | 22.7 |
The market has already recognised the shift in both businesses, and that is visible in their valuations. Arvind trades at 33.4 times trailing earnings, against its five-year median P/E of 22 times. Welspun Living trades at 64.1 times, nearly three times its five-year median P/E of 22.7 times.
This has now turned more into an execution story. The current valuation suggests Arvind has more room for its earnings to catch up with its valuation if AMB delivers on its growth targets. Welspun, meanwhile, has less room for execution to disappoint because a much larger part of its expected improvement appears to be reflected in the stock price.
In other words, Arvind needs to prove that its transformation can scale, while Welspun needs to prove that its current earnings momentum can persist.
Both companies show how the textile opportunity is shifting from volume to value. The winners may not be those that add the most capacity, but those that can build defensible niches, improve pricing power, and earn better returns on capital. Add these stocks to your watchlist and monitor how they execute their growth plans.
Disclaimer:
Note: We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Deepan Datta has spent over a decade studying stocks and mutual funds. His passion is to uncover interesting stories in the financial markets and share them through his writings with investors at large. He is focused on delivering clear, easy to understand and research-backed insights. Deepan began his career as a Research Associate at S&P Global, where he developed a strong foundation in financial research and data analysis.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, their employees (s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.