



Contrarian Trade: Buying the Regulatory Mess
There is a kind of company professional money managers like but retail money will not touch: a company that has just been told “no” by its regulator. The order lands, the price gaps down, and the sellers are, well, retail investors who are unable to rationally think through the situation. That is usually when the professional money managers come in.
Ashish Dhawan, who built ChrysCapital before turning to Ashoka University, has spent a career on exactly that trade. Private equity teaches you to underwrite the mess the public market will not price. The June 2026 filings show him at it again, twice, in one sector.
Join now
He took one holding from roughly 4.1% to 5.2%, and lifted a relatively new position from 1.09% to 1.33% within one quarter of opening it. Together the two are worth over Rs 760 cr. What links them is not the sector. It is the Reserve Bank of India. Let us dive in.
#1 IIFL Finance: The 128% Recovery from Regulatory Exile
In March 2024, the Reserve Bank ordered IIFL Finance to stop giving gold loans, citing regulatory lapses in how it valued the gold it lent against and how it handled cash. Gold was the engine of the business. The engine stayed off for roughly six months.
One line item in the accounts carries the damage. Net profit fell from Rs 1,974 cr in FY24 to Rs 578 cr in FY25, down about 71%. The ban lifted in September 2024. The rebuild began there.
Two years on, the rebuild looks done. The loan book stands near Rs 1.16 lakh cr, up 38% over the year, spread across gold, home loans, small business credit and microfinance, run out of roughly 4,700 branches. Nearly 90% of it is secured against something the borrower has pledged, which is a different animal from the unsecured lending troubling the sector.
Reigniting the ₹58,406 Crore Gold Loan Engine
June 2026 was the best quarter the company has reported. Net profit came in at Rs 713 cr, up about 160% on the year and 14% on the March quarter, with revenue up roughly 33% to Rs 3,919 cr. Annualised return on equity touched 19.5%.
Gold did the lifting. That book grew 114% to Rs 58,406 cr, a little over half of everything the company lends. The business the regulator shut two years ago is now the single reason the profit line reads as it does.
Two profit numbers are doing the rounds. The Rs 713 cr sits before the slice owned by minority holders in the subsidiaries; the parent’s own share is about Rs 675 cr.
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5Y CAGR |
| Revenue (Rs cr) | 5,968 | 6,991 | 8,444 | 10,472 | 10,233 | 13,366 | 18% |
| Financing Profit (Rs cr) | 1,090 | 1,625 | 2,263 | 2,734 | 1,478 | 2,612 | 19% |
| Net Profit (Rs cr) | 761 | 1,188 | 1,608 | 1,974 | 578 | 1,817 | 19% |
For a lender, the honest operating measure is financing profit, what survives interest paid and running costs. The EBITDA you would use for a factory means little when the raw material is borrowed money. That FY25 dip is the ban.
Why IIFL Trades 45% Below Sector Averages
The IIFL Finance share price was near Rs 275 in August 2021 and as on 19th August 2026 it was Rs 626, which is about a 128% jump in 5 years.
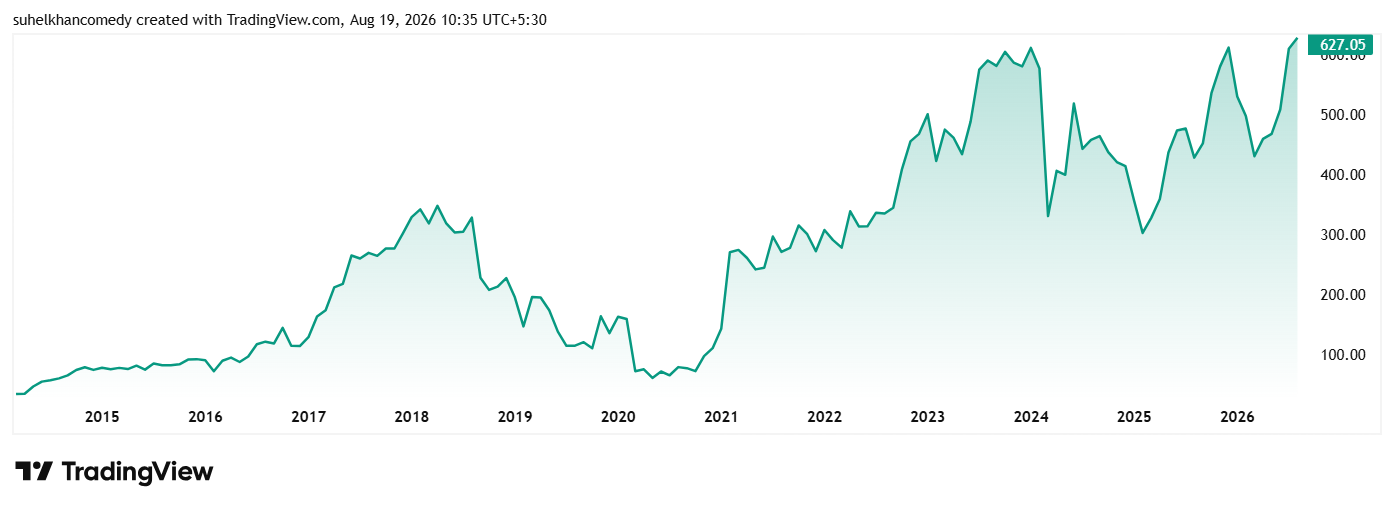
Valuation is where this turns interesting. The stock trades at a PE of about 13x and the industry median currently is 20x. It trades at 1.9 times book. The company’s 10-year median PE is also 13x, so it sits almost exactly on its long-run average. The industry median across those same 10 years is 23x. A lender fresh off a record quarter, with return on equity near 20%, is priced roughly 45% under what the sector has historically fetched.
The Hidden Costs of 35% Debt-Fuelled Growth
First, asset quality ticked the wrong way in June: gross bad loans 1.55% against 1.46% three months earlier, net bad loans 0.82% against 0.73%. Small moves, but direction matters when a book grows this fast.
Second, borrowings climbed roughly 35% in FY26 to about Rs 69,176 cr. Growth this quick has to be paid for, and it is being paid for with debt. A $500 mn social bond went out in June 2026, and a further equity raise has been flagged.
Third, concentration. Just over half the book is one product, and it is the product the regulator objected to in 2024. Management expects that growth to slow. Add 500 new branches planned for FY27, which lift costs before they lift revenue, and the execution list runs long.
Dhawan’s position reads as conviction and caution at once. He arrived in the March 2026 quarter at 1.09%, then added another 10 lakh shares to reach 1.33% by June, worth about Rs 352 cr. He is building, but this is not yet a top holding. Meanwhile, foreign institutional holding fell from 28.16% to 23.86% that same quarter. He bought while overseas money left.
#2 Religare Enterprises: A ₹415 Crore Bet on a Blocked Catalyst
If IIFL is the far side of an RBI problem, Religare is the near side. It is a holding company, not an operating one, owning roughly 63% of Care Health Insurance plus a small business lender, a housing finance arm and a broking unit.
This is old ground for Dhawan. He sat near 2.3% across 2023 and 2024, stepped up to 4.1% by early 2025, and put on close to 37 lakh more shares last quarter to land at about 5.2%. At Rs 415 cr, it is his second largest disclosed position. A late June filing briefly showed 5.42%, a shade above where the quarter closed, which points to a small trim at the end.
The Demerger Dilemma: Why the RBI Said No
Then the ground moved. The board had approved a scheme splitting the financial services businesses from insurance into two separately listed entities. That split was the entire argument, because it would let the market price the insurance franchise directly instead of through a parent that owns other business as well.
The exchanges cleared it. The Reserve Bank did not. A letter dated 6th August 2026 said the request had been examined and was not being acceded to. The company says it will go back for clarifications.
That is the catalyst blocked. Not cancelled, but blocked, on a timeline nobody can date.
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5Y CAGR |
| Sales (Rs cr) | 2,513 | 3,227 | 4,679 | 6,266 | 7,385 | 8,459 | 28% |
| Operating Profit (Rs cr) | 278 | -364 | 483 | 368 | 356 | 136 | Turnaround, Then Drop |
| Net Profit (Rs cr) | -478 | -1,539 | 3,169 | 347 | 183 | 73 | Turnaround, Then Drop |
Two rows need care. That FY23 figure of Rs 3,169 cr came from neither lending nor underwriting. It rests on Rs 3,473 cr of other income booked as the old loan book was cleaned up, and it flatters every ratio it touches. FY21 was a loss, so a five-year profit growth rate has little or no meaning. Operating profit fell, Rs 278 cr to Rs 136 cr, and a growth figure there would mislead.
Only the top line grew honestly, compounding about 28% a year on insurance premiums.
Profitable Arms, Bleeding Parent: The Q1 Reality Check
The June quarter results, out on 12th August, made the gap plain. Revenue rose about 26% to Rs 2,353 cr, yet the consolidated line still closed at a net loss of Rs 47 cr, with an operating loss of Rs 49 cr.
The pieces underneath did well. Premiums at Care Health rose 37% to Rs 3,247 cr, pre-tax profit up 59% to Rs 163 cr. The broking arm lifted income 7% and profit 65%, with assets under custody near Rs 47,946 cr. Finvest, once the source of all the trouble, turned in Rs 15.1 cr on recoveries against a net worth of Rs 914 cr and Rs 609 cr of cash.
The businesses work. The structure holding them does not turn that into reported profit, and the demerger was the fix.
The 161x PE Anomaly: A Thinning Float and a Promoter Showdown
Five years ago, in August 2021, the Religare Enterprises share price sat near Rs 136 and as on 19th August 2026 it was Rs 231.
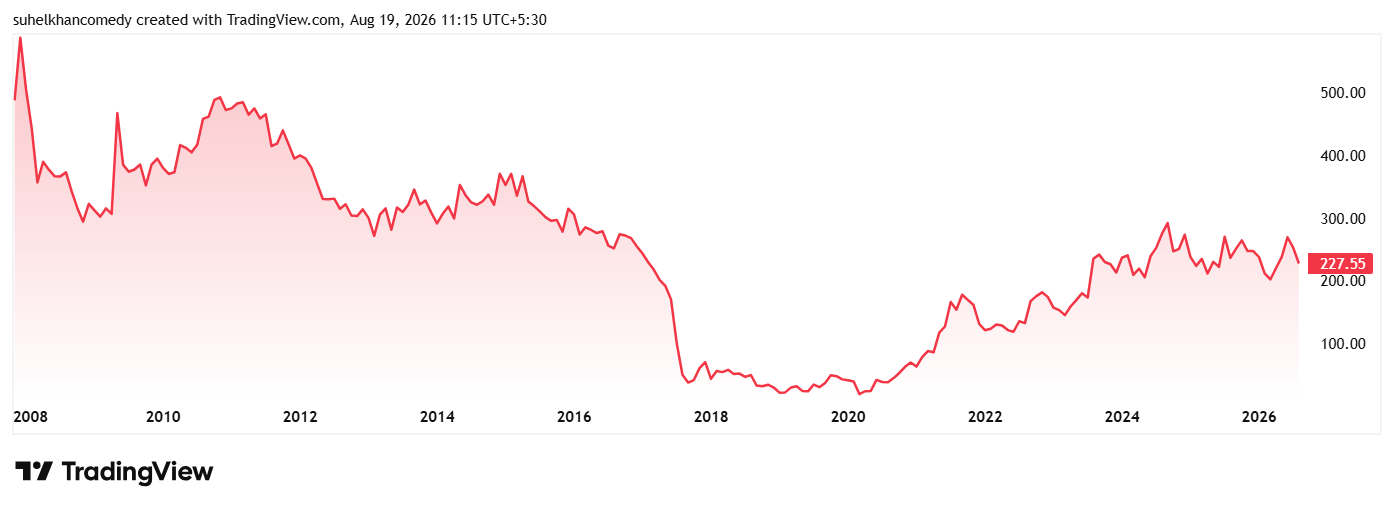
As for the valuations, the stock is trading at a PE of a big 161x, and the industry median currently is 27x. The 10-year median PE for the stock is 73x while the industry median for the same period is 20x. Return on equity is 3.2%. Borrowings have crept back from Rs 233 cr to Rs 493 cr. No dividend is paid, and an RBI letter from December 2019 forbids one.
The bet is what the insurance and lending arms fetch if they are ever priced on their own. The Burman family of Dabur, promoters with 30.55%, are betting the same way with far more money. Public holding has slid from 83.92% in March 2024 to 50.49%, and both foreign and domestic institutions added last quarter. The float is clearly thinning.
The Watchlist Verdict: Sizing the “Far Side” vs. “Near Side” Risk
Set them side by side and the shape shows. IIFL Finance is an RBI problem viewed from the far end: two years, a rebuilt book, record profit, a share still cheap against sector history. Religare is the near end: a blocked plan, a quarterly loss, and a price that holds only if you accept an argument the accounts do not yet make.
Dhawan sized them accordingly. Religare is the older, larger holding, built over years and topped up with weight. IIFL is newer, smaller, still being assembled. These are not the same trade, and readers should not treat them as one.
The pattern matters more than the picks. Regulatory trouble manufactures forced sellers, and forced sellers set prices that have little to do with the business underneath. The catch is that early and wrong feel identical for a long time. IIFL needed two years and a lifted ban to settle the argument. Religare has been sent back to the start with no clock running, and the next letter could say no again.
The sensible move is to put both on a watchlist and follow the regulator rather than the companies. On this evidence, that is where the story gets decided.
Disclaimer:
Note: We have relied on data from http://www.Screener.in and http://www.trendlyne.com throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Suhel Khan has been a passionate follower of the markets for over a decade. During this period, He was an integral part of a leading Equity Research organisation based in Mumbai as the Head of Sales & Marketing. Presently, he is spending most of his time dissecting the investments and strategies of the Super Investors of India.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.