



One of the strongest signals about a company’s future growth potential comes when promoters put their own money behind the business. It becomes even more interesting when they do so alongside institutional investors.
That is exactly what happened with Piramal Finance and Ather Energy. Both companies raised money from institutions through a Qualified Institutional Placement (QIP), while their promoters simultaneously committed fresh capital through warrants.
And there is one detail that stands out. In both cases, promoters agreed to pay more than the QIP floor price. This is not a guarantee that the stocks will deliver returns. But when promoters are willing to put fresh money at stake alongside institutional investors, it is a signal worth looking at.
Why this QIP + Warrants Combination Matters
A QIP is a way for a listed company to raise money from institutional investors such as mutual funds, insurers, and foreign investors. On the other hand, a promoter warrant issue works differently. It gives promoters the right to buy shares at a fixed price, but they must pay 25% of the issue price upfront when the warrants are allotted.
Join now
They then have 18 months to pay the remaining 75% and convert the warrants into shares. If they do not convert the warrants within this period, the 25% upfront amount is forfeited.
This QIP + Warrants combination points to a simple thing. Institutions are putting fresh money into the company, while promoters are also increasing their skin in the game through financial exposure. This pattern is not just limited to these two companies.
Why Piramal Finance and Ather Energy Stand Out
There are several Indian companies that have followed a similar route in 2026. Such as:
- KIMS Hospitals paired a ₹1,500 crore QIP with a ₹600 crore promoter warrant issue to the Bollineni family. The warrants were priced at ₹779, against a QIP floor price of ₹771.73.
- Arvind Limited: The textile major launched a ₹500 crore QIP on August 3, 2026.
- Netweb Technologies India: The high-end computing and AI infrastructure provider successfully raised ₹1,200 crore through a QIP.
- Adani Energy Solutions: In late July 2026, they launched a QIP with a base size of ₹3,500 crore, and it was subscribed over three times.
- JSW Infrastructure: The company raised ₹6,555 crore in fresh capital through a QIP, which was executed alongside a promoter Offer for Sale (OFS) of ₹948 crore. In an OFS, the proceeds don’t come into the company’s treasury. Instead, go directly to the selling shareholders.
Now, Piramal Finance and Ather Energy stand out for two reasons. First, both institutions and promoters are putting fresh money into the companies. Second, and more importantly, both companies are raising this capital to fund growth.
KIMS Hospitals, Arvind Ltd., and Adani Energy Solutions are using the funds primarily to repay debt and strengthen their balance sheets. Netweb Technologies and JSW Infrastructure, meanwhile, are raising money largely to fund capital expenditure.
Piramal Finance: Capital to Grow the Loan Book
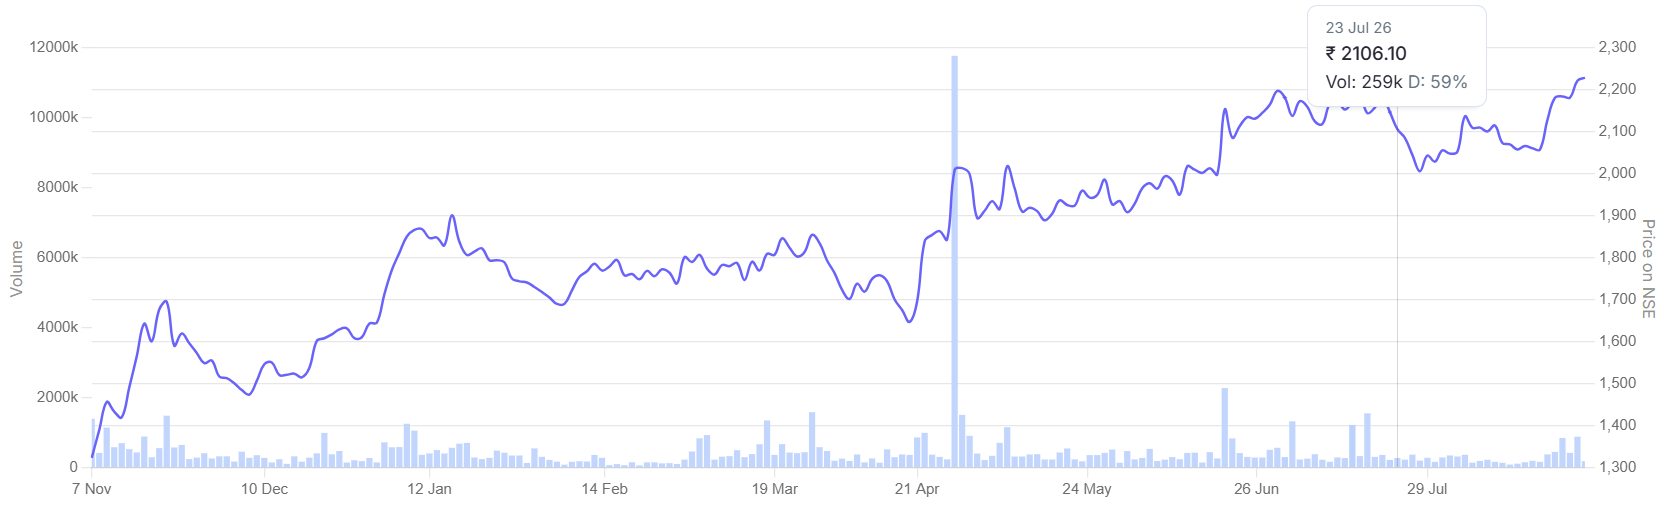
Piramal Finance’s QIP opened on August 24, 2026, with a floor price of ₹2,102.65 per share. The company is looking to raise close to ₹2,100 crore from institutional investors.
On the same day, its board approved a preferential issue of up to ₹1,750 crore to promoter entity Nithyam Realty. The issue covers 82.94 lakh warrants priced at ₹2,110 each, slightly above the QIP floor price.
Together, the two fundraises could bring in around ₹3,850 crore. As per the company, the proceeds from the fundraise will be used for onward lending and capital adequacy.
Why Does Piramal Finance Need Money?
To understand why Piramal Finance needs more money, first, we have to look at its financial performance.
Piramal Finance: Financial Performance
| Period | FY25 | FY26 | Q1FY26 | Q1FY27 |
| Net Interest Income (₹ crore) | 3,591 | 4,731 | 1,010 | 1,442 |
| YoY Growth (%) | – | 31.7% | – | 42.8% |
| Net Interest Margin (%) | 5.8% | 6.3% | 6.1% | 6.5% |
| Net Profit (₹ crore) | 485 | 1,506 | 276.00 | 461.00 |
| YoY Growth (%) | – | 210.5% | – | 67.0% |
Piramal Finance’s Q1FY27 numbers show why the company is looking to expand. Consolidated profit rose 67% YoY to ₹461 crore, while net interest income increased nearly 43% to ₹1,442 crore. Net interest margin also expanded during the quarter to 6.5%, compared to 6.1% a year earlier.
Asset Quality and Structural Transformation
Assets under management grew 25% to ₹1.07 lakh crore. The retail loan book grew even faster at 32% and was ₹91,249 crore at the end of June 2026. Asset quality is steadily improving. Gross Non-Performing Assets (NPA) fell to 2.4% in the first quarter of FY27, from 2.8% a year earlier.
There is also a structural change underway. Earlier, Piramal Finance operated as a housing finance company (HFC). This restricted Piramal from growing its non-housing loan book. To fix this, Piramal surrendered its HFC license, and the RBI granted it a Non-Banking Financial Company- Investment and Credit Company (NBFC-ICC) license in April 2025.
The company is therefore trying to build a larger and more diversified lending business. The QIP and promoter warrants will therefore support further loan growth and strengthen the balance sheet.
Piramal Finance already has a clear growth target. Management is targeting around 25% AUM growth in FY27, taking the loan book to roughly ₹1.25 lakh crore, along with around 50% growth in net profit. For investors, the next few quarters will be important. The key things to watch are whether business grows on expected lines with steady improvement in margins and NPA levels.
Piramal Finance: 1-year Stock Price Chart
Ather Energy: Betting on Capacity and the EV opportunity
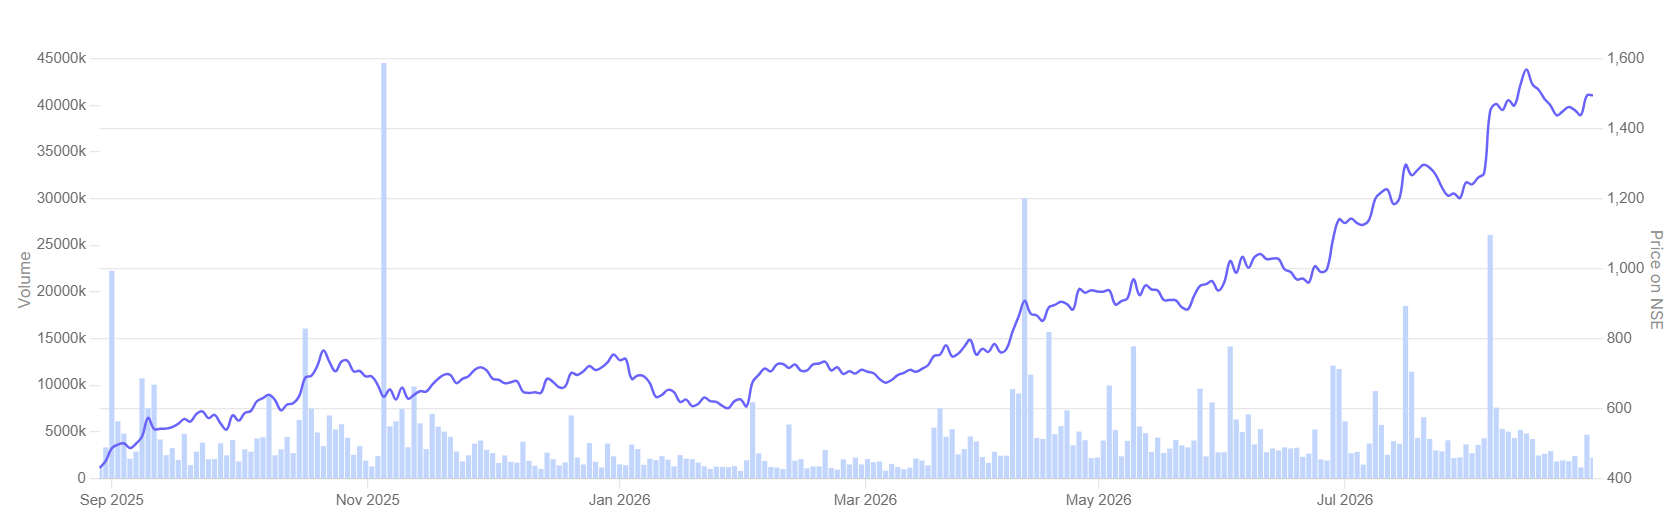
Ather’s story is very different. The electric two-wheeler maker approved a ₹2,500 crore fundraising plan in June 2026, including a QIP of up to ₹1,500 crore. The QIP eventually raised ₹1,300 crore at ₹1,202 a share after being oversubscribed roughly eight times. The company then moved ahead with its preferential issue.
The India-Japan Fund was allotted shares at ₹1,230 each, while promoters Hero MotoCorp, Tarun Mehta and Swapnil Jain were offered warrants at ₹1,260 each. Both prices were above the QIP floor of ₹1,169.70. Hero MotoCorp alone committed around ₹960 crore through the warrants, which will raise its fully diluted stake to 30.68%.
Where Will Ather Use the Money?
Like Piramal Finance, Ather is also raising capital to expand manufacturing capacity and develop products. Ather is currently at an inflection point to turn its operations profitable and grow. The financials of the company also reflect a classic transition.
Ather Energy: Financial Performance
| Period | FY25 | FY26 | Q1FY26 | Q1FY27 |
| Revenue from Operations (₹ crore) | 2,255 | 3,672 | 645 | 1,217 |
| YoY Growth (%) | – | 62.8% | – | 88.7% |
| EBITDA Margin (%) | -23.0% | -7.0% | -16.0% | 0.8% |
| Net Profit (₹ crore) | -812 | -517 | -178 | -51 |
| YoY Growth (%) | – | 36.3% | – | 71.3% |
The company’s Q1FY27 numbers suggest that the business is moving closer to profitability. Revenue from operations jumped 88.7% YoY to ₹1,217 crore. Net loss narrowed by 71% to ₹51 crore. More importantly, Ather reported its first-ever positive Earnings Before Interest, Tax, Depreciation, and Amortisation (EBITDA), at ₹9.45 crore. For the company, this is an important milestone.
Bridging the Supply-Demand Gap
The biggest takeaway from Q1FY27 numbers was volume. Ather sold more than 83,000 scooters during the period, compared to 46,000 in Q1FY26.
As demand is growing, the company is now facing supply constraints. Management said it could have sold another 13,000-15,000 scooters a month if it had sufficient capacity. Many dealers have stopped accepting new orders because of the long waiting time. Customer enquiries increased 95% year-on-year, while pre-orders rose 158%.
Therefore, the company is building a new manufacturing facility, dubbed Factory 3.0, located at Chhatrapati Sambhajinagar, Aurangabad. Once fully scaled, Factory 3.0 will have a capacity of 1 million units annually, pushing Ather’s total capacity to around 1.42 million units per year. The biggest chunk of fundraise is now being used in operationalizing this manufacturing facility.
Also, a part of the funds will be used in R&D and new product development, as Ather shifts from being a niche performance brand to a mainstream volume player. For investors, Ather has now become an execution story. The focus will be on how fast it can scale its operations amid intense competition from established two-wheeler players.
Ather Energy: 1 Year Stock Price Chart
The Real Signal is What Happens After the Fundraise
Promoter participation makes these fundraises worth watching, but the real test starts after the money comes in. For Piramal Finance, investors need to see whether the additional capital translates into sustained loan-book growth without a deterioration in asset quality.
For Ather Energy, the focus will be on whether the new capital can help the company add capacity, meet demand and move from its first positive EBITDA quarter towards sustainable profitability.
That is also what separates these two companies from other QIP-plus-warrant deals. The story is not simply that promoters are putting their own money in. It is that both promoters and institutions are backing a growth plan. But ultimately, the market will value the company based on execution. Add these stocks to your watchlist and monitor how they execute their growth plans.
Disclaimer:
Note: We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Deepan Datta has spent over a decade studying stocks and mutual funds. His passion is to uncover interesting stories in the financial markets and share them through his writings with investors at large. He is focused on delivering clear, easy to understand and research-backed insights. Deepan began his career as a Research Associate at S&P Global, where he developed a strong foundation in financial research and data analysis.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, their employees (s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.