



Imagine ordering a product today and hearing it will take 14 years to arrive. That is the current reality for commercial aviation. Major manufacturers are sitting on a massive backlog of over 15,255 unfulfilled aircraft orders (as of August 2025), locking in production demand for the next decade.
Macro Trajectory: Macro Projections Driving Indian Aerospace Manufacturing
For investors, this creates a fascinating landscape. As per Frost & Sullivan, the global aerospace market is projected to grow from US$188.04 billion (2024) to US$272.56 billion by 2030. Back in India, local airlines have placed over 1,260 unfulfilled aircraft orders (as of June 2025). India is also rapidly transforming into a critical manufacturing hub.
The Indian aerospace manufacturing market is projected to nearly double, expanding from ₹13,051 crore in 2024 to ₹25,709 crore by 2030. Most importantly, exports of aerospace components have already increased to ₹58,838 crore in FY25, driven by the Make in India and production-linked schemes for the aerospace sector.
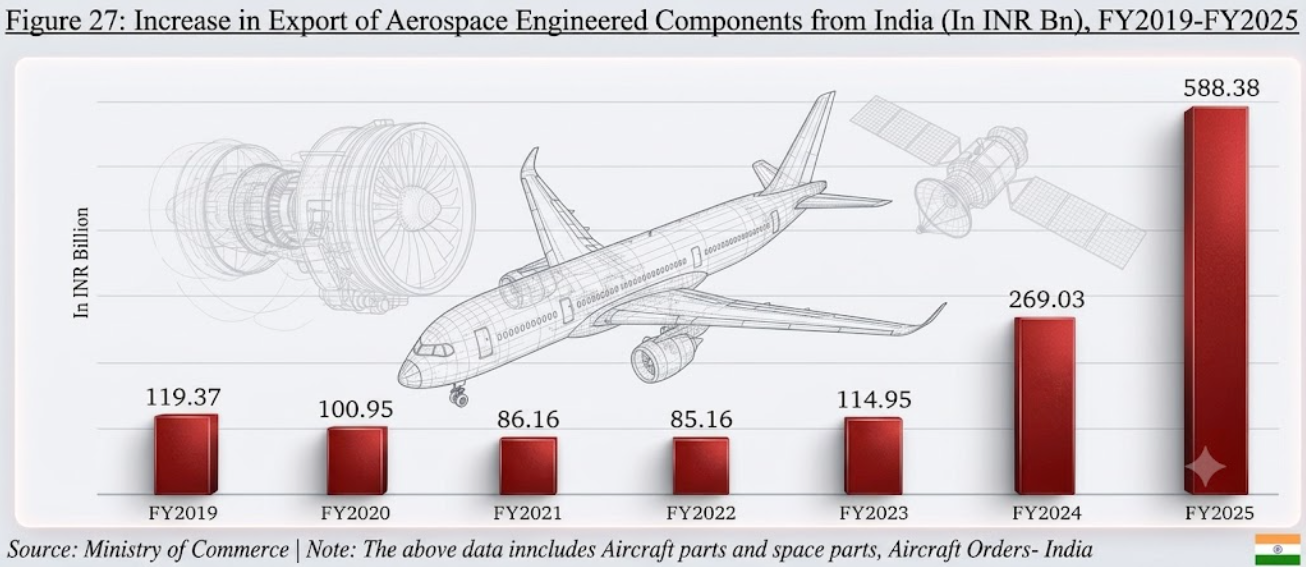
The numbers and growth demonstrate that India has emerged as one of the most significant markets not only for aircraft orders but also for component suppliers. This aligns with the aerospace supply chain, a global network of manufacturers, suppliers, and distributors that provide components and materials for aircraft, spacecraft, and defence systems.
Thus, beyond cash-guzzling aerospace manufacturers, the real opportunity may lie with mission-critical suppliers that build essential components, benefiting from the sector’s growth often with far lower capital requirements.
Key Financial Metrics as of FY26 (In ₹ Crore)
| Particulars | Exports | Order Book | Revenue | Profit |
| Rossell Techsys | 98.0% | 715.0 | 485.0 | 20.7 |
| Azad Engineering | 93.0% | 6,500.0 | 590.4 | 132.0 |
| Aequs | 85.0% | 8,500.0 | 1,046.4 | -113.0 |
| Source: Q4FY26 Investor Presentation | ||||
The combined order book of these three companies stands at ₹ 15,715 crore, while revenue is ₹2,122 crore. In aggregate, this provides around 7.4 years of revenue visibility.
Let’s dive into three such component suppliers from India.
#1 Rossell Techsys: Order Book Hits ₹715 Crore
Rossell Techsys provides high-reliability engineering, manufacturing, and integration solutions to global Original Equipment Manufacturers (OEMs) and Tier-1 partners. Its primary product segments are Electrical Wiring & Interconnected Systems, Electrical Panel Assemblies, Electronic Systems and Systems Integration, and Automatic Test Solutions.
The company has a presence in both the aerospace and defence segments. Its manufacturing capabilities span both build-to-print (manufacturing to exact customer blueprints) and build-to-specification (designing and engineering custom solutions). The company operates from a certified facility in Bengaluru and has an additional unit in the USA.
Order Book & Multi-Year Revenue Visibility
To meet surging aerospace demand, they recently leased an additional 210,000-square-foot facility nearby to quickly scale up capacity. The aerospace business provides strong long-term revenue visibility through strategic agreements exceeding ₹3,000 crore. These are multi-year master agreements that represent the total value of programs over their lifespans.
As of March 2026, the company holds confirmed purchase orders (POs) for execution standing at roughly ₹715 crore. In the aerospace supply chain, confirmed POs are typically placed against the strategic agreements 6 to 12 months before delivery. This gives Rossell a clear, predictable outlook for at least the next three years.
Rossell is a critical supplier integrated into nearly every military platform originating from the United States. It maintains multi-year partnerships with industry giants such as Boeing, Lockheed Martin, Honeywell, and BAE Systems. A major highlight of its aerospace business is its strategic agreements worth US$200 million (roughly ₹1,900 crore) for Boeing’s T-7 program.
Value-Chain Scaling: Transitioning Rossell to 30% Margin Integrated Systems
Right now, Rossell’s aerospace strategy is to scale up harness production. From FY29, it plans to aggressively expand its content share on existing aerospace platforms. The plan is to transition from supplying individual wire harnesses and panels to delivering highly complex, integrated electromechanical systems and assemblies.
This vertical movement up the value chain is projected to significantly increase their revenue per platform and boost their profit margins to an estimated 21-30%. Rossell is also transitioning from a Tier-2 supplier in commercial aerospace to a direct player in the segment.
Rossell has already been shortlisted as a potential partner for these initiatives and expects to receive large-scale Requests for Proposals by Q2FY27. Management expects this to open the door to larger order sizes.
Rossell has also entered the Indian market for Maintenance, Repair, and Overhaul Services. This division is currently in its marketing phase, generating strong interest both domestically and globally. It is expected to command higher profit margins because it is a service-based offering.
FY26 Financial Performance: Revenue and Profit Analysis
Rossell delivered a structurally transformative financial performance in FY26. Revenue grew by 87% year-over-year to ₹485 crore. Aerospace and defence accounted for 80% of revenue during the year. Most of its revenue (around 98%) came from exports. Operating performance was also strong.
EBITDA surged by 73% to ₹66.6 crore with a margin at 13.7%. Net profit increased to ₹20.7 crore, up from ₹7.4 crore in FY25. Management expects the margin to improve to 17-22%.
In FY27, Rossell expects its revenue to grow by about 80-90%. While aerospace and defence will account for about 50% of the business in FY27, the non-aerospace segments are entering a hyper-growth phase. The space and semiconductor programs are expected to see a 300-400% increase in revenue during FY27.
Operational Efficiencies and Legacy Margin Risks
While revenue nearly doubled, inventory levels only increased by 45%. As a result, the company’s inventory coverage improved from a historical average of 10 months down to 7.7 months. Management aims to bring it down to a 4-month inventory cycle.
On the risk side, Rossell is still burdened by a legacy, loss-making Boeing order that continues to drag on its overall margins. After executing ₹75 crore worth of orders in FY26, it still has ₹70 crore left to execute in FY27. The majority will be executed in H1FY27. Raw material price volatility and dependence on exports remain another risk area to watch.

#2 Aequs: Backlog Secures ₹8,500 Crore Runway
Aequs Limited is an engineering-led, vertically integrated precision manufacturer. The company operates via its two primary business verticals: Aerospace and Consumer. It also has a presence in the defence industry.
Aequs operates a manufacturing infrastructure spanning 2.22 million square feet in India. Its global capacity is located in Paris, the US, and France.
The Belagavi Footprint: Capitalizing on End-to-End Localized Unit Logistics
A key differentiator for Aequs is its end-to-end manufacturing capability within a single Special Economic Zone (SEZ) in Belagavi. Through this, the distance components travel is reduced from thousands of kilometers to less than 500 meters. This enables unmatched lead times, cost control, and quality.
Portfolio Depth: Core Aerostructures and Strategic SKU Expansion
The Aerospace division is its growth engine, manufacturing highly complex parts for long-cycle, recurring aviation programs. It holds one of the most extensive aerospace product portfolios in India. The portfolio consists of 5,654 SKUs and over 1,150 parts in FY26.
Its capabilities encompass aerostructures (the bulk of the business), engine systems, actuation systems, landing systems, interior and cargo components, and assembly. For select products, the company achieves 100% in-country value addition.
Customer retention is a major strength, with the top 3 customers having an average relationship tenure of 15 years. Its blue-chip clientele includes Airbus, Boeing, Safran, Collins Aerospace, and SAAB. The aerospace revenue is export-driven. In FY26, exports accounted for 85% of revenue and 15% domestic. Approximately 93% to 94% of overall sales are linked to the US dollar.
Revenue Architecture: Monetizing Dollar-Linked Aviation Contracts
This segment showed strong growth in FY26. Revenue grew 76% year-over-year to ₹1,046.4 crore in FY26. EBITDA rose by 76% to ₹281.3 crore, with a margin at 27%. The Return on Capital Employed also expanded to 20%, up from 14% in FY25.
Order Book Metrics: Assessing the US $889-Million Growth Pipeline
Management aims to maintain an EBITDA margin of approximately 20% going forward. They have also guided for 25-30% revenue growth in FY27 and expect to sustain a 20%+ CAGR over the long term. On a consolidated level, the company expects to break even by H1FY28. This is because the consumer segment remains loss-making due to aggressive expansion.
Capital Infrastructure: Executing the Southern India Defence Corridor Capex
Aequs has multi-year plans to scale its aerospace segment, driven by a strong demand pipeline. The segment has an order book of US$889 million (roughly ₹8,500 crore). This provides revenue visibility of 8-9X the division’s FY26 revenue.
Ecosystem Scalability: Long-Term Capex Commitments in Southern Industrial Corridors
In addition, Aequs is strategically moving up the value chain to manufacture higher-margin landing gear and engine components. Revenue contribution from these engine components is expected to come from FY28. It is also investing ₹160 crore to expand its capacity in India. Further, Aequs has committed to two strategic expansions.
It plans to invest ₹1,900 crore over 10 years to create India’s first vertically integrated aero-engine and landing-gear manufacturing ecosystem in Tamil Nadu. It will also invest ₹2,856 crore over 5 years to expand its existing precision engineering ecosystem in Karnataka.
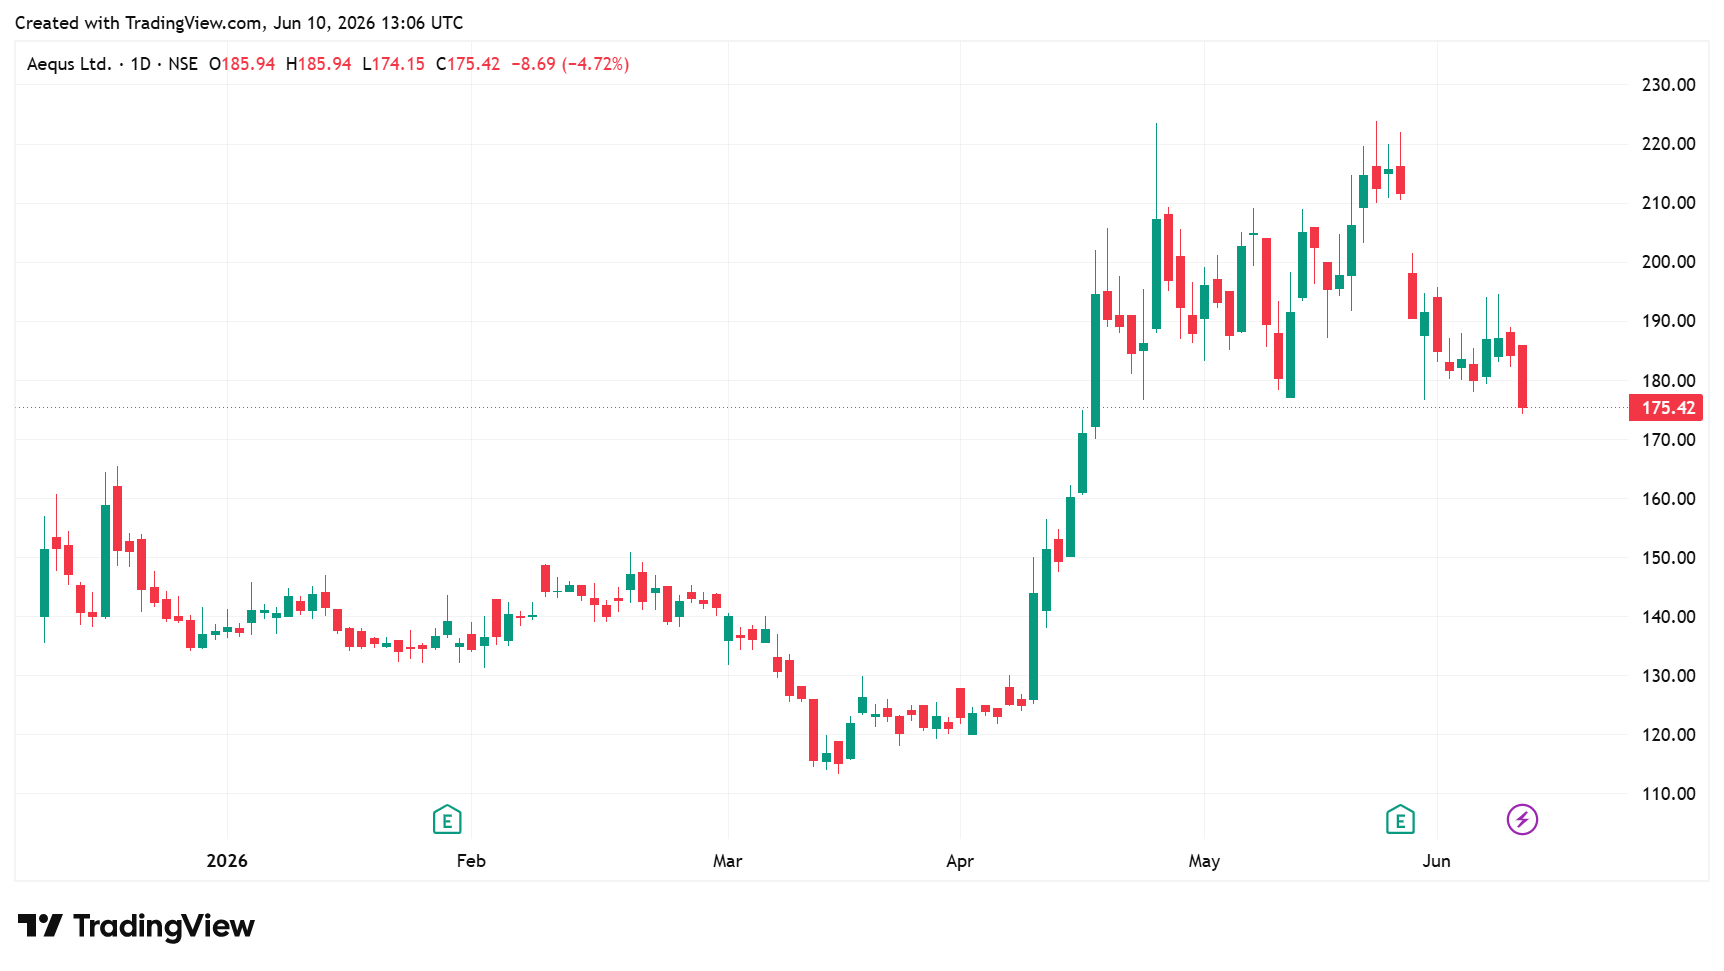
#3 Azad Engineering: Order Book Reaches ₹6,500 Crore
Azad Engineering supplies products such as actuator assemblies and components for hydraulic systems, which are essential to flight control and landing gear. Azad is a key supplier of critical assemblies to six of the major global manufacturers in the aerospace and defence industry.
Contract Sticky Vectors: Qualification Cycles and Tier-1 OEM Integration
Azad makes “mission and life critical” parts, including engine parts, assemblies, operational systems, and external structures. These components are used in the production of business jets, commercial airliners, defence aircraft, training jets, helicopters, and missiles.
The company wins business through highly rigorous, multi-year qualification cycles (often 30 to 48 months), resulting in sticky, long-term contracts.
Scaling the Aerospace and Defence Segment
The segment delivered 25.4% year-on-year growth in FY26, crossing the ₹100 crore mark for the first time. The segment is the key growth engine, accounting for 17.2% of standalone revenue in FY26. The company’s aerospace and defence segment has a rolling order book of over US $200 million (around ₹1,900 crore).
Management expects to become heavily diversified over the next 4 to 5 years. Management expects the energy segment contribution to normalise to 55-60% of revenue. At the same time, aerospace & defence and Oil & Gas are expanding to make up the rest. This indicates headroom for growth in the aerospace division.
Growth drivers include rising demand for commercial aircraft, fleet modernisation programmes, next-generation engines, and heightened global defence spending. Azad aims to increase its wallet share by entering into related segments.
Strategic Pipeline: Quantifying the Rolls-Royce and Global OEM Deals
On the order side, Azad signed a long-term deal with Rolls-Royce to produce Civil Aircraft Engine Parts for the lifespan of the Engine Program. Following a stringent 2.5-year qualification cycle, it expects to supply the first qualification batch in H2FY27. Supply momentum could pick up in Q4FY27 or early FY28.
In addition, the company signed a Master Terms Agreement and a Purchase Agreement with Pratt and Whitney to develop and manufacture aircraft engine components. Pratt & Whitney, followed by Safran, are next in line for component qualifications after Rolls-Royce. Honeywell Aerospace also awarded Azad a US $16 million (around ₹152 crore) order.
The company plans to further strengthen its presence with existing customers in the aerospace and defence sector. Since avionics is a key component of operational systems, this sector aligns with the company’s goal of increasing its market share. It aims to do so by expanding into critical components across various aircraft platforms and entering adjacent sectors.
Balance Sheet Analysis: Managing Working Capital Cycles and Inventory Expansion
Looking ahead, management remains confident in sustaining top-line revenue growth of 25% or more over a multi-year period starting in FY27. The total order book of ₹6,500 crore (including aerospace and defence) provides revenue visibility for 5-6 years. EBITDA margins are expected to be 33-35%.
From a financial perspective, its standalone revenue for FY26 increased 30.3% year-on-year to ₹590.4 crore. EBITDA was ₹217.6 crore with a margin of 36.9%. Net profit surged by 48.3% to ₹132 crore. Risk includes inventory buildup, with inventory days surging to 229 days in FY26, up from 155 days in FY25.
Azad states that the inventory buildup is a deliberate, strategic move to ensure readiness for committed production schedules at its newly commissioned plant. Trade receivables have also increased from ₹221.6 crore to ₹309.2 crore during the period.
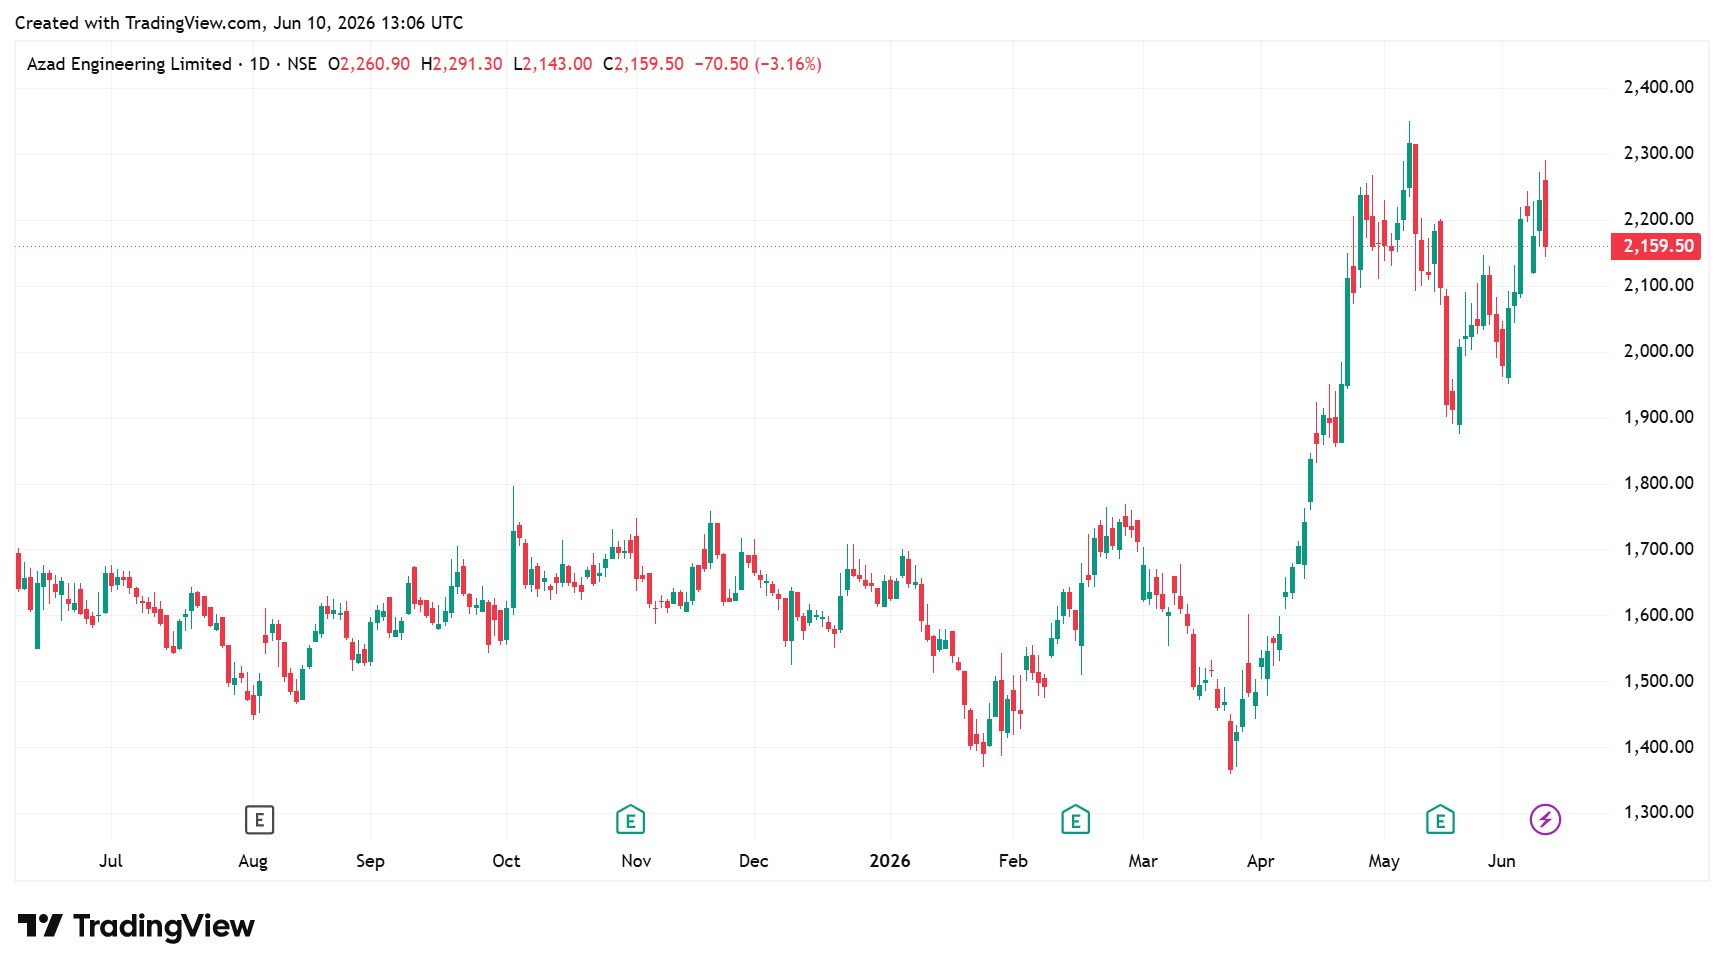
Aerospace Valuations: Analyzing the Sector Premia and Returns
Azad’s Return on Equity (ROE) and Return on Capital Employed (ROCE) are moderate due to the high level of capital investment to build out manufacturing capacity. Aequs’s aerospace segment has a strong ROCE at 20% (discussed above), but losses in other segments have dragged down operating performance.
Rossell Techsys’ return ratios are moderate due to a highly working-capital-intensive business model, front-loaded investments, and ongoing execution of the loss-making contract. For valuation, we have used the EV/EBITDA multiple and have not used the historical median due to insufficient data. Accordingly, all three are trading at a premium to the industry median.
Even on a standalone basis, their valuations remain high, likely due to their presence in a sunrise sector with a strong tailwind. This makes execution, margin stability, and order inflow crucial for all of them.
| Peer Comparison (X) | ||||
Particulars | EV/EBITDA Multiple | Return Ratios | ||
| Company | Industry | ROE (%) | ROCE (%) | |
| Rossell Techsys | 62.2 | 37.8 | 15.7 | 11.5 |
| Azad Engineering | 52.7 | 21.3 | 9.1 | 11.9 |
| Aequs | 73.0 | 37.8 | – | 1.6 |
| Source: Screener.in (As of 10th June 2026) | ||||
With global aircraft backlogs exceeding 15,255 orders and India’s aerospace manufacturing market projected to nearly double to ₹25,709 crore by 2030, the sector enjoys a long growth runway.
Companies supplying mission-critical components stand to benefit from rising aircraft production, defence spending, and localisation. However, rich valuations mean investors will need to closely track execution, margins, and order inflows going forward.
As strong contenders, these stocks are worth keeping on your watchlist.
Disclaimer:
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation. Only in cases where the data was unavailable have we used an alternative, widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
About the Author: Madhvendra has been deeply immersed in the equity markets for over seven years, combining his passion for investing with his expertise in financial writing. With a knack for simplifying complex concepts, he enjoys sharing his honest perspectives on startups, listed Indian companies, and macroeconomic trends.
A dedicated reader and storyteller, Madhvendra thrives on uncovering insights that inspire his audience to deepen their understanding of the financial world.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources, and only after consulting such independent advisors as may be necessary.