



India’s solar sector continues to expand as the country adds renewable capacity and pushes for greater use of clean energy. Government-backed programmes are also supporting demand for solar modules, EPC services and distributed solar projects.
However, strong sector growth does not automatically make every solar-linked SME attractive. Smaller companies can face execution risks, working-capital pressure and volatile order flows.
We therefore applied a quality screen to identify financially stronger SME companies with meaningful exposure to the solar opportunity. The screen requires ROCE above 15%, debt-to-equity below 0.5 and positive operating cash flow. It also looks for three-year sales and profit growth above 10%.
Promoter holding must be above 30%, with no promoter pledging. Operating margin must be above 10%. Market capitalisation must also be above Rs 100 crore.
Two SMEs from the screen stand out. Both have meaningful exposure to the solar sector. They have also delivered strong profit growth and ROCE of more than 30%.
Neither is a pure-play solar company. Their businesses also extend to other segments. Still, solar remains an important part of their growth opportunity.
Let’s take a closer look at these two SMEs.
#1 Ganesh Green Bharat: Solar Manufacturing and EPC
Incorporated in 2016, Ganesh Green Bharat specializes in Solar PV module manufacturing, solar systems and allied services, electrical contracting, and water supply scheme projects.
Solar Manufacturing Adds Scale to the Growth Story
Three-year sales and profit CAGRs of 132% and 110%, respectively, support its inclusion among our selected SMEs. ROCE stands at 36.8%.
The company’s FY26 annual report shows that solar has become an important part of its business. Ganesh Green manufactures solar PV modules and also undertakes solar EPC projects. Its offerings include ground-mounted systems, rooftop solar, solar street lighting and agricultural pumping systems. Ganesh Green AR
The manufacturing business is also being scaled up. Its May 2026 investor presentation shows a fully automated solar PV module manufacturing capacity of 1.1 GW. Management plans to increase this to 2 GW by the end of 2027. The company also manufactures N-type TOPCon bifacial modules with power output of up to 650 watt-peak.
Solar Orders Add Revenue Visibility
Ganesh Green’s solar exposure goes beyond module manufacturing. It also provides end-to-end EPC services covering project development, engineering, execution and operations and maintenance.
Its investor presentation shows Rs 470.2 crore of unexecuted solar-module orders. Another Rs 207.7 crore comes from solar allied services. This includes solar water pumping, rooftop projects, solar power plants and solar street lighting.
The company is also entering battery energy storage system EPC. Its planned capabilities cover project engineering, battery and inverter integration, grid interconnection, commissioning and O&M. This could widen its clean-energy opportunity beyond conventional solar projects.
FY26 revenue rose 234.7% YoY to Rs 1,064.7 crore from Rs 318 crore. Net profit increased 148.8% YoY to Rs 75.2 crore from Rs 30.22 crore. Operating margin, however, moderated to 10.7% from 14.9% in FY25.
Ganesh Green is not a pure-play solar company. Electrical and water infrastructure remain part of the business. Its rapid expansion also brings execution and working-capital risks. Investors should also watch whether margins stabilise as the company scales manufacturing and executes its large order pipeline.
To know more about the company’s financial performance, growth, order book and broader infrastructure business, read 4 SME stocks riding India’s infrastructure boom.
Ganesh Green Bharat Financial Performance
| Metric | FY26 |
| Revenue | Rs 1,064.3 crore |
| Revenue growth | 234.7% YoY |
| Net profit | Rs 75.2 crore |
| Profit growth | 148.8% YoY |
Source: Ganesh Green Bharat’s FY26 annual report
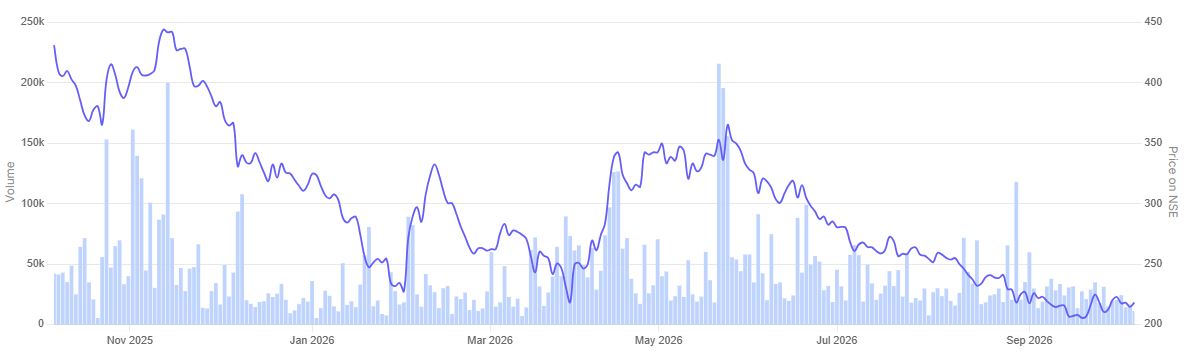
In the past year, the share price of Ganesh Green Bharat is down 49.4%.
Ganesh Green Bharat 1-Year Share Price Chart
Source: Screener.in
#2 GRE Renew Enertech: Solar EPC Growth Backed by 35.2% ROCE
GRE Renew Enertech is engaged in the business of solar energy solutions and LED lighting products.
Solar EPC Execution Supports the Growth Story
Three-year sales and profit CAGRs of around 50% and 150%, respectively, support its inclusion among our selected SMEs. ROCE stands at 35.2%.
The company’s FY26 annual report shows that solar is now central to the business. GRE operates through both EPC and RESCO models. Under EPC, it handles design, procurement, construction, commissioning and O&M. Under RESCO, it owns solar assets and earns recurring revenue through long-term power purchase agreements.
Solar EPC accounted for the bulk of the business. The company crossed 100 MWp of cumulative solar installations by June 2026.
Larger Projects Drive the Next Phase of Expansion
GRE is now moving towards larger utility-scale projects. It secured its biggest solar EPC order so far. The Rs 175 crore contract covers a 50 MW AC/65 MW DC ground-mounted project in Maharashtra.
Its order book stood at Rs 248.01 crore, including GST, as of July 15, 2026. This represented around 82 MW of DC solar capacity. The company is also expanding its RESCO portfolio. Its June 2026 investor presentation projects RESCO assets rising from 3.83 MW in FY26 to 15.53 MW in FY27.
FY26 consolidated operating revenue rose 46.8% YoY to Rs 122.92 crore. Net profit increased 93.3% to Rs 13.58 crore. FY26 operating margin was around 13%. Debt-to-equity remained low, while debtor days stood at 31.
Promoter holding stood at 69.99% in June 2026. However, investors should watch execution risk as GRE moves into larger projects. Working-capital requirements may also rise with scale. The company is listed on the BSE SME platform and does not report quarterly financial results. This leaves longer gaps between financial updates and SME shares can also carry liquidity risks.
GRE Renew Enertech Financial Performance
| Metric | FY26 |
| Revenue | Rs 122.92 crore |
| Revenue growth | 46.8% YoY |
| Net profit | Rs 13.58 crore |
| Profit growth | 93.3% YoY |
Source: GRE Renew Enertech’s FY26 annual report
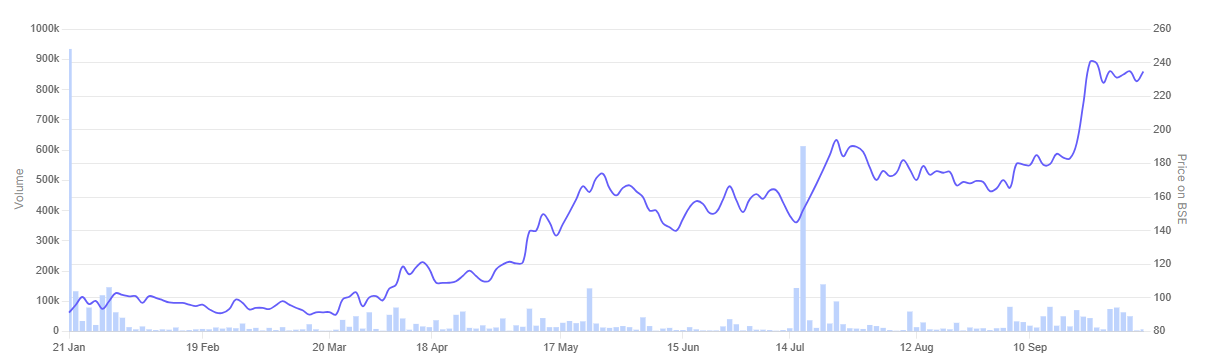
In the past year, the share price of GRE Renew Enertech rallied 157.5%.
GRE Renew Enertech 1-Year Share Price Chart
Source: Screener.in
Conclusion
India’s solar opportunity is expanding, but the quality of individual businesses still matters. Strong sector tailwinds alone are not enough. Investors also need to look at execution, capital efficiency and balance-sheet strength.
The two SMEs highlighted here combine direct solar exposure with healthy growth and strong return ratios. Their business models also give them exposure to different parts of the solar value chain, from manufacturing and EPC execution to renewable asset ownership.
However, both are SME-listed companies. Liquidity can be lower and business performance can be more volatile. Project execution, working-capital requirements and changes in government policy also remain key risks.
For investors, the key question is whether these companies can sustain their growth while maintaining margins and return ratios as they scale.
Two Quality SMEs Riding India’s Solar Boom: Growth and Operating Performance
| Metric | Ganesh Green Bharat | GRE Renew Enertech |
| Three-year sales CAGR | 132% | 50% |
| Three-year profit CAGR | 110% | 150% |
| ROCE | 36.8% | 35.2% |
| FY26 operating margin | 10% | 13% |
| FY26 debtor days | 25 | 31 |
| FY26 operating cash flow (Rs crore) | 13.0 | 5.28 |
Sources: Screener data for growth, ROCE, operating margins and debtor days; FY26 annual reports of Ganesh Green Bharat and GRE Renew Enertech for operating cash flow.
You can track how these are progressing by adding stocks to your watchlist.
Disclaimer
Note: We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Ekta Sonecha Desai has a passion for writing and a deep interest in the equity markets. Combined with an analytical approach, she likes to deep dive into the world of companies, studying their performance, and uncovering insights that bring value to her readers.
Disclosure: The writer and her dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.