



India’s defence spending is increasingly moving from policy announcements to a visible pipeline of orders for domestic manufacturers. The latest move adds another large opportunity to this pipeline. On 7 September, the Defence Acquisition Council approved capital acquisition proposals worth around ₹1.10 lakh crore, covering equipment for the Army, Navy and Air Force.
More importantly, around 98% of the proposed procurement is expected to come from Indian industry. This would benefit key Indian defence players. The timing is significant for the domestic defence ecosystem. The government has budgeted ₹2.19 lakh crore for capital outlay on defence services in FY27, up from ₹1.86 lakh crore in the revised FY26 estimate.
This creates a larger pool of spending for platforms, mobility equipment, electronic warfare systems, radars, helicopters and other mission-critical systems. The latest approvals also show the opportunity isn’t limited to one part of the defence supply chain.
Join here
The Army will require high-mobility vehicles, helicopters, bridging systems, and mine-laying equipment, while the Navy is looking at radars and indigenous marine gas turbine technology. Meanwhile, the Air Force has received approvals for electronic warfare and fleet upgrades. Against this backdrop, this article examines four primary beneficiaries of this defence proposal.
#1 Hindustan Aeronautics: High-Margin MRO and ALH Dhruv Scale
Hindustan Aeronautics stands to benefit the most from this ₹1.1 lakh crore clearance. It is the main integrator for the Advanced Light Helicopters (ALH) program. Its indigenously developed ALH is called the Dhruv.
The pipeline includes 143 ALH units, costing approximately Rs 400-500 crore per helicopter. This contract will be a major contributor to ₹90,000 crore of fresh contracts HAL expects to receive over the next 2 years. To handle this increased volume, HAL has expanded its helicopter division production facilities.
HAL secured several key helicopter contracts during FY26, boosting its order book. These major contracts include supplying 6 ALH Mark III MR to the Indian Coast Guard and 10 ALH Dhruv NG to Pawan Hans. HAL’s current order book includes 21 ALH helicopters in active execution.
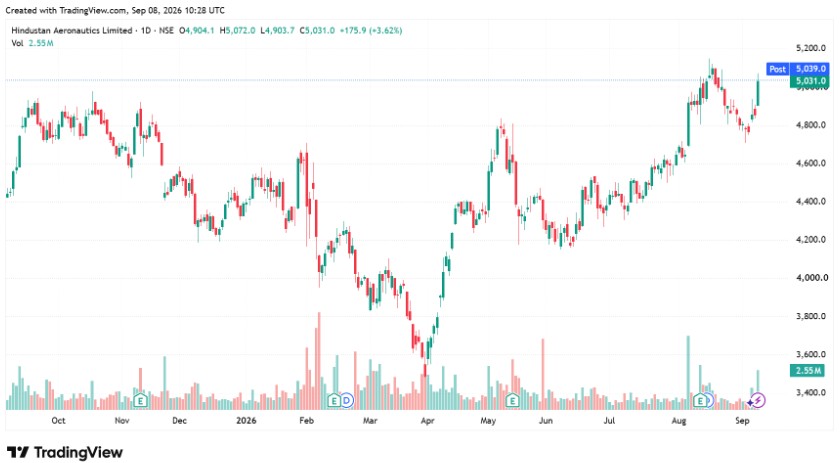
Additionally, HAL is targeting delivery of eight ALH helicopters to Pawan Hans and five more to other partners, all on track. HAL continuously supplies about 20 to 25 ALH helicopters every year, which also helps scale its repair and overhaul service pipeline as the platforms age. As of 31 March 2026, HAL’s order book stood at ₹2,54,538 crore.
For FY27, HAL expects to transition from its previous 7% growth rate to a steady double-digit revenue growth of 10% to 12%. Profitability is projected to remain stable, with management confidently maintaining an EBITDA margin of 30% to 31%. It plans to shift its revenue mix from the current 30:70 split between manufacturing and repair & overhaul to 50:50.
#2 Bharat Electronics: Radars, DIRCM Suites, and Anti-Drone Growth
Bharat Electronics (BEL) is a key player in several systems. The company is involved in Chemical, Biological, Radiological, and Nuclear (CBRN) reconnaissance vehicles, the Arudhra radar (lead developer), ground-based multi-purpose jammers, and ALH avionics systems. Larsen & Toubro could also benefit from the CBRN and Arudhra radar systems.
The Arudhra radar is a key project for BEL’s order book and execution pipeline. It is among the top seven pending projects in its order book. BEL expects significant revenue from this program, with turnover estimated between ₹500 crore and ₹1,000 crore. The company is also expected to benefit from ALH Avionics and Systems.
BEL has initiated a project to customise and integrate a Directed Infrared Countermeasure (DIRCM) for ALH during FY26. DIRCM is a critical Electronic Warfare suite designed to protect the helicopter against infrared-guided threats. The company also won orders for the EW suite for helicopters in FY26.
To capitalise on future opportunities in this segment, BEL has established a dedicated Avionics Systems business Unit at its Bangalore Complex. The goal is to maintain a focused, concerted approach to the airborne and helicopter avionics market. BEL also has a robust presence in the jammers segment.
BEL is active in the jamming domain. Under its non-defence segment, BEL develops and supplies classroom jammers and vehicle-mounted jammers. It indigenized the Infrared Jammer in FY26. This is part of BEL’s aggressive indigenisation drive designed to build self-reliance and protect margins.
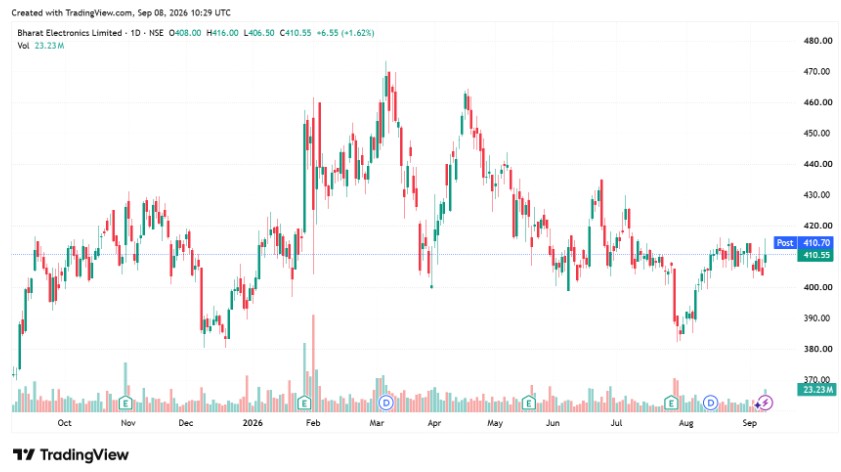
In the rapidly expanding drone and counter-drone market, BEL works on complex multi-layered solutions. While the company focuses on large, complex hard-kill systems, it also uses EW jammers designed to kill or bring down drones. As of July 2026, its order book stood at ₹72,258 crore.
#3 Bharat Earth Movers Limited: Heavy Mobility Systems and Armoured Vehicle Trawls
Bharat Earth Movers Limited (BEML) is expected to benefit from the Sarvatra Bridge System, High Mobility Vehicles, and Trawl Tanks. BEML has a major presence in the High Mobility Vehicles (HMV) segment, with over 9,500 HMVs supplied to date.
The company recently developed the HMV 1212 and is developing high-speed road-based vehicles for long-range surface-to-air missiles. Additionally, it is actively looking to export HMVs to integrators for final delivery to ministries of defence in West Asia. It has also supplied 6 sets of Pontoon Bridge Systems.
Moreover, tank trawls are one of its premier In-house Developed Products under its defence portfolio. The company has supplied over 1,170 units of Track-Width Mine Ploughs till June 2026. Tank Trawls are combat attachments mounted on the nose of battle tanks to sweep or clear landmines specifically from the path of the tank’s tracks.
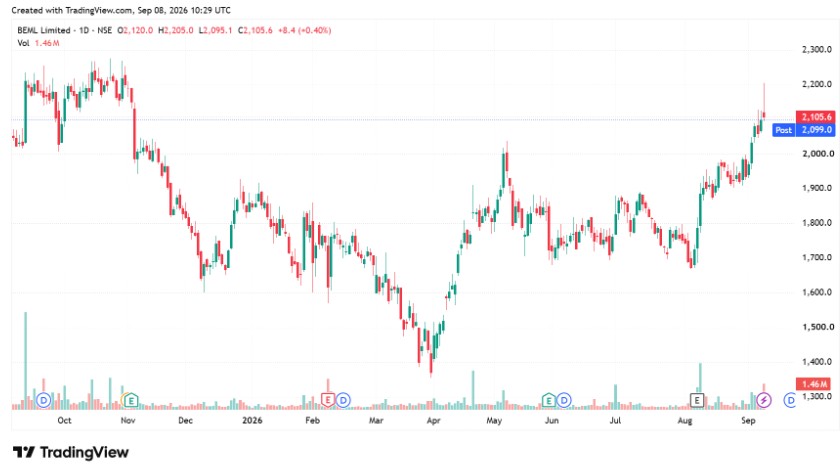
BEML’s defence business grew 25% in Q1FY27, while overall revenue grew 29%. The management expects similar or better growth in subsequent quarters. BEML’s order book stands at slightly above ₹16,000 crore, with the defence segment accounting for around 25%.
The company is targeting ₹20,000 crore in new orders, of which 20% is expected to come from the defence segment. In addition to BEML, Ashok Leyland and Mahindra & Mahindra are other players expected to benefit from the high demand for mobility vehicles.
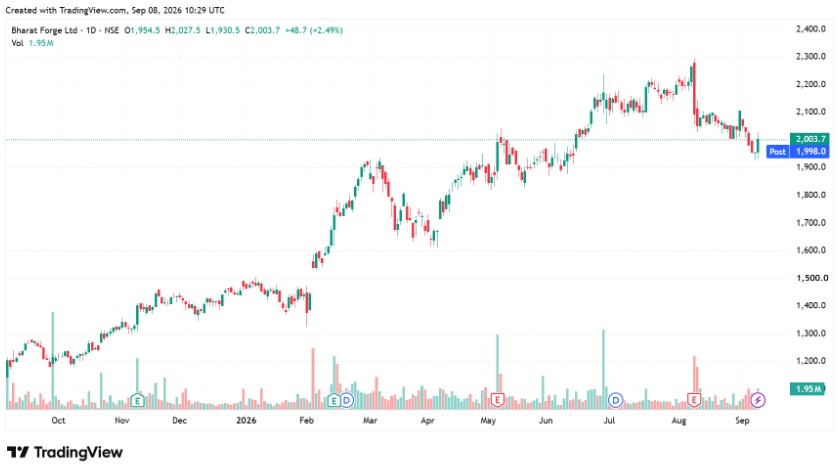
#4 Bharat Forge: Navigating Gas Turbines into Maritime Power
Bharat Forge is the beneficiary of Marine Gas Turbines (MGT). The company won a landmark order for marine gas turbine generators for the Indian Navy’s Kolkata-class ships. It represents the company’s largest naval systems order to date and marks a strategic entry into shipboard power generation.
The company has developed a range of turbines for naval applications, ranging from 1.25 MW to over 25 MW. These turbines are engineered as multi-fuel systems. The product is fully developed and has entered the testing phase. Bharat Forge will manufacture the entire turbine in-house.
Historically, Bharat Forge’s presence in the naval sector was restricted to shafting and propellers. Winning power-generation contracts allows it to capture the entire propulsion and power value stream. This significantly increases the revenue potential per ship, especially with the Indian Navy’s plans to build 140 new ships.
The defence business’s outstanding order book reached a record ₹11,196 crore as of Q1FY27. Deliveries for major domestic orders are set to commence in H2FY27 as the new defence facility enters serial production. Bharat Forge aims to grow its Indian manufacturing operations at a 15% CAGR over the next five years, with profits projected to rise even faster.
Execution Realities vs. Multiples
BEL boasts a higher Return on Capital Employed (ROCE) and Return on Equity (ROE), followed by HAL, Bharat Forge and BEML. Valuation-wise, both BEML and Bharat Forge trade at a significant premium to the industry median and their own 3-year historical median. Meanwhile, HAL and BEL trade near their historical medians but at a significant discount to the industry.
| Peer Comparison (X) | |||||
Company | Price-to-Earnings Multiple | Return Ratios | |||
| Company | 3Y Median | Industry | ROCE (%) | ROE (%) | |
| HAL | 36.2 | 34.6 | 87.4 | 32.0 | 24.0 |
| BEL | 48.8 | 49.4 | 87.4 | 36.4 | 27.4 |
| BEML | 98.6 | 58.8 | 30.5 | 7.7 | 4.8 |
| Bharat Forge | 94.7 | 67.0 | 29.8 | 12.6 | 12.0 |
The ₹1.10 lakh crore DAC approval adds meaningful visibility to an already expanding defence order pipeline. HAL has the largest direct exposure through the ALH program, while BEL could benefit across radars, electronic warfare and helicopter systems. BEML gets exposure to mobility and bridging systems, and Bharat Forge is moving deeper into naval power systems.
The next phase will therefore depend on how quickly these companies convert approvals into contracts, production and revenue. Nonetheless, you could keep these names on your watchlist to track their execution.
Disclaimer
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation. We used an alternative, widely used, and accepted source of information only when the data was unavailable.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, we strongly advise you to consult your advisor. This article is strictly for educational purposes only.
About the Author: Madhvendra has been deeply immersed in the equity markets for over seven years, combining his passion for investing with his expertise in financial writing. With a knack for simplifying complex concepts, he enjoys sharing his honest perspectives on startups, listed Indian companies, and macroeconomic trends.
A dedicated reader and storyteller, Madhvendra thrives on uncovering insights that inspire his audience to deepen their understanding of the financial world.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities, or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives and resources, and only after consulting any independent advisors as may be necessary.