


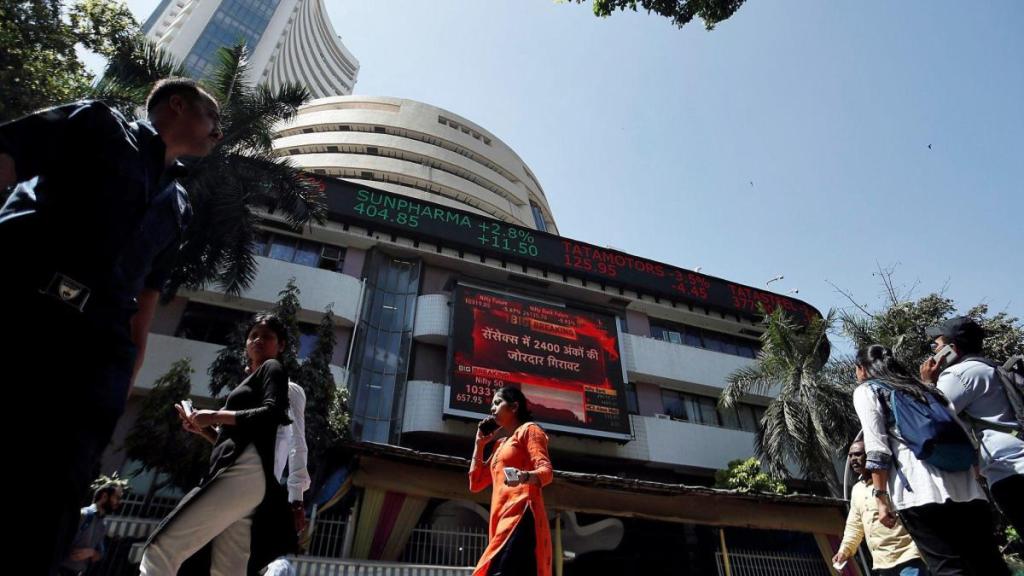

BSE’s weekly derivatives expiry triggered another bout of extreme volatility during the closing auction session (CAS) on Thursday, with the Sensex’s indicative closing level plunging more than 2,100 points before staging an equally sharp recovery – in all, swinging by almost 4,000 points (3,900 point) in two mins.
The indicative Sensex level tumbled from 76,510 at 3:18 pm to 74,373 at 3:20 pm — a fall of 2,137 points — before recovering by 1,800 points. The benchmark eventually closed at 76,153, down 417 points, or 0.55%, from its previous close.
The violent swings spilled over into the derivatives market, with Sensex put-option premiums surging 400-500% within minutes.
Thursday’s episode comes just a week after the index witnessed a similar dislocation during the monthly futures and options (F&O) expiry. The Sensex’s indicative closing level had then plunged more than 2,500 points, or 3.4%, during CAS before recovering. The recurrence of such sharp moves on expiry days is adding to concerns over liquidity and price discovery during the new closing mechanism.
Thin Liquidity
Gaurav Arora, head of research at SAHI, attributed Thursday’s plunge to a large one-sided sell order hitting an almost empty order book.
“Market orders are allowed between 3:20 and 3:25, and a market sell with nothing behind it falls straight to the lowest buy price available. Expiry flow made it heavier,” Arora said. Low trading volumes on BSE amplified the move, while the rapid recovery suggested that the order was either withdrawn or fresh buyers stepped in, he added.
Liquidity remains a key concern. BSE’s average daily CAS turnover stands at just Rs 54.34 crore, equivalent to around 0.50% of its average daily cash-market turnover of Rs 10,970 crore. It is also a fraction of the average cash-market turnover on the National Stock Exchange (NSE), which stands at Rs 1.19 lakh crore, with the CAS average at Rs 2,825 crore.
Operational since August 3, CAS has completed its first month with mixed results. While the mechanism has found acceptance among institutional investors and demonstrated its utility during the recent MSCI index rebalancing, sharp expiry-day swings, declining derivatives turnover and concerns over possible manipulation have emerged as key challenges.
Regulatory Scrutiny
Its first month has already seen regulatory action. The Securities and Exchange Board of India (Sebi) barred JPMorgan Chase & Co-owned Copthall Mauritius Investment and Mansi Share and Stock Broking from the securities market for alleged manipulation during CAS and ordered the impounding of Rs 3.68 crore in alleged gains through an ex-parte interim order.
Market participants say some features of the auction mechanism may themselves be discouraging participation and aggravating the liquidity problem.
Arora said traders find their “safety net” disappearing when they need it most because basic tools such as stop-loss and iceberg orders are unavailable during CAS. There is also a mismatch between the cash and derivatives markets: the regular cash market shuts at 3:15 pm while index derivatives continue trading until 3:40 pm.
He likened the arrangement to “one leg moving while the other stands frozen”.
The risk, according to Arora, is that the problem becomes self-reinforcing. If trading desks lose confidence in the closing mechanism, they may complete their trades earlier or quote wider spreads during the auction. That would further thin the order book, making it more vulnerable to outsized price swings.
He suggested measures such as easing the securities transaction tax (STT) for trades during CAS and extending the auction whenever the indicative closing price deviates sharply from the reference price, a safeguard used in several overseas markets.
A senior brokerage official was more critical, arguing that CAS has so far failed to achieve its objective of improving price discovery and remains vulnerable to manipulation.
“No one is able to take a view due to the volatility in the closing auction, and so most market participants avoid it,” the official said.